Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Investing in the Cannabis Market

Five months into the legalized marijuana market, it’s a good time to remind ourselves of basic investment principles. Get good advice you trust.
 

By Kevin Greaves, MyResolver.ca

Special to the Financial Independence Hub

Perhaps not since the dot com boom of the 1990s have we seen the kind of investor interest in a sector that we’re now seeing in the marijuana market.  Seasoned investors and newcomers alike are excited by the prospects of this nascent market and risk is rampant.  In the months leading up to, and the four months following legalization in Canada, there has been huge volatility in stock prices for some of the major players and the valuations of many of these companies is often characterized as ‘out of whack’.   For instance, market leader Tilray (TSX:TLRY) was valued greater than American Airlines Group in September 2018.  That is high! (Pun intended)

So, if you’re looking to add marijuana stocks to your portfolio, there’s a lot to take in at the moment.  It’s not easy to keep on top of the news of mergers, partnerships, earnings reports and growth forecasts in an emerging sector, and you could find yourself caught up in the hype.  So first and foremost, it’s good to work with a trusted investment advisor.  An advisor can help to put disclosure documents in perspective and assist in choosing an investment that suits your financial goals. Even if you are an experienced investor, accustomed to doing your own research and trades, having an advisor to confirm or correct your strategies, even just initially, could help you avoid some costly mistakes.  There are plenty of articles on the value of an advisor, and how to find one, so that’s not a topic we will cover in depth here.

Investor or Speculator?

Warren Buffett’s mentor, Benjamin Graham believed it was crucial to determine whether you are acting in the market as an investor or a speculator.  The distinction is fairly simple.  As an investor, you buy a stock in a company you believe will be successful and that stock represents ownership in the company.  You have a stake in the future of that company.  As a speculator, your only concern is what someone will pay for that stock down the line.

Some would argue that all investment is a combination of the two but it’s an important differentiation to make when you are working with an emerging market sector.  It allows you to clarify your expectations and often, the timeline for your ROI and the amount of risk you are prepared to take.

It’s important to remember that marijuana is a commodity: plain and simple.  And as a commodity it is subject to the same booms and busts as other commodities.  As an agricultural commodity it holds additional risks.  Think of all the uncertainties of growing any crop:  the introduction of a single pest can wipe out an entire harvest.

Consider ancillary products and players

There are opportunities beyond investing in producers of marijuana and if you’re considering investing in this sector, you may want to look beyond the obvious.  Certainly, Biotech stocks have been around for decades but with more and more information available regarding the medical uses of cannabis, there will be expanded opportunities for companies to develop drugs and treatments for various diseases, conditions and illnesses.  For instance, creams and oils derived from CBD, the non-intoxicating compound of the marijuana and hemp plants, have shown great promise in the treatment of epilepsy and arthritis.
Continue Reading…
U.S. Economy Watch: Searching for Clues


By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

After at least a month-long delay, fixed income investors have finally been receiving economic data. With a number of government agencies closed due to the recent shutdown, 2019 began with a data vacuum, but now it looks like we are making up for lost time. Unfortunately, these “data delays” render some of the economic information potentially old or stale. Nevertheless, the data still offers insights as to how 2018 ended and can provide clues on any possible springboard effects for the current year.

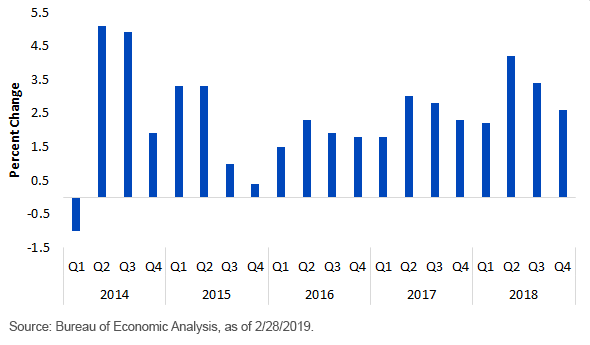
A perfect case in point is last month’s release of the Q4 2018 real GDP report. Yes, the data is three months old, but the underlying components in this release can offer insights for the future. First, let’s go high level and look at some headline numbers. For Q4, the Bureau of Economic Analysis’ (BEA) initial estimate for growth was pegged at +2.6%. While this was a drop-off from the Q3 pace of +3.4%, it beats consensus forecasts by nearly half a percent. For 2018 as a whole, real GDP came in at +2.9%. This rate of expansion has been reached only two other times since 2005. On a Q4/Q4 basis, growth was pegged at +3.1%, finally eclipsing the elusive 3% threshold.

U.S. Real GDP

US Real GDP q4 2018

While recession fears have been a part of the economic dialogue, the ongoing debate seems to be more centered on what type of slowdown we should expect in 2019. The accompanying graph illustrates that growth has trailed off a bit after reaching its most recent high-water mark of +4.2% in Q2. Some further deceleration is likely. In fact, Q1 2019 real GDP will likely be held down by the aforementioned shutdown, but then snap back in Q2 as those negative effects are reversed. Overall, real GDP in the area of +2¼% is my base case for this year.

Let’s take a look at the GDP engine cylinders:

Personal consumption expenditure (PCE): Household spending rose at a +2.8% annual clip in Q4, which translated to a 1.9 percentage point (pp) contribution to growth. This component should continue to be a positive force for the economy this year. Continue Reading…

Real Estate Investing: The good and bad of investing in real estate

By David Miller, CFP, RFP

Special to the Financial Independence Hub

Real estate can be a differentiator in a diversified investment portfolio. But when you watch the pundits in the media and certain TV network shows, as seen on HGTV, buying, flipping or renting a property seems like a sure way to increase your income or get rich quick. As glamourous as it seems when you take a sledgehammer to a useless wall to ‘open up the space’, the reality of making it a marketable investment is often much more daunting. What really is daunting is the sheer number of options you have when it comes to investing in real estate, and the obvious question is:

Does it make financial sense to add real estate to your portfolio?

The Positives

Real Estate does make sense in most investment portfolios but let us back up a little bit here and provide some context:

What are the primary reasons people choose real estate as an investment?

There is something reassuring about investing in real estate, as in the case of owning a rental property. You own a tangible asset and you may feel like you can see the value and the risks just by walking through the property. You may own your home, and assuming you are mortgage free, brings an incredible feeling of security and freedom.

Real estate investing can offer a stable, reoccurring income; after all, ‘who doesn’t pay their mortgage or rent?’ It also carries a fairly high certainty of a higher value over the long term; after all, “they are not making more land” (unless you’re in the South China Sea or Dubai). These are two common positive arguments.

If you look specifically at Canada, there can be times when your rate of return can be incredibly high. We experienced this with Calgary’s real estate boom from 2005-2007. The Greater Toronto Area and Greater Vancouver area from 2015-2018 have seen incredibly high growth and price increases that have been covered extensively through the media.

Real estate investing provides an interesting option that is not directly tied to overall stock market risk, which can provide you with increased diversification. Whether the stock market goes up or down, your real estate price may move independently.

The wealthy endowment funds, private pensions, institutional money and the Canada Pension Plan invest heavily in real estate, private equity and infrastructure projects that average Canadian investors either don’t know about, can’t invest or don’t invest into.

To summarize, the benefits of a real estate investment are that it is a tangible, generally stable income producing, ‘always goes up’ investment and offers other benefits not seen in the stock market. Ready to jump in with both feet? Not so fast. There are some serious pitfalls to understand and multiple options to choose from.

How can I invest into real estate?

  • Buy a rental property (putting at least 20% down)
  • Buy a commercial building
  • Real Estate Investment Trusts (REITs)
  • Exchange Traded Funds (ETFs) of REITs
  • Mutual funds specializing in real estate
  • Private equity or debt (Mortgage pools/investment corps)

Primary Issues

Price Risk

Can real estate values fluctuate? The real answer is yes. Nationally, Canadian housing prices reduced by 4.9% on average in 2018, the worst performance since the 2008 financial crisis. Toronto and Vancouver skew the average price to high side, but even they are starting to fall off their 2017/18 highs and there are obvious concerns of a bubble bursting.

Prices for real estate are difficult to gauge as every property is different and value is in the eye of the beholder. To sell your property, you likely need to employ a realtor to get a starting price and you need to find someone else who agrees on the price to buy. Real estate negotiations can go awry quickly, which causes further delays regarding the liquidity. For this service, there is a sales cost paid to the realtor, usually 7% of the first 100,000 and 3% after, although this can be sometimes negotiated.

In an example of how poor the Calgary commercial real estate market is; this*is an article that explains how the city of Calgary is losing over $300 million in tax revenue every year as downtown core commercial property values have decreased by a collective $12 billion. This is an example of how real estate values can fluctuate to the downside and how unstable a source of income a real estate investment could be.

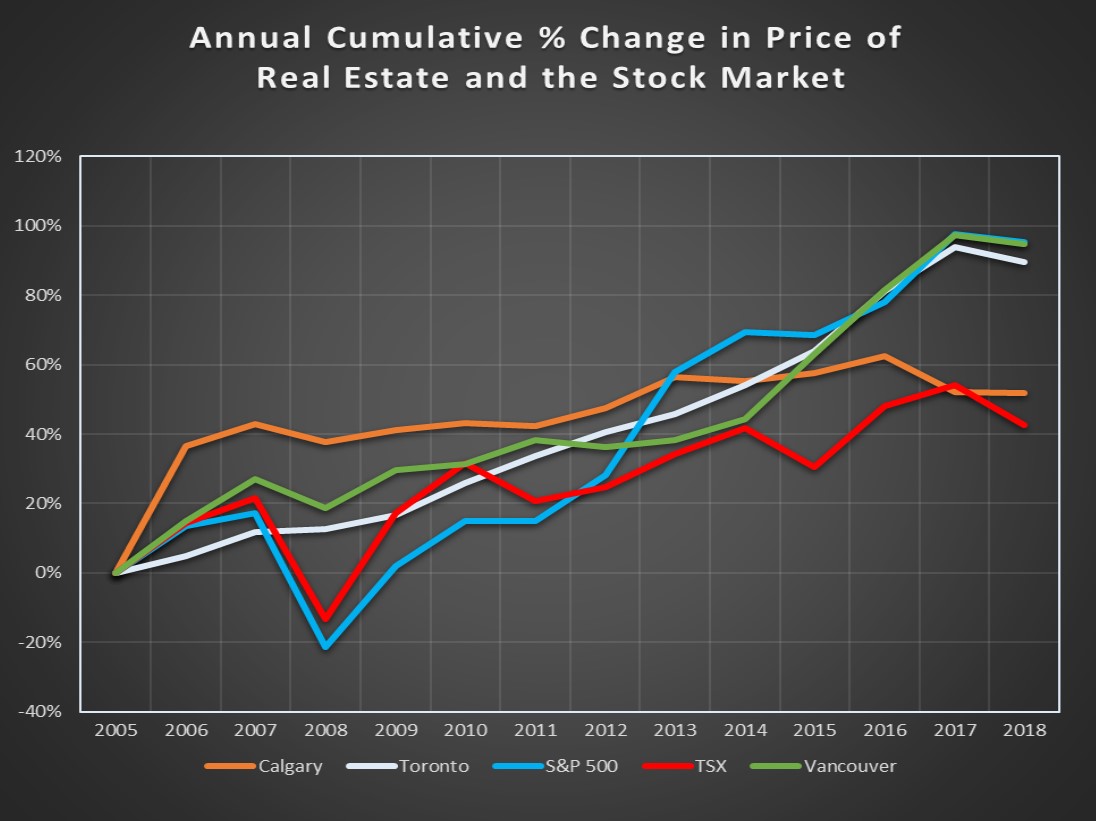
See the chart below for the relative volatility of the selected Calgary, Toronto and Vancouver markets when compared with the US Equity and Canadian Equity markets. While the annual volatility in the S&P 500 and TSX has been much higher relatively, this chart shows that you could lose out if you sell your real estate holding at the wrong time or pick the wrong city or neighbourhood to invest in.


Calgary data via CREB Monthly Average Sale Price “Attached, Detached, Apartment”, Jan 2005 to Dec 2018. Vancouver Data via CREA.ca HPI Tool Greater Vancouver Composite historical price data Jan 2005 to Dec 2018. Toronto Data via CREA.ca HPI Tool Greater Toronto Composite historical price data Jan 2005 to Dec 2018. TSX data via tmxmoney.com price history. S&P 500 data via http://www.multpl.com/s-p-500-historical-prices/table/by-year. The chart above only looks at price change and does not factor the effects of leveraging or reinvestment of interest or dividends.

Liquidity Risk

Liquidity refers to how quickly you can get your money out if you change your mind about your investment. Are you prepared to invest money into a residence only to find out it’s a money pit? What happens when you struggle to sell it when the market turns, and you could really use the extra money for something else? What if there is an emergency and you need those funds and there is no liquidity? If you are buying a stock or ETF on a major open market, the level of liquidity can be measured in volume of shares bought or sold and shares usually change hands instantaneously. While investing in stocks should be a long-term investment, at least you have the option to get out at any time almost instantly. The same is generally true in real estate; however, the liquidity premium is significantly higher. Continue Reading…

Alternative assets in ETFs and mutual funds, including a new one from Franklin Templeton


Alternative asset classes like private equity and real estate have long been in vogue with pension funds, institutional investors and some high-net-worth individual investors but the pickings have been slim for retail mutual fund investors. Now, Franklin Templeton Investments Canada has introduced the Franklin K2 Alternatives Fund.

The company says its new mutual fund, announced on Monday, March 11, uses “a multi-strategy approach in seeking to dampen volatility and offer downside protection, while providing added diversification and low-correlation to asset classes typically held in a traditional portfolio.

Franklin Templeton Canada Duane Green pointed to the unpredictable market environment of the past year and said “investors are looking to reduce volatility and protect capital … Our alternatives fund addresses these investor needs and combines the benefits of a sophisticated solution with the liquidity, convenience and fee transparency of a mutual fund.”

In a piece this weekend in the Financial Post, which mentioned the new Templeton fund among others, investing reporter Victor Ferreira said Canadian retail investors looking for exposure to hedge-fund like strategies that can involve leverage and short-selling are being inundated with new options, following a rule change in January. At least six firms have brought so-called “liquid alternative” products (some of them ETFs and some of them mutual funds from firms like Mackenzie and C.I. Funds) to market since regulations barring them from doing so were lifted at the beginning of 2019. Prior to the regulations being altered, he said, only a few firms were able to offer such products after applying for exclusions.

As the Post pointed out, some alternative assets — notably real estate and private equity — are seldom easily liquidated if you need some cash. It cited a 2018 Scotiabank report that projects the Canadian market for these kind of products could grow to be worth $20 billion.

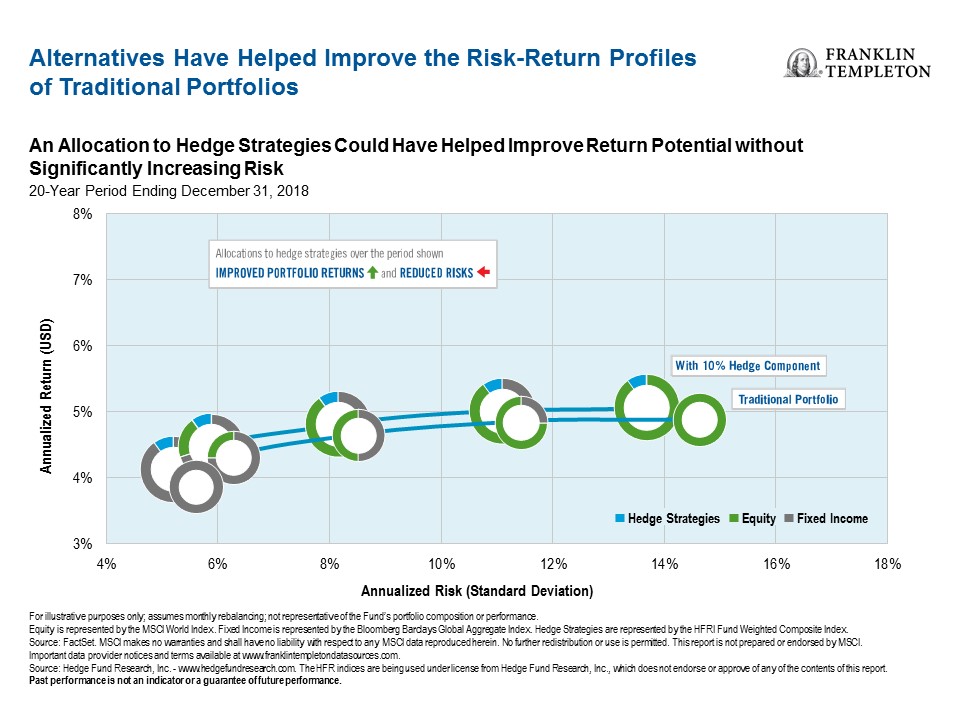
According to Franklin Templeton marketing documents, alternative asset classes or hedging products can improve return potential without significantly increasing risk. It describes three possible “buckets” investors can choose from: traditional Equity Beta or “Risk On,” traditional Bond Beta or “Risk Off” and Alpha Alternatives, or “Risk Uncertain.” It said Alternative Assets can also protect client assets during declining equity markets. In addition, Alternatives have “held up well in weak bond markets.”

Green told the Post that the new Franklin Templeton fund gives investors access to three different strategies: the fund will index 50 hedge funds and aim to replicate their returns. On the long/short side, the fund will also identify the most popular stocks that alternative asset managers are buying and take long positions in them while shorting S&P 500 or futures contracts and any individual names it deems unattractive. Thirdly, the fund will target risk premia.

Or, in the language used in the Franklin Templeton press release: Continue Reading…

Solving the home country bias in Canadian portfolios

Canadian investors tend to suffer from home bias – a preference to hold more domestic stocks over foreign equities. This is actually true of investors in most countries, but it’s particularly troubling in Canada where our stock markets are highly concentrated in the financial and energy sectors.

The federal government could be partially to blame for our home bias tendencies. As recently as 2005 the government imposed a limit on the amount of foreign content allowed in RRSPs and pension plans. This cap was introduced in 1971 to help support the development of Canada’s financial markets but was scrapped in the 2005 federal budget, freeing Canadians up to invest abroad.

Sizes of World Stock Markets

It’s well known that Canada makes up less than 4 per cent of global equity markets (2.7 per cent, to be exact), yet 60 per cent of the equities in Canadian investors’ portfolios are in domestic securities.

Even most model ETF and index fund portfolios have Canadian investors overweighting domestic equities, holding anywhere from 20 to 40 per cent Canadian content.

Canadian home country bias

The result is a portfolio that is more volatile and less efficient than one with international equity diversification. Indeed, investors with a Canadian home bias are taking risks they could have diversified away by increasing their allocation to global equities.

My two-ETF portfolio

So how does my portfolio stack up? When I switched to my two-ETF solution, made up of Vanguard’s VCN (Canadian) and VXC (All World, ex-Canada), I chose to have an allocation 20-25 per cent Canadian stocks and 75-80 per cent international stocks.

That allocation would be relatively easy to monitor and rebalance if it was simply held in my RRSP. Whenever I added new money to my RRSP, I’d simply buy the ETF that was lagging behind its initial target allocation.

But I complicated things recently when I started contributing again to my TFSA. I wanted to treat my TFSA and RRSP as one total portfolio and keep the same asset mix in place. Since my RRSP was much larger than my TFSA, I decided to hold mostly foreign content (VXC) in my RRSP while putting Canadian stocks (VCN) in my TFSA.

This worked out great for several years but now I’ve run into a second problem; I’m contributing to my TFSA at a much faster pace than my RRSP. That’s because I’ve maxed out all of my unused RRSP contribution room and, due to the pension adjustment, I get a measly $3,600 per year in new contribution room.

Meanwhile I still have loads of unused TFSA contribution room and so I’ve been socking away $12,000 per year for the past two-and-a-half years. I hope to continue at that pace for many more years until I’ve completely caught up on all that available contribution room.

The result is a portfolio that is becoming increasingly more tilted to Canadian equities. At this rate, if I continue filling my TFSA with VCN, my portfolio will have more than 30 per cent Canadian content in five years, and nearly 40 per cent Canadian content in 10 years.

My Home Bias Solution

I’m considering a change to my two-fund portfolio. With the introduction of Vanguard’s new all-equity asset allocation ETF – VEQT – I could turn my two-fund solution into a true one-fund solution and make investing even more simple. Continue Reading…