Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

How much can you expect for investment returns?

“How much am I going to make?”

That’s likely the most reasonable question that an investor could ask. When you sign up for a savings account or GIC it’s usually the rate of return that lured you in, or got your attention. We know that many savers are ‘rate chasers’. They go from bank to bank, playing each bank against the other bank, asking for more, asking for a higher interest rate on their savings account or GIC.

I often had clients brag to me that they could get a savings account at 1.5% at so-and-so bank or credit union. I’d reply “That’s great, go for it, but I work in investments, I’m talking about earning triple or quadruple or more than that rate over time.” Of course, I would always qualify that there was the potential to earn that greater rate or return.

Did I mention that 1.5% don’t impress me much?

Of course, at this stage of the conversation I would probe the client’s savings accounts and whether or not they had a more than ample Emergency Fund. Typically, advisors will suggest that you hold 3-6 months of total spending needs in a savings account. That said, everyone knows their own personal situation and what types of emergencies that might pop up – and potentially the costs of those emergencies.

Separate short-term and long-term money

Another important practice is to separate our short-term monies and our long-term monies. Once we’re covered with that short-term emergency bucket, we move on to growth and try to make our long-term monies work real hard. You will also have day–to-day monies in a chequing or savings account.

One of the biggest mistakes Canadians make is to have too much money in “high interest” savings accounts. Guess what? That 1-2% is not going to take you to the retirement promised land. In fact, monies in a savings account are usually going backwards, it’s not making you a dime once you factor in inflation. A long term historical average for inflation is in the area of 3%. If you’re earning 2% in a savings account, you’re losing 1% spending power, each year.

Your $100,000 that you have today might feel like (or spend like) $90,000 or less in ten years. Start to extrapolate that over a few decades and the effect is greatly exaggerated. Inflation is nasty. Here’s an example that will also show my age. When I was a kid, I would take 25 cents to the movies to buy treats. With those 25 pennies I would be able to buy a pop and chips, I think I may have also been able to buy a 3-pack of gum. Yes, I also spent a lot of time in the dentist’s chair. Can you get anything for a quarter these days? I didn’t think so. Talk about losing spending power. And no, I did not grow up in the era of the Great Depression. I ‘grew up’ in the best decades of all time: the 60s and the 70s.

Only stocks can outstrip inflation

Now certainly, the 70s experienced some ‘hyper’ inflation so the effect was exaggerated. But inflation is there and it’s powerful, even in the 2.5 – 3% range. Continue Reading…
How investing makes it easier to achieve Financial Independence

By Gary Bordeaux

Special to the Financial Independence Hub

If you are looking for a way to secure your financial future, learning how to invest your money can help accomplish that goal. There are a variety of investment vehicles that can be tailored to fit your needs, timeline, and risk tolerance.

Let’s take a look at some of the specific reasons how investing helps a person obtain financial independence (aka “Findependence”).

Make money both today and tomorrow

If you are interested in generating a steady income from your investment portfolio, you can buy dividend stocks or a REIT (Real Estate Investment Trust). You make money today by receiving a dividend payment every month or quarter. You make money in the future by holding the security as it appreciates in value. When it reaches what you feel is the height of its value, feel free to sell it and lock in a profit. It is also possible to hold stocks in a trust that can benefit children, grandchildren or other beneficiaries after you pass on.

Obtain returns greater than the Rate of Inflation

Thanks to inflation, a dollar that you hold in your hand today will be worth the equivalent of 98 cents a year from now. This is because the price of goods will increase by an average of 2 per cent per year. In some cases, inflation can reach 4 per cent or greater in a given 12-month period.

As a general rule, stocks will appreciate by about 7 per cent per year, and that amount is higher if a stock offers a dividend. What this means is that you are increasing your net worth above what it takes to keep up with cost-of-living increases. Over a period of years or decades, you could accrue tens or hundreds of thousands of dollars that can be used to enhance your lifestyle.

Improve your chances of owning a home

Let’s say that you are looking to buy your first house. You could decide to buy a single-family unit with a monthly mortgage of $1,000 that you are responsible for paying on your own. However, another option is to buy a duplex that you can both live in and derive income from. At the very least, having a tenant living in the other half of your home will decrease the monthly mortgage payment.

The money that you save can then be used to improve the home or make other investments. If you make improvements to a property that is used for rental purposes, it may be possible to write off the amount of those repairs on a state or federal tax return. Continue Reading…

5 financial fitness tips to help becoming #RetireReady

By Jenny Diplock

Special to the Financial Independence Hub

As any personal trainer will tell you, a new fitness routine starts with a personalized plan and a target goal. And to improve performance, you need to train: especially in the off-season. Taking a similar approach to your retirement contribution goals can help you feel confident you’re #RetireReady.

In fact, according to a recent survey from TD, 79 per cent of working Canadians agree that reviewing their retirement contribution goals outside of RSP season is a good idea.

But even with these good intentions, the data shows just 40 per cent of working Canadians contribute regularly to their registered Retirement Savings Plans (RSPs) through pre-authorized contributions, 20 per cent don’t contribute to retirement savings at all, and nearly a third of working Canadians feel stressed out during the February RSP season.

When it comes to saving for retirement, contributing to your RSP once a year is like running a marathon without the right training. Because you’re not in the habit of saving, trying to come up with one large contribution amount just before the annual RSP deadline can be harder than contributing smaller and more manageable amounts throughout the year, potentially putting additional pressure on the rest of your finances.

To help improve your retirement readiness year-round: Continue Reading…

How to make money online for your business marketing

By Kristen Pearson

(Sponsored Content) 

When you think of something like business marketing, it’s important to consider that it’s not just limited to making people attracted to certain aspects of your business. Given the scope and kinds of business marketing you can pull off, you are actually more than capable of utilizing your business appeal and tap into your potential audience to make means to earn more money for your business outside your products and services. When you read the article below, consider trying to apply these methods to your overall business strategy, and you might find out some new way of creating passive income for your various needs.

It’s important to understand, however, that while there are a lot of ways you can make passive income — in both through your personal endeavors and through marketing itself — you shouldn’t forget to maintain these income streams’ performance. In fact, some of these passive income ideas can actually boost your marketing efforts as well, making it quite the stone that hits the proverbial two birds. This can be very helpful if you’re stuck in a bind and want to use your resources efficiently, as the methods can not just get you potential sales and boost your marketing, but even earn you additional income.

Tips on making money online

With the above in mind, it may be important to consider as early as now that business marketing does hold a lot of potential to attract people to your business. However, did you know you can make passive income out of it? That’s right, try to review the journalreview.org passive income methods below and see if you can actually apply this to your business:

Make your blog suitable for outreach 

Blogger outreach is one of the most relied-upon methods of gaining traction with your audience, though it can be challenging using this to earn passive income as blogging is really more of an investment. When you make a blog, don’t just focus on your rankings and your keywords, but rather to write content relevant enough for your audience across a long period of time. This not only encourages other bloggers to source you, but you can build yourself a reputation of publishing relevant content in your blog. Give it time, and other blogs will want to guest post in your blog – and that’s when you can start charging them on piggybacking on your rankings. And if this is a competitor or someone in a niche, you’re likely going to get samples and other benefits to review as well.

Maximize content releases by making them on sale

Blogging is free: most of the time, anyway. However, if you want to provide more technical and more precise knowledge to your audiences, you always have an option to make them exclusive content. Provide your more relevant information through ebooks and other releases that your fans will want to buy from you, all the while proving to them you provide relevant content through your blog. You’d be surprised how well ebooks and other exclusive content can sale if you get them out there enough.

Encourage fans and audiences to take up an online course

If you know you and the members of your team are experienced enough in your field, you can actually offer a course to help others jumpstart a career in your niche. You can gather your meeting data and your notes in order to create lectures subscribers and loyal customers can avail for a certain fee. This not only puts you in a position to spread learning, but being able to actually teach what you know puts you in a position of relevance. What better way to establish authority than to do things that make you appear like one? Continue Reading…

This is Easy Street for Canadian investors

By Dale Roberts

Special to the Financial Independence Hub

Investing is simple. We are all familiar with the KISS acronym. Simplicity is the key to successful investing. I have been reading and studying investing and investment strategies for decades and came to the conclusion that for the most part “nobody knows nothing.”

Great. All that research and tens of thousands of hours of study and I came back to the fact that I don’t need to know much at all. What a complete waste of time? No not at all. The thousands of hours of study showed me why I, we, don’t need to know much. We do not need to be experts when it comes to investing. As I like to write: It ain’t rocket surgery. Here’s how you find Easy Street.

What is an investment portfolio? In its basic form we can think of a portfolio as having two components: great companies for greater growth potential and bonds to manage the risk. Those bonds work like shock absorbers on the portfolio to reduce the risk or volatility. The more bonds in the portfolio, the lower the risk level of the portfolio.

A typical portfolio will hold great blue-chip companies (stocks) such as Apple, Google, Microsoft, Facebook, Johnson & Johnson, Berkshire Hathaway (Warren Buffett’s company), Coca-Cola and on and on. On the Canadian side we’ll hold Tim Hortons, the big Canadian banks, the telco companies such as Bell, Rogers and Telus, plus railroad companies such as CN and CP Rail and major energy players such as Suncor and Enbridge and on and on.

The rich are business owners

We know that the richest people on earth are usually business owners. We’re going to join them. We’re going to own a piece of those businesses. When enough of those companies do well, you do well. And certainly not every business is going to do well: that’s why you own a bunch of ’em. And that’s why you’ll own great companies in Canada, US and around the globe. And we don’t have to know how to analyze those companies, we can simply go and buy the ‘entire’ stock market. Here’s What is Index Investing and why it’s simply a superior form of investing. It’s so easy we call it Couch Potato Investing.

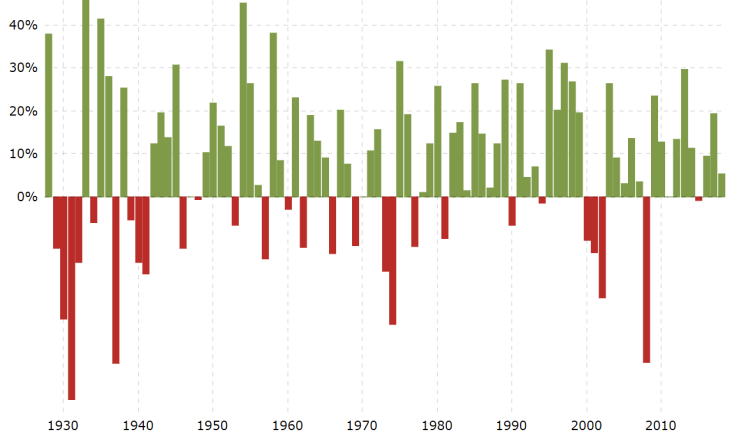
And back to risk or volatility. Certainly stock markets mostly go up over time, but they do correct or go down with regularity; it’s a normal and expected part of investing. For the potential of those 9-10% annual returns from stocks we need to accept some risk. Keep in mind that stocks can go down by 50% in major stock market corrections. That’s not everyone’s cup of tea to watch their investment portfolio get cut in half. That’s why many or most investors will need some bonds in the portfolio. Bonds are fixed-income investments and are typically less risky than stocks. A bond pays you a fixed payment on a regular basis and bonds can also go up in value when stocks go down – think teeter totter.

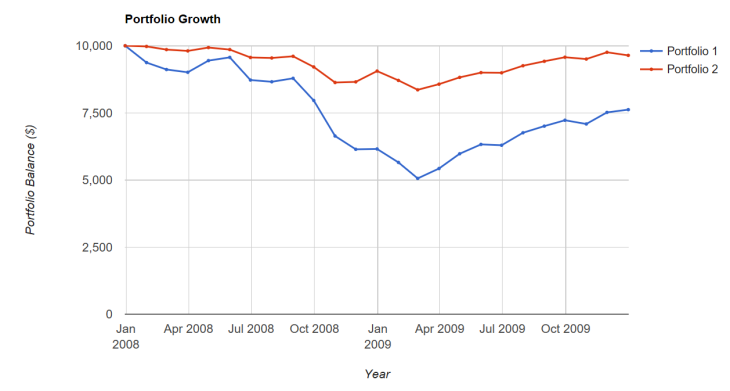
A portfolio with a very generous amount of bonds would have only decreased by about 10%-15% in the last major market correction. For the period of 2008 to end of 2009, here’s a comparison of the US stock market (S&P 500) as Portfolio 1, and a Balanced Portfolio as Portfolio 2.

We see that the all-stock portfolio declined by 50% while the Balanced Portfolio with a 70% bond component declined by just over 15%. By the end of 2009 that conservative Balanced Portfolio is almost back in positive territory while the all-stock portfolio still has more of that hill to climb.

Percentage in Bonds a critical decision

The most important decision that will be made, or the most important question answered will be “What percentage of bonds do you need?” What is your risk tolerance level? What roller coaster do you want to ride? You get to decide. Continue Reading…