Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

The Future is not quite now: A calm perspective on gloomy predictions

Here are a couple of conversations I’ve been involved in recently. Does any of it sound familiar?

Conversation with a retired engineer. He asked, “What do you think about this driver-less cars business? Has anybody even considered how many people this will throw out of work? We have to do something about this! Otherwise, joblessness will go so high that it will cause a depression.”

Conversation with a middle-aged family doctor/real-estate investor. He said, with complete confidence, “I’m cutting back on my medical career and moving into real-estate development. Long before I want to retire, I expect my job to disappear due to competition from AI (artificial intelligence).”

When listening to predictions, especially gloomy ones like these, keep in mind that nobody can consistently predict the future. Also remember that the most widely accepted gloomy predictions are especially prone to fail. That’s because people, as individuals, react to and prepare for predictions of doom. They work on the problem before its predicted arrival time. Sometimes they offset it entirely.

Y2K was the ultimate example

The ultimate example came on the first day of this century, with the non-arrival of the so-called “millennial bug,” or Y2K for short.

In the late 1990s, computer consultants warned that at the stroke of midnight on December 31, 1999, computers around the world would freeze up because of a problem with their data-storage limits. Computers used to use just two digits to designate a year. So they wouldn’t be able to tell what came after 1999; ‘00’ could mean 1900 or 2000. The problem had a simple fix, however. By the last day of 1999, most computer owners had attended to it. Damage from the predicted crisis was negligible.

Today’s predictions — gloomy and hopeful — revolve around the expectation that computer speeds will continue to rise, and computer costs to drop, at much the same rate as they have for the past half century.

This trend has led to exponential growth in the processing power of computer chips, coupled with an exponential drop in their cost. This leads to casual-conversation predictions like the two I mention above: artificial intelligence will soon lead to legions of unemployed taxi, truck and bus drivers; and legions of unemployed family doctors will follow soon after.

The logical flaw here is that exploding computer power at shrinking cost is a technological advance. But there are social, legal and practical limits to how quickly business can translate these technological gains into real-world progress (or problems, depending on how you look at it).

Computer makers don’t need government permission to raise the speed of their chips. In contrast, makers of driverless cars face all sorts of problems, long before they make any money.

The shift to driverless vehicles will happen gradually, over a period of decades. After all, driving in traffic involves far more surprises than a champion Go player faces on the playing board. Drivers have to deal with changing weather, full sunlight and deep shadow, unpredictable human drivers with varying skills, unpredictable pedestrian web surfers, potholes, snow-covered street markings and so on.

The shift from human to AI doctors will occur at an even slower pace — in line with how long it takes to earn a driver’s license on the one hand, and a medical license on the other. AI will replace family doctors some time after it replaces the voice and chat help lines that people use when they have a problem with a computer, a cell phone or a utility bill.

Assume technological process leads to economic progress

People have a long record of guessing wrong about the impact of new technology, and on how long it will take for the new technology to become part of daily life. You’ll guess right much more often if you just assume that technological progress eventually leads to economic progress. Continue Reading…

Retired Money: Should you worry a large TFSA will trigger a CRA audit?

MoneySense/Shutterstock

Should you worry that a large TFSA will trigger a CRA audit? My latest MoneySense Retired Money column looks at a legal debate between the Canada Revenue Agency and taxpayers who have succeeded too well in growing their Tax-free Savings Accounts (TFSAs) with shrewd investing. You can access the full story by clicking on the highlighted headline: Why the CRA is targeting some TFSAs in court. 

If you’ve contributed regularly to the TFSA since it began in January 2009 you now have $57,500 of cumulative contribution room. With decent growth, it’s easily possible to have accumulated $100,000 in a TFSA by now: in fact, the CRA told me for the article that of the 13.5 million TFSA accounts that existed by 2016, 18,000 have balances of at least $100,000 (a number that includes myself and my own Millennial daughter, thanks to a few good FANG stock picks).

A Globe & Mail article last week profiled several ordinary Canadian investors and financial bloggers who have TFSAs of at least $100,000. See How to Grow your TFSA: Tips from Financial Bloggers to Fatten Your Account.

My MoneySense article quotes an unnamed investor who is being audited because his TFSA has grown to $500,000, owing to  timely growth of some private technology companies. He doesn’t think $100,000 is enough to trigger an audit but suggests $250,000 may be. In other words, the CRA may be fine with TFSA doubles but five-baggers will invite scrutiny and ten-baggers most certainly so.

But the real controversy involves TFSAs that are run as de facto securities trading businesses. The Globe highlighted this latest crackdown in an earlier article in July but was merely the latest of a series of TFSA audit scares that have been surfacing virtually since after the first year the program existed.

Shrewd stock-picking is not “aggressive tax planning” 

Some of those earlier audits involved TFSAs that soared because they held private companies but my guess is that, as in my own case or that of my daughter, the vast majority of TFSA holders are neither day traders nor experts in investing in private companies. We only buy exchange-traded funds or blue-chip North American stocks, including the FANG tech giants (Facebook, Amazon, Netflix and Google).

True, depending on when you bought them, it’s quite possible TFSA investors may have experienced 5- or even 10-baggers on stocks like Facebook, Amazon or Netflix. I doubt many investors would make concentrated bets on just one or two of these but if they did, then a $250,000 TFSA would not be inconceivable. That might invite scrutiny from the CRA but I strongly doubt they’d have a case for running a securities business.

Based on the CRA numbers cited in the MoneySense column, Tim Clarke estimates the CRA would have to audit 9,000 TFSAs in order to “recover” the amount of tax specified in the July G&M column that sparked this latest round of TFSA audit worries.

“I love how they say successful traders are conducting ‘aggressive tax planning’ “, Clarke told me in an email, “The purpose of TFSAs was stated in the budget that announced them to be a vehicle to allow taxpayers to save for retirement and other legitimate purposes. How can being successful at that be aggressive tax planning?”


TFSAs remain a critical tax-shelter for retirees

If you’re a retiree or close to it, presumably your TFSA will be invested fairly cautiously, just like an RRSP or RRIF, which means some combination of blue-chip dividend-paying stocks and fixed income. The TFSA is too valuable a tax shelter to get scared by audits of a handful of aggressive investors. Keep in mind that unlike RRSPs, you can still keep adding to your TFSAs well after age 71, to the current tune of $5,500 a year, and perhaps with future inflation adjustments.

There’s no reason that a retiree shouldn’t keep adding to their TFSAs until their late 90s or even beyond: not necessarily with “new” money but from post-tax money liberated from non-registered investments or after tax is paid on forced annual RRIF withdrawals.


The two main types of Financial Independence

By Vicki Peuckert Cook

Special to the Financial Independence Hub

If you are financially savvy and on your way to a secure retirement, you may already know the steps you should take to work toward financial independence. Maybe you’re already there.

But if you are climbing out of debt and just taking control of your money, financial independence (aka “Findependence”) might seem entirely out of reach. If you have kids, focusing on solving your own money problems may be complicated by your concern about their financial future too.

Financial independence means two different things at two different points in life. And they are both significant milestones. You and your adult children may even be working toward them at the same time!

Here are explanations of both kinds of financial independence and actions to consider to make the path to “FI” attainable, no matter where you are starting from.

Becoming Financially Independent from your parents

Adult children who no longer require any monetary support from their parents are financially independent. This doesn’t mean that a parent can’t provide some kind of financial aid if they choose, it means a child can meet their financial obligations without parental help.

With money concerns including five-figure student loans, rising rents, and considerable consumer debt, many young adults face an uphill battle when trying to leave their parents ‘financial’ nest. And parents may also be “sandwiched in” – helping their kids and providing support for aging parents while trying to save for retirement.

For the benefit of everyone involved, parents and adult children have a responsibility to each other to focus on changes and develop a plan to make financial independence a priority.

What can young adults do?

They can learn how to track expenses and make (and stick to) a budget. Making choices like sharing housing with friends and buying used cars or taking public transportation can also help 20-somethings tackle debt.

Over time, increased income from second jobs paired with making frugal choices like cooking at home, can provide the money adult children need to minimize and finally eliminate the need for parents to provide financial support.

What should parents do?

Parents should start setting limits on the assistance they provide their children. And they should work closely with them to create a plan to end all financial support over a set period of time. Parents need to realize they may actually be harming their kids by enabling their kids to make decisions that aren’t always focused on them becoming financially secure.

If a parent always steps in with a solution, their kids may not learn the importance of meeting their needs while putting off wants for the future. And this will only lengthen the time needed to reach financial independence.

Providing advice, emotional support, and helping adult children problem solve money troubles shifts the financial relationship to adults talking, rather than a parent instructing their child on what to do.

Becoming Financially Independent from Work

The other definition of financial independence is one that’s sometimes debated. But there is little argument that it should be a future goal of everyone. In general, reaching financial independence means you have enough income to pay for your living expenses for the rest of your life without having to work. Continue Reading…

Avoiding the “big mistake” — How Evidence-based investing saves long-term wealth

By Steve Lowrie, CFA
Special to the Financial Independence Hub
“Buy low, sell high.”

Sure, it’s a tired cliché, but it’s actually good advice.  Everyone knows it.  Most of us may even manage to do it by simply leaving well enough alone instead of constantly questioning our investments.  This is especially so if you’ve preceded your inactivity by setting up a solid plan and investing accordingly.

But here’s the challenge: Even the most stay-put investor is still at risk for making that rare “big mistake.”  It happens when seemingly game-changing news tricks you into falling for a different financial platitude: This time is different.

Even if you only deviate from your routine in the face of an extreme event, the financial damage done can last a lifetime.  One of the biggest, most recent anomalies was the Financial Crisis of 2008/2009.  At the time, many investors (and many advisors as well) wondered whether the markets would ever recover.

Although we are almost 10 years removed from this time, it was a highly emotional period for investors.  In fact, one of my favourite financial commentators — Nick Murray — refers to this period as The Great Panic. To put this into context, let me share a few real-life investor anecdotes.

Take “Joe,” for example, who reached out to me to inquire about my services in October 2008.  At the time, Joe had a $2.6 million portfolio.  He had a very stable and successful business and wasn’t planning to tap into his investments for a couple of decades.  His portfolio wasn’t perfect.  Some of his holdings had high expense ratios, and some of them could have been better managed.  But overall, they seemed relatively well diversified and well structured.  He was doing okay.

Still, Joe was thinking about abandoning his balanced approach and moving to cash.  I offered Joe this timeless advice:  When we’re in the thick of a bear market, nobody knows when or how it might reverse course.  But we do know it is highly likely it eventually will: often quickly and without warning.  If you try to time when to be in and out of the market for optimal effect, you must not only correctly guess when to get out, you’ve also got to predict exactly when to get back in.

Cashing out in 2008

So, November 2008 came and, along with it, a second major market drop. This was too much for Joe.  In late November, he called me and told me something like this:  “Thanks for your time.  However, this time really is different, and your history and evidence doesn’t matter.  I have sold my entire portfolio and moved all my investments into cash.”

I don’t know what happened to Joe after that, because we went our separate ways.  In the short run, he was right.  We didn’t know it then, but the third (and final) major drop in the equity markets arrived in January/February 2009.  Using historical index data and assuming a balanced portfolio of 60% Global Equities and 40% Global Bonds, liquidating his portfolio ahead of this final drop “saved” him from a loss in the range of $200,000.

Once again, using index data, had he simply held his portfolio he would have made back the “$200,000 loss” by May/June 2009 and then been almost 20% higher by November 2009.  In dollar terms, that is over $500,000 higher than he was in November 2008.

I doubt Joe had the nerve to reinvest anytime in 2009 …  it’s far more likely he waited until the recovery was in full swing, buying higher than necessary and sacrificing returns that could have been his by simply holding tight.  Or, for all I know, he’s still sitting in cash today.  If so, he has so far given up about $3 million in potential wealth … even after assuming reasonable fees for investment management, financial planning, and (most importantly in Joe’s case) behaviourial coaching. Continue Reading…

New mandatory risk rating is misleading Canadian investors

By Nick Barisheff (Sponsor Content)

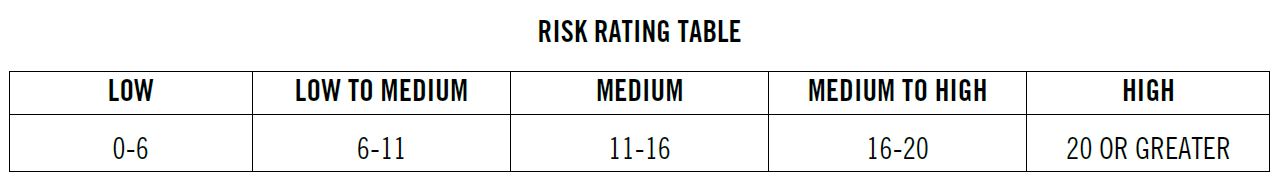
Canadian securities regulators may be putting investors at risk. They implemented a new mandatory risk weighting system in September 2017 based on 10-year Standard Deviation. Every Canadian mutual fund and exchange-traded fund (ETF) must now include a risk rating based on the following:

Before implementing this policy, the Ontario Securities Commission (OSC) asked for submissions from the industry. These can be viewed here.

Over 50 submissions were received (mine included.) and out of those, three warned about the deficiency that Standard Deviation does not differentiate between upside and downside volatility.

Scott C. Mackenzie of Morningstar made a particularly succinct comment:

“A conservative investor’s portfolio that is missing a key sector or asset class, essential for prudent diversification (and risk reduction), may demand the inclusion of a small amount of a concentrated sector mutual fund or ETF. A single measure risk score for such a vehicle may be higher than recommended for the investor and they are consequently dissuaded from incorporating it. The irony and potential downside is that the risk of the conservative portfolio may actually be higher than otherwise would have been had the investor included the diversifying investment. “Diversification as a risk-reduction activity is a sensible approach, practiced by many, and supported by decades of investment research.” http://www.osc.gov.on.ca/documents/en/Securities-Category8-

Comments/com_20140312_81-324_mackenzies.pdf

There are two major flaws with the methodology:

  1. It does not differentiate between Standard Deviation and Downside Deviation; and
  2. It measures individual portfolio components rather than the overall Standard Deviation of the entire portfolio.

This policy will not protect investors from experiencing losses, but may prevent investors from structuring portfolios for reduced volatility, optimal performance and effective diversification. The resulting reduction in investment demand in sector funds will result in a negative impact for many Canadian public companies.

The overall weakness of this approach is best exemplified by the fact that Bernie Madoff’s fund had the lowest Standard Deviation in the industry for over 30 years – yet investors lost most of their money.

David Ranson of H.C. Wainwright & Co. published a report entitled “Why Standard Deviation Won’t Serve to Classify the Risk of a Portfolio.” This report details why Standard Deviation is a poor and overly simplistic approach to measuring the risk of a portfolio.

“The riskiness of an investment product cannot be represented by the Standard Deviation (volatility) of its historical returns, or by any other single statistic … On a real risk scale, cash could be assessed as risky and gold as safe.” 

http://bmg-group.com/wp-content/uploads/2017/12/why-standard-

deviation-wont-serve-to-classify-the-risk-of-a-portfolio.pdf

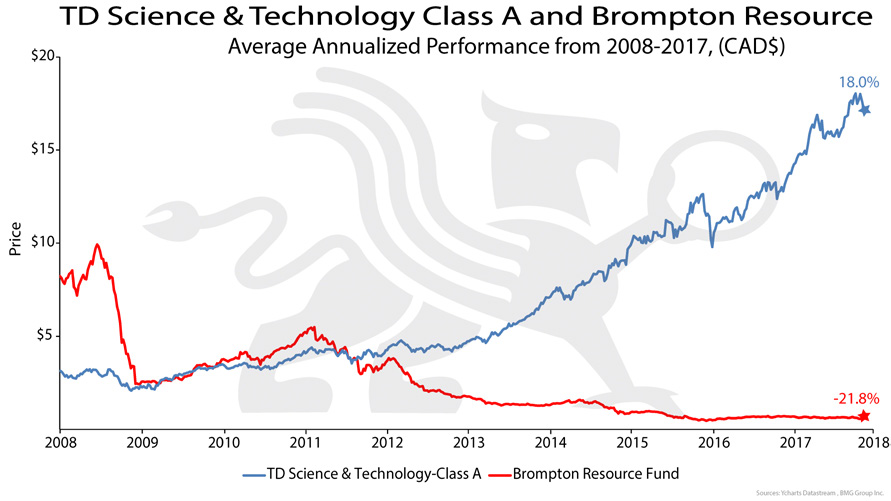
As an example of how flawed this policy is, Morningstar Canada lists 9,412 equity classes of mutual funds. Of these,1,932* have 10-year performance histories. The best-performing fund is the TD Science and Technology Fund, which achieved an 18.00% 10-year annualized return net of MER. A $10,000 investment in 2007 would now be worth $66,554*.

On the other side of the performance scale is the Brompton Resource Fund. It ranks as 1,932*(last) in performance and has experienced a-21.8% annual decline over the same 10-year period. A $10,000 investment ten years ago would now be worth only $643*.

*As of July 18, 2018

The 10-year (2008-2017) Standard Deviation for the TD Science and Technology Fund is 17.7% (MEDIUM to HIGH RISK) and for the Brompton Resources Fund it is 29.57% (HIGH RISK). However, the Downside Deviation is 10.6% (LOW to MEDIUM RISK) for the TD Fund and 25.7% (HIGH RISK) for Brompton Fund.

It should be obvious, even to the unsophisticated investor, that the risk of these funds that are at opposite ends of the performance spectrum is not similar.

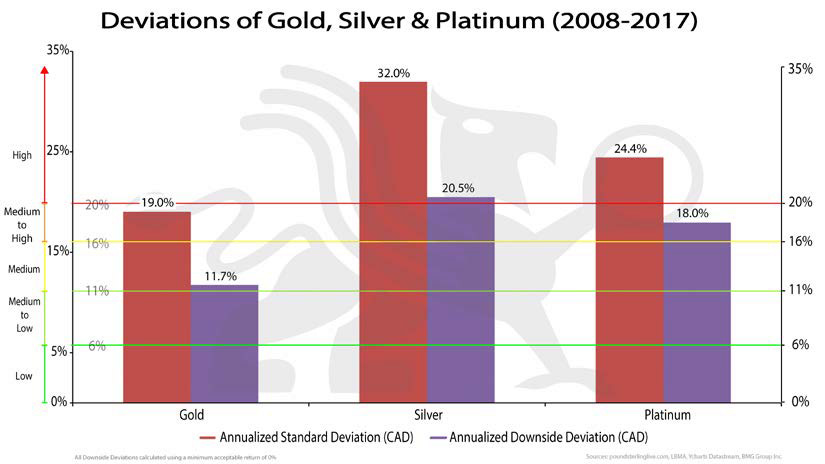
This flawed methodology is more pronounced when it comes to physical bullion funds such as the BMG Funds. According to this methodology, the Standard Deviation for gold results in a MEDIUM to HIGH risk rating. Silver and platinum would be rated HIGH RISK.

This new risk rating methodology is in direct contradiction to the suggested risk rating for gold established by the Basel Committee on Banking Supervision (BCBS). BCBS brings together regulators from 28 countries, and establishes rules governing the appropriate level of capital for banks. The current version of these rules, known as Basel III, is a key element of the international regulatory reform agenda put in motion following the global financial crisis of 2008. During the 2008 financial crisis, gold was used in international settlements as a zero-risk asset after many decades of being sidelined in the monetary system. Gold’s old emergency usefulness resurfaced, albeit behind closed doors, at the Bank of International Settlements (BIS) in Basel,Switzerland. Continue Reading…