Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Italian Economics: Watch Salvini

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

In April, the Italian public was so incensed by the country’s broken government budget, endemic graft and unaffordable inward migration that half of the general election vote went to two protest parties. On the left, the Five Star Movement topped all, with 32% support, while the right-wing League party took 18%. Since then, the League has gathered even more support. Its leader, Matteo Salvini, may now be the most powerful person in Italy.

Salvini’s answer to the European Question

With a wave of migration from North Africa and the Middle East in recent years, Italy finds itself dealing with culture clashes and a scramble to find the money to house and feed the new arrivals.

But amid all the talk of the migrant crisis, what has gone largely unnoticed is that both Five Star and the League have some economic policies that are irrational at best, dangerous at worst. With the news cycle focused on cultural issues, we are wise to remember that Salvini, currently positioned as the champion of nativist Italy, has communist roots. His economic belief system has shifted with age, but this is no solace to EUR longs.

Key planks

The coalition government’s common ground includes overturning the Fornero Law, which increased retirement ages, and putting a universal basic income of €780 (C$1,193) per month on the table. However, the coalition does interestingly entertain the idea of a flat tax. All of these together would conspire to blow out Italy’s 2.3% budget deficit-to-GDP ratio.

Positive backdrop

Italy’s 1.4% GDP growth may be anemic, but it is above water, and high by Italian standards; the norm this century is +0.4%. The manufacturing purchasing managers’ index, at 52.7, has essentially been in nonstop expansion since the first quarter of 2015.1 Unemployment is down to a still-troubling 11.1%, but it was nearly 13% in 2014. Investors must ask: what odd fiscal and/or monetary policies will voters demand if conditions become recessionary?

Start with one such policy, which Brussels fears, that is haunting the bond market and EUR.

The specter of a parallel currency

A “New Lira,” side-by-side with the euro. The state will not come out and say it at the moment, but that’s what the proposal for “mini-BOTs” will mean. If Five Star and the League do go down this path, mini-BOTs would be short maturity debt instruments that can be used to state obligations. On the other side of the ledger, owners of the mini-BOTs could use them to pay taxes. This risk has been haunting the bond market and EUR since the idea entered the conversation in mid-May.

For this privilege 

Figure 1 highlights in green the few bonds that yield more than two-year Canadian sovereigns. Australia and the U.S. generally yield more across the board, but investors have to reach for seven-year bonds in Italy to exceed Ottawa’s 2020 maturities.

Figure 1: Sovereign Yields (Highlighted Green if > Canadian Two-Year Government Bond)

Figure 1_Sovereign Yields

December looms

The stated aim of the European Central Bank (ECB) is to “keep prices stable, thereby supporting economic growth and job creation.” But in the last decade, what mattered is its implicit mandate: keep Europe together. The combination of fuzzier European economic data and the potential for Italian mini-BOTs could cause a “dovish” surprise by the ECB’s Mario Draghi, who is set to end the central bank’s €30bn bond purchase program in December.  Perhaps the surprise is an extension of the bloc’s zero interest rate policy for another year or so. That could harm EUR bulls.

European banks not yet indicating Contagion

One way in which European systemic risks can be priced is via bank credit default swaps (CDS). Figure 2 shows current CDS levels along with the peak fear points of the last five years. Continue Reading…
It isn’t what it used to be: Prospects for interest rates and inflation

When I talk to serious, successful investors, few ask, “Do you think the central banks will raise rates two or three times by a quarter-point before the end of the year?” or “Do you think inflation will hit 3% in the next year?” They are more likely to ask things like, “What are the chances that interest rates and/or inflation will get back up to the peaks of the 1970s/1980s?”

That is a much more important question.  A quarter-point change in interest rates or inflation is a fluctuation. A return to the peaks of the 1970s/1980s would be a disaster.

No one can predict the future, of course. The easy way out on the question would be to say, “Oh no, that could never happen again.” But the productive way to address a question like this is to look at those earlier decades and to try to figure out what was special about them.

It seems to me that in the years prior to those decades, three specific political/economic factors worked together to unlock a lot of pent-up demand for money, goods and services, and funnel it into a narrow timeframe where it could have great impact. These factors helped spur the rise in interest rates and inflation that followed.

The first factor was that, during four decades between the early 1930s and the early 1970s, the U.S. managed to fix the price of gold at around $35 U.S. per oz.

Greenback became a world currency in three crucial periods

This helped set up the U.S. dollar as something of a world currency during three crucial, historic periods: the 1930s depression, World War II and the post-war boom. The role of world-currency issuer let the U.S. expand its money supply without burdening itself with a heavy load of domestic inflation — not burdening itself right away, that is. But eventually the $35 gold peg gave way, like a dam that bursts when the force of a rising river becomes too much. The breaching of that $35 barrier helped set off a worldwide wave of inflation, as the value of the U.S. dollar withered in relation to the value of gold. Continue Reading…

Sh*it my advisor says

Some investors eventually leave their commission-based advisors and opt to set up a simple portfolio of index funds or ETFs on their own. There are plenty of compelling reasons to do so; the reduction in fees alone can save investors thousands of dollars a year, and academic research shows that the lower your costs, the greater your share of an investment’s return.

Related: Steak Knives, Yes. Financial Advice, Maybe Not

In my fee-only planning service, many clients end up doing exactly that. I always enjoy hearing the rebuttals from bank and investment firm advisors whenever they hear their clients want to move to a lower-cost portfolio. Here I’ve tried to capture some of that conversation with sh*t my advisor says:

Sexism: When my husband told him we’re choosing simple index investing and that I handle the family finances he smirked and said to my husband, “What credentials does your wife have to manage money?”

The real enemy: Our investment company is being vilified when the true villains are credit card companies with their interest rates.

Proof of concept: I have tons of clients with assets over $500,000 so I must be doing something right.

Working for free: My advisor told me she basically worked for me for free for the past eight years and accused me of dumping her just as my assets were growing.

It takes a professional: People think they can trade mutual funds or ETFs on their own but it’s not as easy as you think. Plus, you don’t have anyone like me to call up and ask if you’re doing the right thing. Re-balancing a portfolio is easy if you have the background, but doing it like you’re thinking about (indexing) is very tough without the training and knowledge.

What’s in a fee?: The fees are at 2 per cent (Ed. Note: actually, 2.76 per cent) because this isn’t just about buying and selling. We created a complete portfolio with you for your tolerance in the market and deal in actively traded mutual funds that most of the time outperform the market.

Nortel: ETFs aren’t all that great. When you buy an ETF you buy the whole fund. In the late 90s when Nortel owned 30 per cent of the TSX it crashed. If you purchased that ETF you’d be down 30 per cent too! But with a mutual fund you can’t buy that much. You are only able to purchase up to 10 per cent of any one company. So you would have been fairly safe with the crash of Nortel.

Downside protection: If the market goes down 20 per cent your ETFs will too. You are much more protected with mutual funds.

Apples-to-apples: All of our fees are wrapped up together in our MER. We do not charge account fees, transaction fees, advisory fees, admin fees or fees for our service. It is just the MER.

Clairvoyance: The bond market has likely reached its peak and appears to moving in a different direction. The equity markets are very risky at this time. In my mind the only safe place left is guaranteed deposits. Continue Reading…

The Paper Boy and the Theory of Nuclear War: Valuable Investment Lessons

Looking back over the past few decades, I’d say that some of my most useful and profitable investment principles came from things I’ve read or experienced that had nothing to do with the stock market.

I’ve already written about my first experience as a substitute newspaper delivery boy, filling in at age 11 for the 13-year-old who delivered the papers on our street. He made it sound simple: “You pick up the papers from the route boss on the corner, and you deliver them to the houses on this list. You go around to the houses and collect the money at the end of the week. The next day, you pay the route boss for the papers you took, and you get to keep all the money that’s left over.”

Every word in that explanation is true. However, he left out one crucial bit of info: rather than pay cash to the paperboy, a third or more of the customers mailed in a check every month to the newspaper office. After the check cleared, the office mailed a check to the (regular) paperboy. This was my first experience with paid work (other than leaf raking, lawn mowing or snow-shoveling, for which I got paid at the end of the day). It provided an instant, valuable lesson: before agreeing to any sort of business deal, you need to know all the details, even if this forces you to ask awkward questions.

Focus on plain-vanilla stocks and bonds

Over the years, this lesson has kept me out of all sorts of money-losing investments and unfair or poorly designed business proposals. It also explains how I came around to the view that you should focus on “plain vanilla” stocks and bonds in your portfolio, and avoid complex investment products, especially those with an insurance component.

Investment products profess to offer a “deal” that has more profit potential and/or less risk than you get from plain vanilla stocks and bonds. In my experience, what you lose on the one side of the promise is less valuable than what you gain (if anything) on the other. The deal in investment products is, however, much more complicated than the deal on the plain vanilla alternative.

It’s easy to find references to the hypothetical gains and advantages of investment products: just look in the marketing brochure, or ask the salesperson. To find out the downside of the product, you have to dig through many pages of legalese/fine print. The seller always has an information advantage over the buyer.

As a group, these products are likely to provide a lower long-term return than what you’d expect from a portfolio of high-quality stocks. But they provide a higher return to the salespeople, compared to what they can earn by selling you a portfolio of high-quality stocks. So, over a few decades, my first newspaper delivery experience at age 11 led me to advise against buying the many types of investment products that expose investors to costly conflicts of interest.

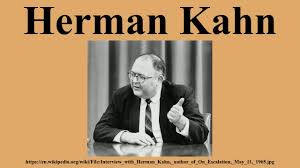
I learned a higher-level lesson about investing from the work of military-strategist/futurist Herman Kahn, author of On Thermonuclear War, Thinking About the Unthinkable and On Escalation. I first heard about Kahn in the early 1960s, when I had just entered high school. This was the height of the Cold War. Like many people back then, I worried that a nuclear war could conceivably break out at any time, with little or no warning. Scientists warned that if war came, “the living would envy the dead.” I tried not to think about it.

YouTube.com

In his book, Kahn said that thermonuclear war would not start overnight. Based on his study of military history, he said the world was more likely to go through 44 stages between the Cold War and World War III. He likened the 44 stages to rungs on a ladder, and divided them into seven subsets.

He labelled the first subset — rungs one through three — as “Subcrisis Maneuvering”; the second group, rungs four through nine, as “Traditional Crises”; the third, 10 through 20, as “Intense Crises”; the fourth, 21 through 25, as “Bizarre Crises”; the fifth, 26 through 31, as “Exemplary Central Attacks”; the sixth, 32 through 38, “Military Central Wars.”

Kahn refers to the passage from subset 6 to subset 7 — that is, from rung 38 to rung 39 — as “The City Targeting threshold.” He labels the final subset, number seven — rungs 39 through 44 — as “Civilian Central Wars.”

In Kahn’s ladder, the first use of nuclear weapons occurs at rung 23 (Local Nuclear War, Military). Civilians only start to become targets at rung 29 (Exemplary Attacks on Population). Civilians become a focus at rung 42, (Civilian Devastation Attack). Rung 43 is “Some Other Kinds of Controlled General War.” Rung 44 is World War III, but Kahn called it “Spasm or Insensate War.”

I found all this greatly reassuring. It gave me reason to believe that if war was coming, it would follow some sort of pattern, rather than come as a total surprise, like a global car crash. Of course, I was still in my teens. Adults differed widely in their attitude toward Kahn and his views.

Some people felt Kahn’s nonchalant writing about thermonuclear war marked him as a heartless monster. (On Thermonuclear War popularized the term “megadeath” — the death of one million individuals.) But Kahn was a jovial, gregarious individual, and this came through in his writing. If he had written in a morose, emotional tone, nobody would have read the book, and that would have been a tragic waste.

Others saw Kahn as an object of ridicule. They loved Stanley Kubrick’s political-satire/black-comedy film, Dr. Strangelove or: How I Learned to Stop Worrying and Love the Bomb. The film’s title character, Dr. Strangelove (played by Peter Sellers), is widely viewed as a parody of Kahn and his unflinching descriptions of the effects of war. It’s less widely known that Kahn collaborated with Kubrick on the script. Some of the film’s funniest lines make use of Kahnian terms, such as “Doomsday Machine.” Others are comical paraphrases of sentences in Kahn’s books. The project appealed to Kahn’s sense of humour.

Spotting unwise or unnecessary risks

Kahn’s work was widely read by high-ranking members of the U.S. and U.S.S.R. government and military. By describing and dissecting Kahn’s 44 stages, politicians and generals on both sides got better at spotting and avoiding unwise or unnecessary risks. In fact, many people give Kahn and his fellow “megadeath intellectuals” some credit for heading off World War III. Instead of world wars, major world powers shifted to regional proxy wars, like the Vietnam war, and the Soviet-Afghan war of the 1980s. Continue Reading…

The Do’s and Don’ts of Trading ETFs

By Bryan Moore, WisdomTree Canada
Special to the Financial Independence Hub
Exchange-traded funds (ETFs) have seen immense growth over the past decade. There are a multitude of benefits, including transparency, tax efficiency and the ability to make intraday trades, that have contributed to the use and growth of ETFs. While these are all beneficial to investors, we continue to see questions around ETF trading. Although ETFs trade on-exchange like stocks, investors have to understand that ETFs trade differently and that ETF execution is an imperative part of investing that should not be minimized.

Many investors know that when evaluating an ETF, average daily volume (ADV) does not indicate the true liquidity of an ETF. The liquidity of an ETF resides in its underlying securities, but how does one access that to ensure smooth execution?

Let’s discuss the do’s and the don’ts of how to best trade an ETF.

The Don’ts

1.)Don’t trade in the first or last 15 minutes of the trading day. This is when trade desks have less transparency and markets are more volatile.

2.)  Don’t place market orders; if you want to trade electronically, place limit orders. We advise investors to always use limit orders, especially in times of volatility. We also advise investors to not use stop-loss orders that turn into market orders.

The Do’s

1.) Do utilize your resources. Consult your trading desk as well as the relevant capital markets desk. The majority of issuers have capital markets teams that can consult on a trade. Additionally, the majority of advisors have access to a trading desk. These desks have access to expert market makers who can access the underlying liquidity.

2.) Do use a limit order when trading electronically, this cannot be said enough!

Most advisors have a trading desk through their firm or custodian, and they are always a resource as well. If there is one thing to take away from this piece, it’s to use your resources and make that phone call or email—it can be the difference between seamless execution and a very costly mistake.

Bryan Moore is Head of National Accounts and Capital Markets for WisdomTree Canada. 

Commissions, management fees and expenses all may be associated with investing in WisdomTree ETFs. Please read the relevant prospectus before investing. WisdomTree ETFs are not guaranteed, their values change frequently and past performance may not be repeated. 

Past performance is not indicative of future results. This material contains the opinions of the author, which are subject to change, and should not to be considered or interpreted as a recommendation to participate in any particular trading strategy, or deemed to be an offer or sale of any investment product and it should not be relied on as such. There is no guarantee that any strategies discussed will work under all market conditions. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This material should not be relied upon as research or investment advice regarding any security in particular. The user of this information assumes the entire risk of any use made of the information provided herein. Neither WisdomTree nor its affiliates provide tax or legal advice. Investors seeking tax or legal advice should consult their tax or legal advisor. Unless expressly stated otherwise the opinions, interpretations or findings expressed herein do not necessarily represent the views of WisdomTree or any of its affiliates.

“WisdomTree” is a marketing name used by WisdomTree Investments, Inc. and its affiliates globally. WisdomTree Asset Management Canada, Inc., a wholly-owned subsidiary of WisdomTree Investments, Inc., is the manager and trustee of the WisdomTree ETFs listed for trading on the Toronto Stock Exchange.