Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Gamechanger? Vanguard Canada launches 3 new Asset Allocation ETFs (plus my take)

Vanguard Investments Canada Inc. has announced the listing of three new low-cost Asset Allocation ETFs that give investors one-stop shopping to the firm’s globally diversified strategies. They began trading on the TSX today (February 1, 2018.)

Both investors and advisors are asking for “simple yet sophisticated single-ticket investment solutions that provide well-diversified global equity and bond exposure within a low-cost ETF structure,” says Atul Tiwari, managing director for Vanguard Canada. The new ETFs offer investors three different risk profiles and regular rebalancing.

In effect, each ETF is a fund of funds although Vanguard describes them as having an “ETF of ETFs structure.” Each holds seven existing core Vanguard index ETFs (which I list in the postscript below). Each new ETF of ETFs has a management Fee of 0.22%. Vanguard says that when one of its ETFs invests in underlying Vanguard funds, “there shall be no duplication of management fees.” Spokesman  Matthew Gierasimczuk said “There are no duplicate fees beyond the 0.22 management fee, other than a basis point or two for operating expense and the trading fee for buying or selling the ETF.”

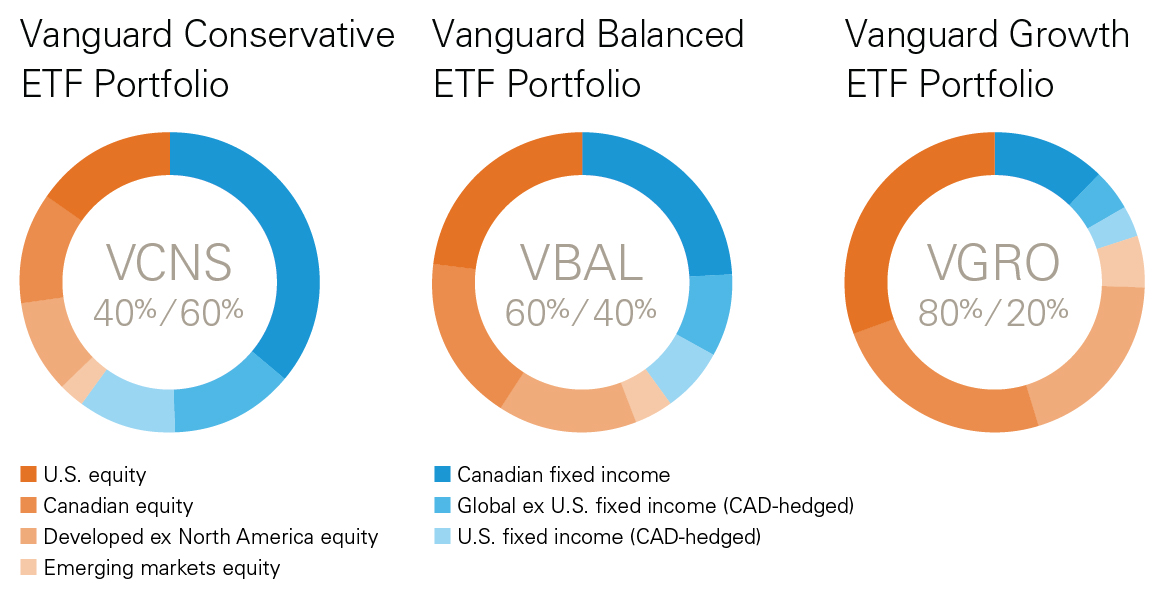
The three asset allocation ETFs cover the normal range from Conservative to Balanced to Growth, as reflected in the product names. Equity weights range from 40% for the Conservative offering, to 60% for the Balanced and 80% for the Growth.

Here are the 3 ETFs and their ticker symbols on the TSX:

Vanguard Conservative ETF Portfolio (VCNS) seeks to provide a combination of income and moderate long-term capital growth by investing in equity and fixed income securities with a strategic allocation of 40% equities and 60% fixed income.

Vanguard Balanced ETF Portfolio (VBAL) will provide long-term capital growth with a moderate level of income split 60% equities to 40% fixed income.

Vanguard Growth ETF Portfolio (VGRO) provides long-term capital growth by investing in equity and fixed income securities with 80% equities and 20% fixed income.

In a press release, Vanguard Canada head of product Tim Huver said the ETFs offer “a simplified and scalable solution for financial advisors, and a one-stop globally-diversified and transparent option for investors … Investors can rely on Vanguard’s global investment experts to continuously assess their portfolio’s exposure and rebalance it back to its intended risk level.” 

With the three new ETFs, Vanguard Canada now offers 36 ETFs, with C$14 billion in assets under management. Vanguard Investments Canada Inc. is a wholly owned indirect subsidiary of The Vanguard Group, Inc.

You can find more at Vanguard Canada’s website.

Postscript: My Take

After sleeping on this announcement, it strikes me as more significant than I had initially perceived. Continue Reading…
Franklin Templeton extends Canadian ETF family with Emerging Markets, Global Dividends

As my latest Financial Post blog this morning explains, mutual fund giant Franklin Templeton Investments Canada has expanded its ETF lineup with a pair of new “Smart Beta” ETFs and an actively managed balanced ETF. Click on the highlighted text for full story: Franklin Templeton boosts Canadian ETF offerings with Emerging Markets play.

As I note in the piece, Franklin Templeton has long had an Emerging Markets mutual fund, famously managed until last year by globetrotting fund manager Mark Mobius, who retires on January 31st after a 30-year career with the company. Franklin Templeton once had a closed end version of the fund but it was closed down in September of 2001, a company spokesman said.

The new Franklin LibertyQT Emerging Markets Index ETF (CAD) bears the memorable ticker symbol FLEM on the TSX, allowing Franklin Templeton to play catch-up to long-established Emerging Markets ETFs from rivals BlackRock Canada (iShares) and Vanguard Canada. You can find more about the new ETF family here.

FLEM is a four-factor “Smart Beta” ETF: the single biggest “factor” at 50% is a quality screen, along with 30% value, 10% momentum and 10% low volatility. Its largest single geographic weighting is South Korea at 15.4%, followed by 13.9% in China, 13% in India, 12.8% in Taiwan and 10.8% in Russia, according to Franklin Templeton vice president of ETF business development Amed Farooq.

The expected Management Expense Ratio (MER) for FLEM is 0.55%. The two other ETFs are The Franklin LibertyQT Global Dividend index ETF (FLGD/TSX, MER 0.45%) and an actively managed balanced ETF, Franklin Liberty Core Balanced ETF (FLBA/TSX), with an MER of 0.45%.

Time to “rebalance” from US equities to Emerging Markets?

Both the two new smart-beta ETFs provide a rebalancing opportunity for investors who feel US stocks have run up sufficiently to start taking profits. Earlier this month, famed investor Jeremy Grantham warned of one last market “meltup” for US stocks before another correction, and said his firm was rebalancing into Emerging Markets. You can find the full January 3rd article here: Bracing yourself for a possible near-term melt-up.

You can also find his comments made in a recent interview with Consuelo Mack’s WealthTrack show here.

I asked about this at the ceremonial opening of the TSX Monday morning, which focused on the ETF launches. Financial advisor John De Goey said he was doing just such a rebalancing for his clients and in an interview, Franklin Templeton senior vice president Dennis Tew said he knew of at least one advisor with a large book of business who likewise has been rebalancing from US income funds to Emerging Markets equities.

Balanced ETF managed by Franklin Bissett

Continue Reading…

Retired Money: Finally, a “Tontine” proposal for true Longevity Insurance

Even if they’ve saved a million dollars, retiring baby boomers lacking Defined Benefit plans and their inherent longevity insurance justly fear outliving their money. It’s been said some fear this more than death itself.

The latest instalment of my MoneySense Retired Money column looks at an intriguing proposal made this week by the CD Howe Institute. Click on this highlighted text for the full link: An annuity that pays off — if you live long enough.

CD Howe has proposed the creation of a “pooled risk insurance” scheme called LIFE, which has all the hallmarks of a 17th century concept known as the tontine.

Moshe Milevsky has long suggested tontines as one remedy for outliving our money

Annuity expert Moshe Milevsky — also a finance professor at the Schulich School of Business and author of books like Pensionize Your Nest Egg — says LIFE is a “great idea.” He actually made the case for the resurrection of “tontine thinking” three years ago in a book I reviewed at the time also at MoneySense: Tontine: Retirement Plan of the Future? 

The CD Howe paper (Headed for the Poor House) authored by Bonnie-Jeanne MacDonald doesn’t actually come out and call LIFE a tontine scheme but it certainly appears to contain the DNA of one.

LIFE stands for Living Income for the Elderly. The idea is that by sharing mortality risk, those who make it to age 85 start to receive monthly payouts for as long as they live, funded in part by the less fortunate members who die between 65 and 84. Apart from normal investment returns, the lucky survivors would enjoy the “added return” of the mortality premium.

Continue Reading…

Here are a million reasons to ignore 5 popular RRSP myths

A lot of Canadians seem to be harbouring misconceptions about the value of RRSPs (Registered Retirement Savings Plans) but I can give you a million reasons why it’s dangerous to believe the  five popular RRSP myths.  My latest two blogs in the Financial Post this week explain why.

In Thursday’s Post, also published in some regional dailies, I described how young people can easily save a million dollars as long as they start early enough. Click on the highlighted text for the online link: How to build a million-dollar RRSP: it isn’t as hard to get there as you think.

Yes, it’s the old story of disciplined saving year in and year out, and the magic of compounding, all aided by the lure of an upfront tax refund and a multi-decade deferment of taxes. Of course, eventually it will be time to draw an income and pay some tax on the RRIF but that’s a story for another day.

Whether a million is enough is open to debate but with today’s paltry interest rates and rising expectations for long lives, the need for annuities or some form of longevity insurance has become urgent. More on that shortly.

Exploding 5 RRSP myths

This morning, Friday,  the FP also ran a blog by me commenting on tax guru Jamie Golombek’s debunking of five common myths average investors harbour about RRSPs. You can find Golombek’s column here: The 5 biggest RRSP myths Canadians can’t stop repeating.

My take on it and a CIBC poll that accompanied the report, can be found here: Almost 40% of Canadians see ‘no point’ in investing in RRSPs — Here’s why they’re wrong.

In short, Golombek and I agree that the RRSP makes a lot more sense than investing only in taxable (non-registered or “open”) accounts. And while the TFSA is a compelling alternative to RRSPs for young people in low tax brackets, or for low-income seniors counting on living on Old Age Security, for the vast majority of middle- and upper-middle-income private sector workers lacking a Defined Benefit plan, the RRSP remains an essential tool for building wealth.

And as I also point out, if you’re in a high tax bracket, you don’t have to choose between an RRSP and a TFSA: you should maximize both!

Sizing up the Size Factor


Small-Cap Growth & Small-Cap Value begin to diverge in 2015

By Chris Ganatti, Wisdomtree Investments

Special to the Financial Independence Hub

It seems like everywhere across the investment landscape in these days there is talk about “factors.” While this isn’t necessarily a new discussion (research has been done for decades regarding the drivers of excess returns within equities), it is easier than ever to pick and choose the factors to which you would prefer exposure.

Size: popular but volatile

When people get excited about changes — changes in policy, changes in growth expectations, changes in political leadership — we’ve tended to see this excitement show up in the behavior of small-cap stocks. We saw this most recently during the “Trump trade,” with the bulk of the performance response coming between the November 8, 2016, election victory and the January 20, 2017, inauguration.

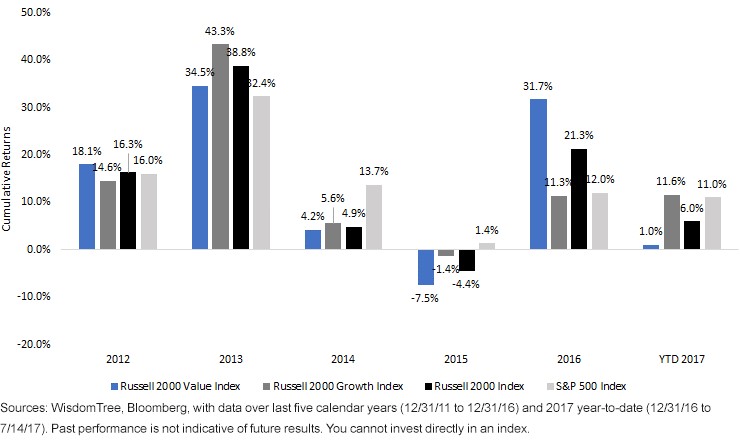
  • In 2012 and 2014, the Russell 2000 Value Index and the Russell 2000 Growth Index performed very similarly. Even the approximate 9% difference between these indexes in 2013 wasn’t particularly noteworthy because U.S. equity market indexes across the board tended to be up 30% to 40% that year.
  • The most recent “tough” year for small caps was 2015, and it was clear that the Russell 2000 Value Index was the laggard, as the Russell 2000 Growth Index was nearly flat. But 2016 saw greater than 20% outperformance of the Russell 2000 Value Index vs. the Russell 2000 Growth Index. In 2017 through July 14, these indexes have reversed again, with the Russell 2000 Growth Index now outperforming the Russell 2000 Value Index by 1,000 basis points (bps).

Value, Growth, Core…What’s the “Right” Choice?

Based on what we’re seeing in more recent index behavior, trying to time the shift between value and growth could carry with it a significant opportunity cost and the risk of being incorrect. Intuitively, one might say, “why not just own all the stocks?,” which could then lead to the Russell 2000 Index: very much the status quo choice. But as we mentioned before, it has never been easier to fine-tune exposure to a market segment through the use of factors.

Over the long term, did Size or “Size-Plus” lead to outperformance?

Continue Reading…