Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

5 ways to turn your Savings into Capital Gains

By Sia Hasan

Special to the Financial Independence Hub

Continuously adding to your savings account is a responsible and astute financial step towards a comfortable retirement. Unfortunately interest rates offered by banks on standard savings accounts make for really slow growth, which is barely enough to keep up with inflation. Fortunately, there are other investment options out there that can increase your money at a more decent pace, one of which is stocks. Here are five techniques to turning your spare cash into a portfolio that grows both in capital gains and dividend income.

1.) Start Small

You don’t need to pour all of your savings into stocks right away. Going about it slowly can minimize risk. For example, if you have $10,000 as your savings, start buying 10 to 20 shares of stocks per month. Consider increasing your order size or frequency of purchase as you gain more experience or as you get more data about specific companies. If company XYZ’s stock price has solid momentum, consider buying more of it.

2.) Dollar Cost Averaging

You can also do dollar cost averaging, which basically involves setting a budget to buy stock each month. For example, if you have $1,000 to invest per month and company XYZ’s stock costs $50 for this month, you buy 20 shares of it. The next month, it costs $40 per share, so you buy 25 shares. The month after that, it actually increase to $100, so you buy 10 shares for that month and so on.

3.) Strategize according to your Lifestyle

A methodical approach to investing is key to growing your investment portfolio consistently. Strategy removes emotions from the equation, which for an investor can be a detrimental quality or set of qualities to bring in the stock market. Figure out what strategy best fits you. Someone who is saving money month after month is probably occupied with a full-time job; hence there are limited hours in the day for monitoring prices and current positions. Continue Reading…

Why “Topping up to bracket” makes sense if you’re temporarily in a low tax bracket

My latest column in Wednesday’s Globe & Mail looks at a strategy called “Topping up to Bracket,” which can be useful to anyone who is temporarily in a lower tax bracket.

Click on the highlighted headline to access the online version, assuming you have Globe subscriber privileges or haven’t exceeded the monthly free click quota: A strong tax case for early RRSP withdrawals.

When might you be “temporarily” in a lower tax bracket than usual? This can of course happen when you lose a job or if you’re in your Sixties and transitioning between full employment (typically earning in higher tax brackets) and Semi-Retirement, when it’s tempting to “bask” in lower tax brackets.

Temporary because as Semi-Retirement progresses, you can end up moving back into higher tax brackets: for example, if you start to receive Old Age Security (OAS) at 65, then take Canada Pension Plan (CPP) a few years later, these are both taxable sources of income.

And the big hit can come at the end of the year you turn 71, when RRSPs must be converted to Registered Retirement Income Funds (RRIFs) or else annualized or cashed out. RRIFs entail forced annual withdrawal rates that keep rising between your 70s and your mid 90s.

So that makes “Topping up to Bracket” (a term used in a BMO Wealth Institute paper on the topic, published around 2013) a strategy not to be ignored. In practice it means making sure that in those low-earning years you at least bring into your hands each and every year the roughly $12,000 of untaxed earnings that’s called the Basic Personal Amount (BPA). And as the G&M column explains, it’s also a good idea to at least bring in the dollars that are in the lowest tax bracket (15% federally, 5% in Ontario), or roughly $42,000. There are of course higher tax brackets above that but the law of diminishing returns starts to kick in beyond the $42,000.

Note too that this is a “use it or lose it” proposition. If for example a year went by that you failed even to bring in even that $12,000 income that would not have been taxed, you can’t carry forward the opportunity to benefit from it the following year. You will of course have another opportunity for the BPA that year but it won’t double up because you neglected to earn low- or non-taxed income the previous year. Continue Reading…

Do men and women have different Savings Habits?

By Danielle Kubes

Special to the Financial Independence Hub

In an online survey about savings habits, financial comparison site Ratehub.ca reports that although Canadian men and women save almost the same amount of money, men have a greater level of confidence in their financial planning.

Inspired by 2014 Statistics Canada data that says Canadian women have lower financial literacy scores than men and were less likely to consider themselves “financially knowledgeable” (31% of women versus 43% of men), Ratehub.ca set out to discover if there truly is a gender divide. 

The company digitally surveyed a random sample of 1,087 Canadians in November, with respondents self-identifying their gender.

“Our survey revealed that while men and women differ in aspects of their financial planning, at the core, their personal finance goals and concerns are nearly identical,” the report says.

Both genders have similar financial goals

Indeed, both genders report almost the exact same financial goals. At the top of list of priorities is retirement, followed by travel and then having an emergency fund.

Both men and women prefer to save and invest in registered accounts, especially the registered retirement savings plan (RRSP) and tax-free savings account (TFSA). What they choose to invest in within these accounts — guaranteed income certificates (GICs), exchange traded funds (ETFs), stocks, or other products — is unknown.

Yet men and women diverge most in how confident they are that they’ll have enough money to retire: less than half of women, 41%, say they’re confident compared to over half of men surveyed, at 56%.

Odd, because both genders save almost the same amount of their salaries, with women saving 26% and men 29%.

The gap could potentially be explained in how able they are to grow those savings through investing. Eighty-five per cent of men invest their money, while only 76% of women do.

Of those that do invest, less women than men self-manage their investments, potentially indicating another worrisome lack of confidence in their financial knowledge.

This is supported by the original Statistics Canada data, which found women were less likely to state they “know enough about investments to choose the right ones that are suitable for their circumstances.”

Confidence doesn’t mean financial knowledge

But does confidence translate to actual financial knowledge? Apparently not. When Statistics Canada quizzed Canadians who rated themselves financially literate, one in every three women failed, while one in every four men failed. Continue Reading…

How high investment fees can diminish Investment Returns

By Chris Ambridge, Transcend

Special to the Financial Independence Hub

The objective for most investors is to earn value-added performance. Unfortunately there are fees and other costs that can diminish investment returns. The reality is that the costs associated with investing in these products can lead to underperformance when measured against industry standard benchmarks.

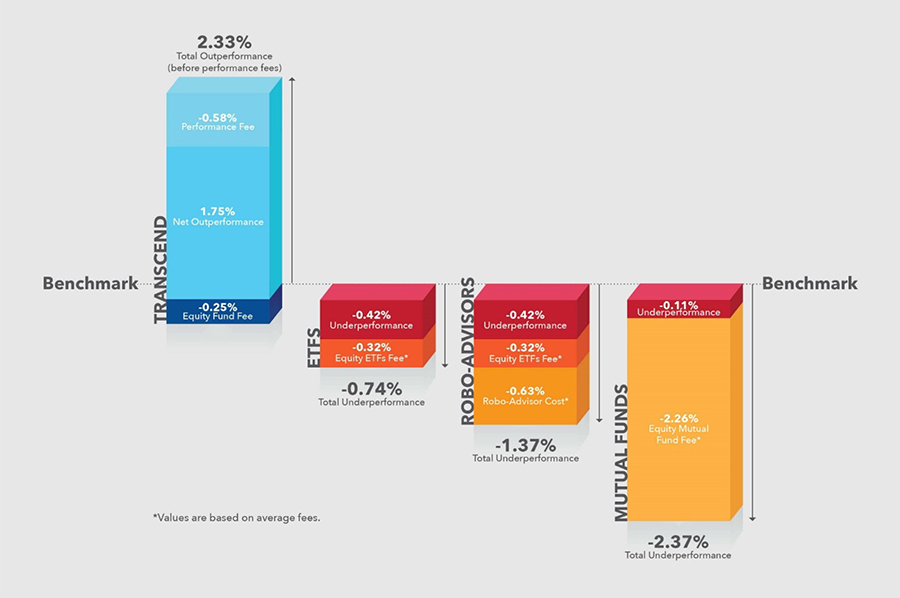
The above chart shows the average annual fees and their impact on investment performance for Equity Mutual Funds, Exchange Traded Funds (ETFs), robo-advisors and Transcend’s Pay-for-Performance™ model. This is illustrated by comparing their returns against a benchmark. The benchmark is a universally accepted representation of a particular stock market that is used to measure the performance of a portfolio manager.  For example, a benchmark for Canadian equities is the S&P/TSX and a benchmark for U.S. equities is the S&P 500.

Ultimately, excessive fees reduce clients’ investment performance and hampers their ability to reach their financial goals.

While ETFs and robo-advisors are gaining in popularity, mutual funds are still the prevalent investment product for retail investors despite numerous studies that have confirmed the weak investment returns of equity mutual funds relative to their benchmarks. In Canada, a fairly new approach developed by S&P Dow Jones Indices called the SPIVA Canada Scorecard confirms performance failings. The latest result based upon five years of data ending December 2016 confirms that equity mutual funds have underperformed their benchmark, often because fees have such a negative impact on the overall portfolio results.

Mutual funds can charge management fees as well as administrative costs and custodial fees. They can also charge clients for trading, legal, audit and other operational expenses. In the chart above, these fees plus investment related underperformance add up to the average true cost (-2.37%) of investing during the last five years for equity mutual funds.

Even low-cost ETFs, which are designed to mirror a benchmark, tend to disappoint. The performance lag can be tied to the level of fees of 0.32%, plus trading and rebalancing costs as well as a potential cash balancing drag of up to 0.42%, based on 2015 data from the Management Reports of Fund Performance (MRFP) found on the SEDAR.ca website. This analysis does not include the negative impact of brokerage costs to buy and sell, and potential custodian or registration fees. With that in mind, the chart reveals that ETF investors underperform the market appropriate benchmark by -0.74%.

Robo-advisors to the rescue?

Another relatively new entrant to the low cost investment marketplace is the robo-advisor. Employing several common assumptions such as an average portfolio size of $50,000 and trading costs of 0.2% per year, it can be determined that the average robo-advisor fee in Canada is 0.63%.

This cost shows that it is more efficient than traditional wealth management fees, but still lags behind the Pay-for-Performance™ model. While everyone is talking about robo-advisors, the true question should be about getting value for your money and how much fees can impact actual outcomes. Continue Reading…

How to prepare for market corrections and advances

“Motivation is what gets you started. Habit is what keeps you going.” —Jim Ryun, Olympic runner

We’re working our way through the fourth quarter 2017. Many stock indices have been hovering near their tops and often keep making new highs. Daily headlines are typically a mixed bag of fears and optimism. They are often interpreted as indications of possible changes in market direction.

Some themes really stand out. For example, NAFTA talks are topics du jour in the US, Mexico and Canada. The United Kingdom is wrestling with Brexit implications. German politics are entertaining altering the seating arrangements.

Many stock indices hover near their tops and keep making new highs.

China faces pressures from increasing debt levels. US tax cut battles keep marching along. Several faces will soon change at the US Federal Reserve. Rising interest rate discussions send chills down the spines of borrowers. These few points alone are forceful enough to create trepidation in investor minds. You will have no difficulty finding headlines for every investment neighbourhood.

As a result, investors develop itchy fingers that want to migrate to the safety of the sidelines, whether it’s beneficial or not. Of course, these investors that have the need for action will make the crucial timing calls on what to buy or sell. Everyone should know by now that timing the markets is a low percentage approach, fraught with many dangers.

My Observation

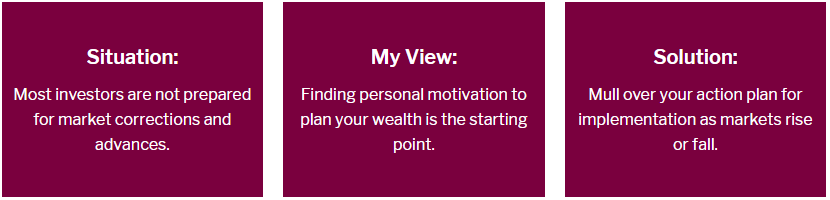
This brings me to one important observation. Wise investors are in the habit of investigating what it takes to be well prepared for both market corrections and advances. They have at least sketched out a rough game plan for each case on the back of the napkin. Something to get started, aiming for the right path. I encourage you to become conversant with what you would likely do with stocks and bonds during bullish and bearish markets.

Most investors that think in this fashion prefer to have some framework of how to approach the uncertainties that come their way. Just some simple ideas are required to get started. The best news is that today’s planning is being conducted while stock prices are high.

Finding the motivation to be informed is a welcome initial step. Perhaps, discussions with your investment professional will shine more light on what actions are in your best interests. Reconfirming your family risk profile is also time well spent. Hopefully, these efforts lead to more disciplined planning for the precious nest egg. The main mission is to reach and deliver your retirement objectives.

Seasoned investors are well aware that diversification and rebalancing strategies are part and parcel of this logical planning approach. I cannot emphasize that enough as nobody knows where the markets are headed or when a directional turn comes around the curve. Bells do not ring when the time is ripe to make portfolio changes. Neither at the top, nor at the bottom.

My Recommendation

I suggest mulling over these situations in preparation for your exercise: Continue Reading…