Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Chinese A-shares to go mainstream with inclusion in MSCI EM Index

(Sponsored Content)

Chinese equities will be going mainstream next year following a decision by the MSCI to include 222 China A-shares in the MSCI Emerging Markets Index (EMI). China A-shares were traditionally only available to domestic and qualified institutional investors, but have recently expanded global investor access through the Hongkong-Shanghai and Hongkong-Shenzhen Stock Connect programs.

The A-share market, including shares from Shanghai and Shenzhen markets, is worth roughly $7.5 trillion, the world’s second largest after the New York Stock Exchange and Nasdaq.[i]

“The decision to include China’s A-shares on the MSCI Emerging market index is very positive for the onshore listed companies as well as foreign retail and institutional investors, who will now benefit from more investment opportunities in China’s domestic growth” says Christine Tan, Chief Investment Officer and Senior Portfolio Manager with Excel Investment Counsel Inc.  “This decision comes after four years of consideration, during which the Chinese regulators have made many positive changes to improve investor access to the onshore equity market.”
Christine Tan

“These A-share corporations will benefit from increased investor interest and flows,” says Tan. “In turn, mutual funds such as the Excel China Fund and Excel Chindia Fund will now invest directly in China-listed companies for further diversification and access to sectors that were not well-represented on the HongKong exchange.”

Almost $18 billion to move into Chinese stocks

According to the MSCI, the inclusion of A-shares on the index will result in about $17 billion to $18 billion of global assets moving into Chinese stocks initially. Continue Reading…
6 ways to ensure you won’t outlive your money

“Retirement: World’s longest coffee break.” —Author Unknown

Over the years you’ve taken plenty of advice, saved and invested diligently. Now you and your family are knocking on retirement’s door or, perhaps, in its midst.

The good news is the family members will likely live longer than before. The flip side is that more money may be required to fully fund retirement lifestyle.

Let’s assume that retirement spans from age 60 to 90, often longer. Many worry that the money won’t last and runs out during retirement.

Analyze life expectancy of the immediate family members for both spouses or partners. Specifically, review the current ages of grandparents, parents, uncles, aunts and cousins.

Some are petrified at the mere thought of such a prospect becoming reality. The question becomes what you can do to at least contain this situation.

I summarize six essential ideas designed to ballpark your lifestyle needs and help your retirement money last:

1. Family life expectancy

Analyze life expectancy of the immediate family members for both spouses or partners. Specifically, review the current ages of grandparents, parents, uncles, aunts and cousins. Get familiar with the ages attained by family members that have passed away. Pay attention to patterns of critical illness and longevity.

Today, it is commonplace for many to live well into their 80s. It is wise planning for a family to expect that at least one spouse could easily live past age 90. Another expectation is that family longevity continues to increase. Updating the retirement projection refreshes the family’s capital needs for the desired lifestyle.

2. Becoming too conservative
Continue Reading…

It’s tough managing money: somebody has to do it, but not necessarily you!

Protecting and growing your retirement nest egg is one of your most important financial responsibilities.  Ensuring that your nest egg is sufficient to fund your lifestyle in retirement often means putting at least part of it at risk in the stock market.

Unfortunately, too many people are swayed into believing that being a successful stock market investor means you have to actually beat the market.  Beating the market is really, really difficult, especially over longer periods of time.  It’s a tough job, but why is it so difficult?

Picking outperforming stocks is hard

A recent article from one of our favourite authors and commentators, Larry Swedroe, highlights some data points from studies that indicate why stock pickers might have such a tough time beating the market:

  • The Russell 3000 Index of the largest 3000 US stocks delivered an annualized return of 12.8% between 1983 and 2006
  • While that’s an impressive return over that period and achievable for anyone investing in a Russell 3000 Index fund (if there was one in 1983!), trying to beat that index by picking stocks would have been a formidable task – here’s why:
    • the median annualized stock return was only 5.1% and the average stock actually lost money, -1.1% annually
    • 39% of stocks lost money
    • half of the stocks that lost money lost at least 75% of their value
    • 64% of stocks under-performed the Russell 3000 Index
    • just 25% of stocks were responsible for all of the gains.
    • only 48% of stocks returned more than one month Treasury bill returns

No wonder it’s so difficult to beat market indices. Outperforming stocks are really hard to find!

Even the pros find it difficult

Continue Reading…

Do you need to “De-FANG” your portfolio of giant US tech stocks?

Do you need to De-FANG your portfolio or are you so focused on Canada that you’re actually underweight on the big US tech stocks?

My latest MoneySense column looks at the post-Trump surge in tech stocks and the more recent retrenchment in the sector. For the full article, click on the highlighted text here: Do you need to de-FANG your portfolio.

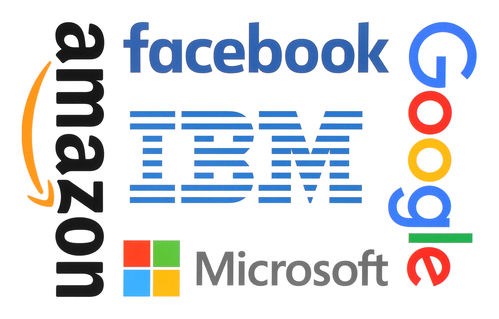
FANG is of course the famous acronym created by Mad Money’s Jim Cramer and stands for Facebook, Amazon, Netflix and Google.

But as the piece goes into in some detail, and per the image above, there are alternative acronyms that include Apple and Microsoft, although not IBM (despite the graphic above).

The question is whether so-called “Couch Potato” type investors who use the MoneySense ETF All-stars already have sufficient technology exposure to participate in the expected long-term growth of technology and particularly Internet giants like Google, Facebook, Amazon and the like. Certainly after last week’s  big announcement that Amazon seeks to acquire Whole Foods, this question is increasingly relevant.

As you’ll see, broad-based ETFs tracking the S&P500 index already have significant tech exposure: roughly a third in these names. Less so for global ETFs exposed to firms outside North America, although these too have healthy exposure to the sector.

Canadian-centric investors woefully underweight technology

Continue Reading…

How to set long- and short-term financial goals

By Angela Baker

Finances are always problematic, and everyone struggles to find balance in this field.

At the beginning of our professional careers, we are on a tight budget with little perspective for any progress. As time passes, our financial goals get higher and desires may seem unrealistic.  There are many ways to plan finances and to set long-term and short-term financial goals. Below, we will try to explain steps for success in this activity.

Define goals and objectives

If you decided to set financial goals, start with clear contemplation about what you need and how you will achieve that. This is the first and most important step. Decide how much money you want to possess each day, month or year. Then after you have determined the amount, start to plan the way for realizing the financial goal.

This may include a new activity like running a website, opening a store, renting houses or finding a well-paid job. No matter what is it, you need a lot of planning and counting. Also, you must research a lot, listen to advice from friends, people around you, and acquaintances. Only with fully-planned action will you be on the way to achieve short- and long-term financial goals.

Identify your financial requirements

The second strategy in setting your financial objectives includes identifying personal needs about money. Everyone spends a certain amount of money daily for basic needs as food, car, hygiene, or meetings with friends. If you live alone, it will be easier to recognize personal requirements because we all know our own needs. Otherwise, if you have a big family and  have to maintain all of them, it will cost you days to count how much money you need. Also, you should not leave out extra spending for a holiday, services in the house, clothes, etc. The final list could make you scared or nervous, but you must face it.

Improve your saving habits

Continue Reading…