Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

A nation of financial illiterates?

By John Shmuel, Managing Editor, LowestRates.ca

Special to the Financial Independence Hub

Do you consider yourself financially literate?

When we posed that question to Canadians last month in an IPSOS survey, the overwhelming majority — 78% — said yes.

Canadians are clearly confident about their financial knowledge. But their actual knowledge, unfortunately, is lacking. When we followed up our initial question with a quiz, comprised of 15 intermediate questions about financial products, the majority of Canadians (57%) failed.

It should be noted that these weren’t simple questions. But they also weren’t questions that require special certification or an advanced knowledge of finance. One question asked whether there were financial institutions in Canada that offer free chequing accounts (there are). Another asked whether you needed a special license to buy stocks (you don’t).

Failure to know the answers to these questions shows that Canadians are confused about financial products. And financial institutions take advantage of that.

Let’s return to the question on chequing accounts. About 34% of those surveyed said they thought all banks charge you money to have a chequing account. Another 14% said they didn’t know the answer. With nearly half of Canadians not realizing free chequing accounts are an option, it’s no surprise many financial institutions continue to charge for them.

Then there is the issue of mortgages. Of our 15 questions, Canadians struggled with ones related to mortgages more than any other. For instance, we asked whether a mortgage term refers to the length of time you need to pay off your mortgage. 51% of Canadians answered incorrectly. Another 18% said they don’t know. (For those wondering amortization refers to the length of a mortgage, a term is how long variables such as your interest rate are in effect.)

So what?, you might say. What does a mortgage term have to do with being knowledgeable about finance?

It all comes down to empowerment. If you’re familiar with how a financial product works, you’re more likely to be confident in getting the best deal for that product. Knowing what a mortgage term is you probably know that you can negotiate mortgage rates, or that you can go online and see different rates from rival banks and brokerages. Continue Reading…

Business Owner suffering Pension Envy? Here’s a Remedy

Jean-Pierre Laporte

The Globe & Mail’s Report on Business has just published my piece titled A remedy for sufferers of pension envy, which you can access by clicking the highlighted text.

It describes the long-established Individual Pension Plan (IPP) and a newer variant called the Personal Pension Plan (PPP). The creator of the latter, Jean-Pierre Laporte (pictured to the left) estimates 1.2 million Canadian business owners could benefit from these plans, which are in effect Defined Benefit (DB) pension plans designed for professionals and business owners.

The newer PPP from Integris Pension Management Corp. is a hybrid in that it can be either a DB plan or a more market-sensitive Defined Contribution (DC) pension.

Trevor Parry

Several sources in the piece have written at more length on these topics here on the Hub. For example, see this blog from the Hub last November: How a Personal Pension Plan can mimic gold-plated DB pensions. Or see Trevor Parry’s most recent Hub blog, Making Canada Great Again. Perry sees both IPPs and PPPs as increasingly relevant in the current Canadian tax environment.

Tim Paziuk

One source I consulted for the piece but didn’t appear is financial advisor and author Tim Paziuk. Paziuk – of Victoria, BC-based TPC Financial Group Ltd. – laments the fact that “employees of the public sector and large corporations enjoy benefits and retirement plans that are unavailable to the private business owner.” As he noted in a recent Hub blog after the last federal Budget — On the Middle Class and Paying One’s Fair Share of Taxes — the pending Liberal working paper on the middle class and tax fairness doesn’t augur well for owners of corporations and even family members who enjoy “income sprinkling” from such corporations.

Fortunately new tools like the PPP and the not-so-new IPP give business owners a way to fight back. You can find on the web various debates between those who prefer the IPP and the PPP. For example, also quoted in the Globe article is Stephen Cheng, of Westcoast Actuaries, who has debated the plans with LaPorte here. Laporte’s reply can be found here: Comparing old IPPs to PPPs.

Motley Fool: Canadians overrate their financial literacy?

P.S. Here’s my latest blog for Motley Fool Canada. The headline pretty much sums up the story: Overconfident Millennials and Gen X flunk Financial Literacy Test, but Boomers only marginally better.

And while on the topic of financial literacy, I was gratified to be named one of Canada’s top online finance influencers, as conveyed by RazorPlan.com in this post.

5 Steps to a Victorious Retirement

Who doesn’t want a Victorious Retirement?

Just in time for the long weekend and Canada’s 150th birthday, MoneySense.ca has just published a 5-part series on retirement, going from deciding what you want to working longer, the Ages & Stages by decade, being a snowbird, and finally what to do once you finally reached the hallowed land of Retirement/Findependence/Victory Lap.

Here’s a summary of each piece (all written by Yours Truly), and links to the full articles:

1.) The first step: What do you really want?

Take a custom approach to retirement planning. There’s no point fretting too much about retirement and how much to save if you haven’t first determined what you want to DO once you’re retired. For starters, how are you going to fill those 2,000 hours a year you use to spend in the office and commuting? Click here for full article.


2.) We live longer. Why not work longer?

Ask questions about a retirement plan that’s right for you. Life expectancies are on the rise: more and more Baby Boomers can expect to become centenarians and that probably goes double for their children, the Millennials. Makes sense to consider working a little longer, if only part-time. Or if you really dislike your chosen profession, go back to school or retrain and find something you’d really enjoy doing in your golden years: preferably something that pays! Click here for full article.


3.) Snowbird? Learn the “substantial presence” test

Learn the tax pitfalls of retiring to the sun in the U.S. It all depends on how long you plan to stay down south each year: the formula isn’t simple. If you don’t relish the thought of paying tax to two countries, you may want to make sure you’re not considered to have a “substantial presence” in the U.S.  Click here for full article.

4.) Your retirement plan has a life cycle

Retirement planning strategies for every age. Every decade from your 20s to your 70s and beyond should take you a little further along the journey to financial independence/Retirement. Just like we all share the same fate in our human life cycle, so it is with the financial life cycle. Click here for full article.


5.) Retirement planning —after you retire

The plan doesn’t stop when you stop working.

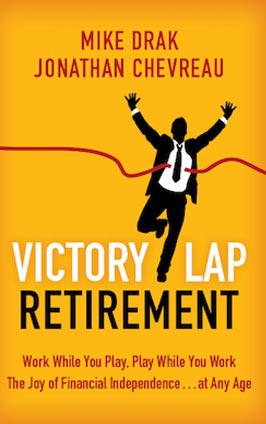
My co-authored book Victory Lap Retirement features on its cover what appears to be a sprinter breaking through the finish line of a long marathon. But that doesn’t mean we’re saying Retirement is a literal finish line and with it the end of striving and purpose. In fact, we’re saying a “Victory Lap” really only begins when you reach the “finish line” of financial independence, or Findependence.

There will still be a big adjustment as you move from Wealth Accumulation to the De-accumulation or “Decumulation” phase: less earned income and more passive sources of income. And you’ll need to master the tax aspects because Tax may be one of the biggest expenses in Retirement. Click here for full article.

5 common mistakes when working with an advisor

Chris Ambridge

By Chris Ambridge, Transcend

Special to the Financial Independence Hub

Canadians are often faced with complex and nondescript investment products that can be overwhelming.  As such, most people need professional advice. With personal recommendations as one of the most common forms of referrals, selecting the right advisor should also be based on qualifications, fees that won’t gouge, and the advisors autonomy to act in the best interest of the customer.

However, many people are now spending a significant amount of time surfing the web and seeking advice online, where it can be difficult to distinguish expert advice from the inept.

In Canada, 96% of registered advisors are “dealing representatives,” which means they are salespersons not legally required to look after your best interests. On the other hand, just over 4,000 advisors are registered in categories where they must act as true fiduciaries and are legally required to deliver clients advice that must be in their best interest. While there are many financial advisors who look after their clients in the same way as true fiduciaries and deliver exceptional support and guidance, there are a whopping 118,000-plus advisors who do not have to adhere to such standards.

As an investor in search of an advisor, your goal should be to find the right person to help you reach your future financial goals. While you can correct a poor choice down the road, you would have wasted valuable time and may have actually suffered financial setbacks. It is therefore paramount you avoid the following mistakes:

Mistake #1

Don’t fall for the opening pitch. No matter how enticing the discussion and no matter how obvious the initial set of benefits are, chances are you are only seeing one side of the equation. No one wants to reveal their warts, especial right off the bat. So take your time to establish a rapport with the advisor. Trust comes with knowledge and clarity so make your first appointment about gathering information and creating a connection.

Mistake #2

If investments and products are the first subject of conversation before attempting to build a profile of you and your family, take a pass. Remember you are looking for someone that can give you personalized advice and not a canned spiel or off-the-shelf solution. If the advisor starts talking about investments before understanding your fears then you should think twice.

Mistake #3

Continue Reading…

Top global investment trends of 2017

By Sia Hasan

Special to the Financial Independence Hub

One of the most important things anyone can do for their future is to invest. There are many ways to build wealth over time if you start early and stay consistent no matter what the market is doing.

There are many global investment trends in 2017 that you need to know about. With all the changes that are going on around the world, this is one of the most important things you can look at changing in your personal finances. When it comes to investing, it pays to look at ways that you can improve constantly.

Real Estate

In many parts of the world, real estate is starting to heat up. With fewer properties on the market, many investors want to take advantage of real estate demand. In some developing nations, there are still opportunities to invest in growing areas. In certain places like the United States, the real estate market is so competitive that it is difficult to find a solid deal for the future. You always need to think five or ten years down the road when you are investing in real estate. This is true whether you are buying a home to flip or if you are just buying a home to rent out.

One other reason to consider real estate is that interest rates are still low. With the low rates, the amount of interest you have to pay on your debt is minimized and you can make more money as an investor. If you borrow money this year, it will be cheaper than in the future.

Equities (Stock Market)

When it comes to investing in the stock market, many are worried that we are in bubble territory. The stock market has been on a positive run for nearly a decade now. At some point, there is going to be a correction, and no one wants to invest right before a crash. If you are going to invest in the stock market, you need to have a plan for the future. Investing in the stock market is all about thinking many years down the road. Continue Reading…