Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

How to Supersize your RESP – Use it as a TFSA and other tips

By Aaron Hector, Doherty & Bryant Financial Strategists Inc.

Special to the Financial Independence Hub

The purpose of this article is to show you how to think outside the box and use an RESP [Registered Education Savings Plan) in ways that you may not have previously considered. But before we get to that, let’s look at the basics.

How does an RESP work?

To help you save for your child’s post secondary education, the government provides a 20% match by way of the Canada Education Savings Grant (CESG). The CESG matching is subject to both annual and lifetime maximums.  Specifically, on your first $2,500 of contributions each year, you’ll receive $500 in grant money, to a maximum of $7,200 in lifetime grants per child. To illustrate over time, if you contribute $2,500 per year, you will max out the grants available to you in 15 years (14 years at $2,500 + 1 year at $1,000, with a 20% match = $7,200).

If you don’t start making contributions when your child is born, or if there’s a lapse in contribution installments, you are able to ‘reach back’ and receive grants for previous years. You can reach back one year at a time. Therefore, you could consider a contribution of up to $5,000 this year if you missed making a contribution last year, or any year prior, and that would net you a CESG of $1,000 in total- $500 for the current year grant, and $500 for a prior year grant. The carryforward of unused CESG accumulates for every year including the year of birth, regardless of whether you have actually opened an RESP account.
Continue Reading…

Raising Retirement Age: Can the Liberals find a way in upcoming Budget to tempt us to wait until 67 for OAS & CPP?

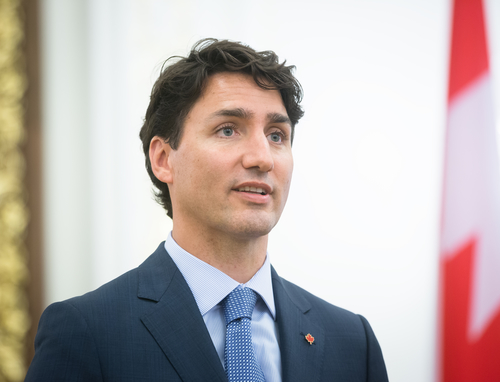
PM Trudeau reversed the Conservatives’ plan to raise OAS from 65 to 67, making it harder to follow advice to raise the Retirement Age going forward.

My latest Motley Fool blog looks at whether the Liberal Government intends to implement any suggestions by its Economic Advisory Council about raising the Retirement Age. See Will the Looming Federal Budget Try to Slip by Another Senior’s Benefit?

Of course, as one source says, the Government officially doesn’t want to raise the age of OAS and CPP eligibility from the current 65 to 67. After all, if it wanted to do that, all it had to do was leave in place the Harper administration’s policy that would have done just that for Old Age Security, albeit phased in gradually by the year 2023.

Even so, they must be sorely tempted, considering the fact that so many other Governments around the world are raising the retirement age to accommodate rising life expectancy patterns. The number of OAS recipients is expected to double over the next two decades, as more and more Baby Boomers take the plunge into Retirement, or at least Semi-Retirement.

Still, there’s more than one way to skin a cat. As I point out in the blog, anything as radical as raising the retirement age needs to be implemented gradually so as not to wreck the well-laid plans of financial advisors and clients who may have been counting on the rules as they now exist.

Delaying retirement age should be voluntary, not compelled by Government

Continue Reading…

“Botched” CRM2 implementation just adding to investor confusion: veteran adviser

Tim Paziuk

By Tim Paziuk

Special to the Financial Independence Hub

After 37 years in the financial services industry I realize I shouldn’t be surprised, and I’m not. I’m shocked. Shocked by the confusion created by the very people who are charged with the responsibility of watching out for us, mainly the Canadian Securities Administration (CSA).

Here is the first paragraph from the overview on the CSA website

The Canadian Securities Administrators (CSA) is an umbrella organization of Canada’s provincial and territorial securities regulators whose objective is to improve, coordinate and harmonize regulation of the Canadian capital markets.

I draw your attention to the words ‘improve, coordinate and harmonize’. In my opinion, they have done more to hinder and confuse the average Canadian than to provide clear and complete information.

Let me give you some background on the recently implemented program referred to as the Client Relationship Management Model – Phase 2 (CRM2).

According to the Ontario Securities Commission:

The Client Relationship Model – Phase 2 (CRM2) amendments to NI 31-103 that came into effect on July 15, 2013 are being phased-in over a three-year period. These amendments introduce new requirements for reporting to clients about the costs and performance of their investments, and the content of their accounts. The requirements apply to dealers and advisers in all categories of registration, with some application to IFMs as well. For more information about these amendments, see CSA Notice of Amendments to NI 31-103 and to 31-103CP (Cost Disclosure, Performance Reporting and Client Statements). Continue Reading…

Q&A: Stock markets are at all time highs … should we sell?

By Steve Lowrie, Lowrie Financial

Special to the Financial Independence Hub

Here’s a question I received recently, which rhymes with many I’ve heard before:

Now that the Dow has hit 20,000, we should seriously get out and put the cash under the mattress … don’t you think?

This time it was the Dow’s recent high-water mark. In the past, it’s been the same question in various forms, all of which could be rephrased to this question behind the question: Should the all-time nominal stock market highs be used as some sort of signal to reduce equity holdings?

Or conversely, should it be used as a rationale for holding onto cash balances or deferring new equity purchases (which, in my experience, is an even more common form of market-timing)?

It is human nature to look for shortcuts and/or ways to simplify complex questions. The fact that people predict outcomes by making up stories is what makes us all … humans.

Timing the markets when they’re at all-time highs is a nice, neat and simple story. Unfortunately it’s a fable; it doesn’t work. To use a “baseball story,”  three strikes and you are out.

One.

I can point a couple of my past posts here and here for frowning on these sorts of signals, or treating them as anything other than the noisy blips they are on your financial radar screen. Try to chase them, and you’re more likely to be left flying blind.

Two.

Nominal levels ignore market valuations. That means new market highs may be fun, but they’ve not been worth beans for predicting future returns. Those are expected either way, but for entirely different reasons.

Three.

To take a deeper dive into the subject, Dimensional Fund Advisors has done the heavy lifting for us in “New Market Highs and Positive Expected Returns.”Their conclusion is that it doesn’t work. Give it a read if you want all of the details.

Still not convinced? … then please contact me.

Steve Lowrie holds the CFA designation and has over 20 years of experience dealing with individual investors. Before creating Lowrie Financial in 2009, he worked at various Bay Street brokerage firms both as an advisor and in management. “I help investors ignore the Wall and Bay Street hype and hysteria, and focus on what’s best for themselves.” This blog appeared originally appeared on his site on February 3rd and is republished here with permission. 


A retired Advisor’s Open Letter to Bill Morneau on expanding TFSA

Finance Minister Bill Morneau (bmorneau.liberal.ca)

(To:) Hon. Bill Morneau, Minister of Finance,
House of Commons, Ottawa.

Dear Hon. Minister,

Thank you for your response to my previous letter. I am a strong believer in an enlarged Tax-free Savings Account (TFSA) and have NINE reasons for that belief through my experience as an IA (Investment Advisor).

I think you will agree that the larger TFSA makes retirement savings fair for all levels of Canadians incomes, but helps those who need it most as there is little RRSP deduction benefit for low-income Canadians. I think your background experience will lend itself to agreeing with my nine reasons for restoring the $10,000 TFSA.

Restore the $10,000 TFSA

The $10,000 TFSA [the previous annual contribution level] is the most profound and beneficial social program created in Canada’s 21st century. It benefits the young, seniors and the less fortunate as well as the well off. Its principal benefit is a meaningful and manageable amount of money which can be used as a saving vehicle and a retirement savings account.

1.)  It is especially beneficial to the non-working spouse, by enabling a savings and retirement account not requiring a monthly pay cheque and its commensurate income tax and tax deductions. This was the principal reason for the Americas Roth IRA, (ROTH account withdrawals are tax free,  but after the age of 58.)

2.) The larger TFSA amount is a meaningful savings target by today’s standards in that $400,000 can be accumulated over 40 years of adult life. Continue Reading…