Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

TFSA Primer 2017

“Many investors are wondering whether to pursue a TFSA or RRSP strategy. Quite simply, the TFSA, which started in 2009, compliments both the RRSP and RRIF.”

It need not be an either/or approach.
Wise investors embrace the Tax-free Savings Account (TFSA) in pursuit of long term goals, like retirement.


I summarize my 2017 TFSA primer:

1.) How TFSAs work

Eligibility:

• Canadian residents, age 18 or older, who have a Social Insurance Number can open a TFSA.

• One TFSA account per individual should suffice most cases. Be aware of plan fees if you own more than one.

Contributions:

• There is no deadline for making TFSA contributions as the unused contribution room is carried forward.

• A withdrawal in any calendar year increases the TFSA room in the following year.

• TFSA contributions can be made in cash or “in kind” based on the calendar year.

• Deemed disposition rules for “in kind” contributions are the same as those for RRSPs.

Your maximum TFSA deposits are as follows:
Continue Reading…

RRSP Gross-up Strategy: Contribute 40-70% more to your RRSP

“Never put dry pasta into your RRSP.”

By Ed Rempel

Special to the Financial Independence Hub 

Wouldn’t it be great if you could save a lot more for your future without affecting your day-to-day cash flow?

One of the main things people learn when they first have a retirement plan done is that you need to invest more than you thought to have the future that you want. But with all the day-to-day expenses, it can be difficult to find the money to contribute as much as you would like to your RRSP.

The RRSP gross-up strategy is a simple strategy that can make a huge difference for you. It can enable you to easily contribute 40 to 70% more to your RRSP.

The strategy works if you already expect a tax refund. If you contribute monthly to your RRSP or have various tax deductions or credits, you probably expect a tax refund.

It is smart to gross-up every RRSP contribution you make.

You have three options with your tax refund:

  1. Spend it.
  2. Invest it.
  3. RRSP gross-up strategy.

Here is how the RRSP gross-up strategy works. Continue Reading…

The power of positive thinking

Positive thinking is a state of mind that allows you to focus on the bright side of life and believe that you can overcome any obstacle and difficulty, including dis-ease. While not accepted by everyone, the concept is growing in popularity. Optimism is the key to effective stress management and we already know that stress negatively affects our health.  The health benefits of positive thinking continue to be researched but may include an increased life span, lower rates of depression, greater resistance to the common cold and a reduced risk of cardiovascular disease related deaths.

The way you think, feel and act has an effect on your body and there is growing evidence that you can change your health just by changing your mindset. Emotions can impact the course of an illness and the mind can affect the outcome of disease. For example, a stomach ulcer may develop after a stressful event, such as the death of a loved one or loss of a job.

Body speaks to Mind

At the root of every physical symptom is an emotional connection; the body speaks the mind. Poor emotional health can weaken your immune system. Continue Reading…

Impact of the Trump administration’s Potential Tax Reform

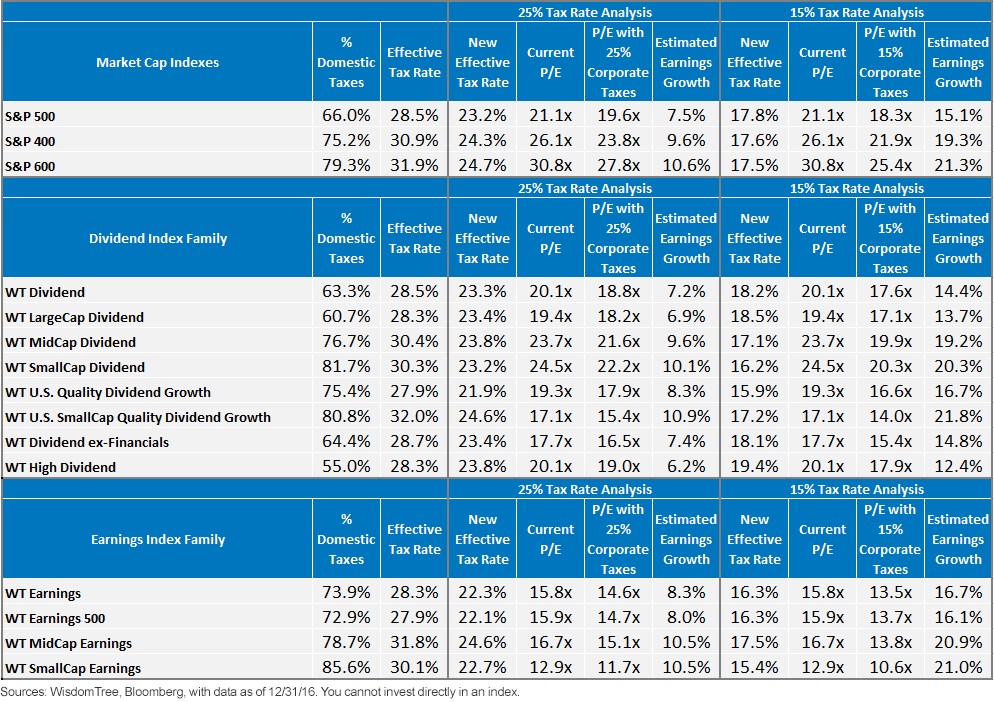
Summary of potential tax cut across Indexes

By Jeremy Schwartz, Director of Research, WisdomTree Investments and

Josh Russell, Quantitative Equity Strategist, WisdomTree Investments
Special to the Financial Independence Hub


Corporate tax cuts were a focal point of Donald Trump’s campaign — and Trump says lowering corporate taxes will be a priority in his first 100 days as president.

Based on the initial market response to Trump’s victory, lowering tax rates looks to us like the most important factor driving the market.

Equity markets, of course, like it when taxes are cut. It naturally means more after-tax earnings that can be reinvested or distributed to shareholders — and, importantly, an improvement in valuation ratios that many think look extended under present circumstances.

We published an initial sensitivity analysis to look at how various assumptions on tax rates might impact the earnings growth and ultimate market valuations across a market cap-weighted index set of the S&P 500, S&P 400 and S&P 600 — and across the sectors in those indexes. We have updated our original analysis to also include domestic WisdomTree Indexes; we also have updated our initial model for estimating the potential tax benefit that shows new results for the cap-weighted index family.1

Lower Tax Rates = Big Earnings Growth and Market Moves in Small Caps 

To summarize the results, a simple model shows the following: the more earnings (and taxes paid) that come from the U.S., the greater the earnings growth would be from a tax cut, because by and large, the companies with revenue across the world already have lower effective tax rates. Continue Reading…

Millennials don’t get the Latte Factor

Financial author David Bach introduced the Latte Factor as a metaphor for all the small indulgences we regularly treat ourselves to that add up over time. It wasn’t meant to single out Starbucks as the main culprit for our financial woes, but somehow millennials feel the need to stand up for their beloved coffeehouse and defend their right to buy an obnoxious drink whenever they damn well please.

Helaine Olen (not a millennial) made people feel good about buying lattes again when, in her best selling book, Pound Foolish, she explained how the Latte Factor is a lie and buying coffee every day is not why you’re in debt. No, instead it’s the big things: housing, transportation, health care (in the U.S.) that are more difficult to cut back on.

Related: The worst financial advice ever given to millennials

More recently, this author whined about how millennials were being judged on their spending choices, criticizing a survey that revealed millennials spend more on coffee than on saving for retirement:

“Millennials are continually being accused of wasting money on supposedly frivolous things. In October, an Australian man named Bernard Salt wrote that he had had enough of seeing young people ordering “smashed avocado with crumbled feta on five-grain toasted bread at $22 a pop and more. Twenty-two dollars several times a week could go towards a deposit on a house,” wrote Salt. 

According to my calculation, if millennials were to abstain from their avocado toast three times a week, they’d save around $3,432 per year. Which isn’t all that much, in reality.”

Oh really? And in what reality is $3,432 not that much money? According to the author, life is unfair and millennials should just give up on the idea of owning a home, or saving for retirement, so just let them have their damn latte and $22 toast.

My take on the Latte Factor Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.