Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

Fed up: Latest Fee Grab Enrages Banking Customers

robb-engen
Robb Engen, Boomer & Echo

By Robb Engen, Boomer & Echo

Special to the Financial Independence Hub

For years Canada’s big banks have walked all over their retail customers without fear of repercussion. They’ve raised account fees and hiked minimum balance thresholds at will, invented new charges for moving our money around, and generally nickel-and-dimed us to death just because they can.

Related: 10 fees you can avoid

Banks get away with it because of the perception that it’s difficult and inconvenient to switch. Typical Canadians, we grumble about the fee grab for a while,  then quietly return to our normal everyday routine.

But this time it feels different. While banks continue to enjoy record profits – particularly from their retail banking operations – consumers are paying higher fees and earning lower interest on savings deposits. Continue Reading…

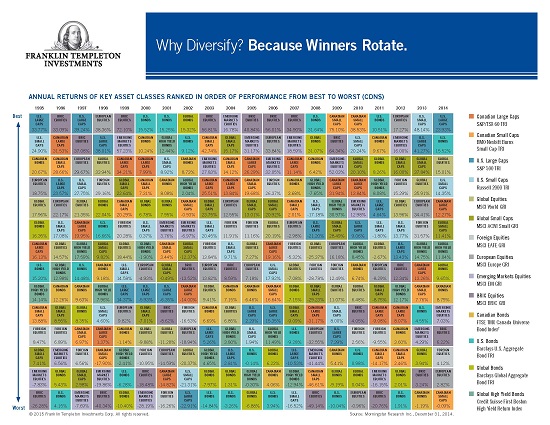
US Large Caps top Templeton asset-class chart but remember Winners Rotate

Here’s my latest MoneySense column, entitled Why Diversify? This chart shows you why. I used to write about this chart back at the Financial Post, and tacked the chart up on my cubicle wall. An updated version of the chart later followed me to my office at MoneySense, and the one below is now in my Editor-at-Large’s home office. Click on the above link to get to the chart, which can be further enlarged on your monitor.

The Hub’s version of the blog below also shows a second chart at the bottom about Risk. As you’ll see, it’s more predictable, living up to Franklin Templeton’s assertion that risk is more predictable than returns. I’ve always found it a useful reminder of the futility of chasing last year’s winners or attempting to predict next year’s winning asset classes. If you can’t get the charts  free through your financial advisor, you can download them here.

By Jonathan Chevreau

Franklin Templeton Why Diversify_low resolution

Continue Reading…

How to get the new TFSA limit to work for you

Illustration depicting a red and white road sign with a taxt free concept. Blue blurred sky background.

By Jonathan Chevreau

Financial Independence Hub

Here’s my latest column from the print edition of MoneySense magazine, written right after the federal budget: Get the new TFSA limit to work for you.

Click on the link for details, but in a nutshell — and has been extensively reported in the media, such as this piece by Gordon Pape (subscribers only)  — there’s no reason why you can’t add another $4,500 to your Tax Free Savings Account right now, in addition to $5,500 you may have contributed anytime on or after Jan. 1, 2015. (Note to American readers: the TFSA is the equivalent of Roth IRAs, providing no upfront tax deductions but which let you eventually withdraw money tax-free in Retirement or for other purposes).

That means a whopping $20,000 per couple. Now while Liberal Leader Justin Trudeau seems to think only “rich” people have that kind of money available, the fact is that many hard-working middle class people have been saving and investing for the better part of two or three decades, and built up substantial non-registered or “taxable” portfolios. Even though they may have paid income tax to acquire the capital in the first place, over those decades they have been paying annual taxes on interest, dividends and (often) capital gains generated by that capital.

As the column points out, those who have built such “open” portfolios don’t have to use new cash to put $10,000 per annum into their TFSAs. They merely have to start transferring their non-registered securities into their TFSAs. This is called a “transfer-in-kind” Continue Reading…

How parents can give their children the gift of future Financial Independence

Two Red Christmas Balls with Blank Embossed PaperFriday’s post on how Hub readers are generally embracing the $4,500 TFSA expansion promised we’d run one particular letter in full on Sunday.

Below is the letter referred to.  The parents in question gave this letter to their three children at Christmas of 2011, just a few years after Tax-free Savings Accounts were launched. They gave us permission to run it, in the hopes that other families could benefit from the ideas, which include parental matching of whatever savings the kids can come up with to fund their TFSAs.

Merry Christmas    2011

 Name  of Child here _____________________                    

This Christmas and future Christmases Mom and I wish to help you to start planning and working towards your long term financial goals/security. We realize that as responsible young adults you use your financial resources to meet your everyday fixed/living expenses and that with your busy lifestyles you do not always have the time to manage/consider long term financial planning. Continue Reading…

What’s the right amount of retirement income?

MarieEngen
Marie Engen, Boomer & Echo

By Marie Engen, Boomer & Echo

Special to the Financial Independence Hub

“Money may not be the most important thing in life, but it’s way up there with oxygen.” – Zig Ziglar

How much is enough? That’s a question that’s asked often. Everyone measures the concept of “enough” differently. Some of us think in terms of dollars per month or year:

  • $50,000 per year
  • $5,000 per month

Or, you may think of a percentage of pre-retirement income:  70-85%.

Many want to know what the “average” Canadian needs, or what “most” people require.

The proper question is, “What is enough for me?”

Related: Budgets, Cash Flow Plans, and Spending. Yawn.

If you are retired, or close to it, I’m going to give you an assignment (should you wish to accept it).  Spend some serious time with this. You are going to make three budgets. Continue Reading…