Building Wealth

For the first 30 or so years of working, saving and investing, you’ll be first in the mode of getting out of the hole (paying down debt), and then building your net worth (that’s wealth accumulation.). But don’t forget, wealth accumulation isn’t the ultimate goal. Decumulation is! (a separate category here at the Hub).

How NOT to invest (Book Review)

Amazon.ca

Special to Financial Independence Hub


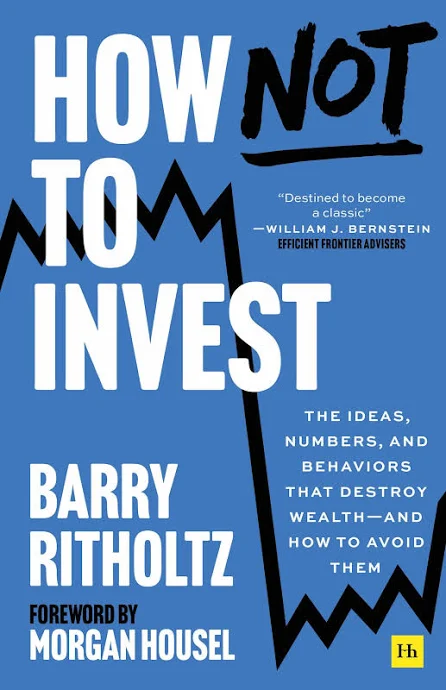
Before reading Barry Ritholtz’s book How Not to Invest, I wondered if the “Not” in the title was a sign it would be filled with gimmicky ways of giving investment advice.

It isn’t.  Investing well is simple enough, but the world tries to push us towards many types of poor choices that lose us money.  The best advice is a list of the many things to avoid when investing.  This book gives readers the benefit of Ritholtz’s extensive experience with staying on the simple path to investing success.

The book is organized into four parts: Bad Ideas, Bad Numbers, Bad Behavior, and Good Advice.

Bad Ideas

Part of what makes it so easy to push investors toward bad ideas is that we believe secret ways to create wealth exist when, in fact, they don’t exist.  “We don’t like to admit it, but nobody knows anything about the future — not just you and me, but the so-called experts too.”

I’ve had the experience of getting people to agree that the future is unknown, and then they immediately ask what I think will happen with interest rates.  It’s hard to get people to really believe the future is unknown.  Ritholtz does an excellent job of going through some high-profile examples of the futility of forecasters.  Instead of searching for the right seer, he suggests having a “financial plan that is not dependent upon correctly guessing what will happen in the future.”  “Don’t predict what will happen, but rather, assess the range of possible outcomes — what could happen.”

So much of the information we see about investing is just noise.  Ian Cassel said “The maturation of every investor starts with absorbing almost everything and ends with filtering almost everything.”

It is freeing to admit we don’t know what will happen and to plan for a range of possible outcomes.  What too many people do is “Make predictions, then marry those forecasts.”  If they’re wrong, “This usually leads to catastrophic results.”

Bad Numbers

This part of the book starts with a good section on economic innumeracy that discusses denominator blindness, survivorship bias, mathematical models, and the fact that we respond better to anecdotes than data.

Part of what makes this book a pleasure to read is Ritholtz’s optimism.  Paul Volker once said “The only useful thing banks have invented in 20 years is the ATM,” but the author lists 20 useful financial innovations, including index funds, ETFs, low costs, fast trade clearing, and cash-sending apps.  The challenge for investors is to benefit from these innovations rather than lose money with them.

The author sees bull and bear markets as secular periods characterized by either high price-to-earnings (P/E) ratios or low P/E ratios.  I’m not sure how he thinks investors should use this information.  In my case, I use P/E levels to make modest formulaic adjustments to both my asset allocation and my expectations for future stock returns.

Sometimes people overestimate how much the news of the day will affect markets.  Some industries were devastated by Covid-19.  However, it turns out that these industries represent a small fraction of overall markets.  If in “mid-2020, the 30 most economically damaged industry categories were delisted, it would have shaved off just a few percentage points from the S&P 500.”

There is a winner-take-all tendency in many areas, including stocks.  “Just 1.3% of the public companies listed in the United States account for all the market gains during the last three decades.”  We can “find the best-performing stocks by buying them all” in an index fund.

“Simplicity beats complexity every time.  A portfolio of passive low-cost indexes should make up the core of your holdings.  If you want to do something more complicated, you need a compelling reason.”

Bad Behavior

“Bad behavior leads to bad investing outcomes.”  Ritholtz categorizes bad behaviour into ten areas, and he illustrates some of them in an amazing story about a billionaire family called the Belfers.  They lost money with Enron, Madoff, and then FTX!  “Has there ever been a greater, more unholy trifecta than this?”  Even billionaires make some terrible choices.

“If only we made better decisions, we would all be so much better off.”  If we could eliminate all investing mistakes for everyone, we might be better off on average, but there is a zero-sum aspect to investing mistakes.  Your loss is someone else’s gain.  The main overall benefit of eliminating all investing mistakes is that those employed exploiting such mistakes would move on to do something useful for society. Continue Reading…
Q&A with John De Goey

John De Goey, courtesy MoneyShow

The following is a question-and-answer session conducted via email with advisor John De Goey following his recent talk at the MoneyShow in Toronto, which we reported here.  Some of the questions and answers also appeared in my recent MoneySense Retired Money column here.

Jon Chevreau, Findependence Hub:  How defensive do you think low-volatility ETFs (i.e., BMO’s, iShares, Harvest) are?

John De Goey: Let’s say the market pulls back by 25%. If you can handle that, then you don’t need a low-volatility ETF. In short, low-volatility products are more defensive than market  (cap)-weighted products, but it all depends on how investors react and behave when things go south.

Chevreau Q2.) Most of those are overweight utilities, consumer staples and healthcare stocks. Do you advocate that investors do this themselves with sector ETFs?

De Goey – I generally don’t recommend buying utilities as a stand-alone product/strategy. That said, if you already own cap-weighted products and want to be more conservative, it would likely be more tax effective to simply add utilities rather than sell cap-weighted products in order to buy low-vol products. Same net result, but less tax on the way.

Jon Chevreau, courtesy MoneySense

Chevreau Q3.)  If U.S. stocks are so richly priced, do you advocate owning a Value U.S. ETF to compensate, or simply sell down some U.S. or and add more International/Canada? Or other factor funds?

De Goey – I recommend getting out of the U.S. entirely. If you cannot do that then, at the very least, I’m worried that there’s an AI bubble much like what we saw with .com a quarter-century ago.

Chevreau Q4.) What range of asset allocation do you recommend for retirees, especially those who are middle-of-the-road and risk-averse?

De Goey: I think all portfolios should have alternatives. Pension plans like CPP, OMERS and HOOP all have over 33% in alternatives. But for MOR retail investors, I’d opt for something like 20% alternatives, 30% income, and 50% equity.

Chevreau Q5.)  Can investors and especially retirees rely on global Asset Allocation ETFs to keep them out of too many over-valued U.S. stocks?

De Goey: I wouldn’t use the word ‘rely.’ Such products will soften the blow, but right now the U.S. represents almost 2/3 of global stock market capitalization. So, if all your stocks were in a single global ETF or mutual fund with a cap-weighted mandate, you’d have massive exposure to a massively over-valued market.

Chevreau Q6.)  What about annuitizing a portion of an RRSP/RRIF? Continue Reading…

Mark Seed on the 2% Retirement Rule

By Mark Seed, myownadvisor

Special to Financial Independence Hub

Well hello!

Welcome to some new Weekend Reading related to an article I read on not 4% rules, not 3% rules but the 2% retirement rule.

The 2% Retirement Rule

“The best retirement withdrawal strategy requires flexibility and course corrections depending on the market environment, inflation and your personal spending levels. No one actually follows through with this stuff like it shows on a spreadsheet.”

These are statements that really reasonated with me from Ben Carlson’s post entitled Why the 4% Rule is More Like the 2% Rule.

  • I desire flexibility related to our retirement income spending needs.
  • I want to use an approach that enables course corrections to happen easily.
  • I have never lived my life in a spreadsheet yet some tracking is necessary.

The 2% rule occurs when many retirees who even worry about the 4% rule constantly underspend from their portfolio from fear of outliving their money.

As Ben writes:

“There is a psychological hurdle that exists with some people because you worry about outliving your money, inflation, high healthcare costs, sequence of return risk or something coming out of left field.”

This also speaks to me.

It will be interesting to see how I combat these fears as my wife enters retirement next month and I consider retirement myself from current part-time work in 2026. Lack of a steady paycheque will be new territory to us.

Things we are considering for our retirement income spending as early retirees at least:

  1. Be flexible with our spending. If markets are good/positive, we’ll consider spending more. If markets are unfavourable, then we’ll spend a bit less. Spending a bit less means cutting back on travel plans.
  2. Keep a cash wedge at all times. Any money needed for spending in the next 1-2 years will be maintained in cash/cash equivalents. This way, when market corrections happen that I can’t see coming, we are ready to cover spending in advance.
  3. While we don’t budget (I recently wrote about that) we do track our spending and we’ll continue to do so. This will ensure we are spending money on things we value and/or are aligned to our values.

Retirement will be uncharted waters for us. My wife begins her journey next month. Our psychological and emotional hurdles when it comes to spending money without two steady paycheques will begin very soon: it will interesting to see and feel how we manage that.

I’ll keep you posted.

Other than 1, 2, 3 above, what other advice do you have for me? Words of wisdom from folks that have been there, done that?

More Weekend Reading – Related to the The 2% Retirement Rule

Ben’s post and my reflections of it remind me of this older but goodie post from Mr. Money Mustache about retirement income planning with a fixed chunk of money. Continue Reading…

Unlocking Overnight Returns for Covered Call ETFs with DayMAX™ ETFs


Image courtesy Hamilton ETFs

By Hamilton ETFs

(Sponsor Blog)

Overnight returns refer to the change in an asset’s price between the market’s closing level and its opening level the following morning. Even though stock exchanges are closed during these hours, the global financial system never truly sleeps.

Equity markets continue to move after the closing bell because of activity in futures markets, which trade almost 24 hours a day. These futures contracts track major indexes like the S&P 500 and Nasdaq 100 and respond instantly to news around the world as well as movements in global financial markets in Asia and Europe. When the North American markets open the next day, these changes are reflected in stock prices.

Why Overnight Returns matter

Overnight returns are an important source of long-term stock price appreciation that is often overlooked. In fact, studies including research from the Federal Reserve Bank of New York[1] show that over time, the majority  of stock market gains occurred overnight, not during the trading day. These moves are often driven by factors such as:

  • Company-specific news: Material information (read: “market moving”) such as earnings results, merger activity, and regulatory action is typically released after the close or before the open
  • Economic data: Reports like inflation and jobs numbers are often published before U.S. markets open
  • Global events: Political, policy, or economic news can move markets outside of trading hours

Importantly, these moves can be significant, and investors who are not invested or exposed overnight can miss out on a meaningful part of total returns.

Don’t Sleep on Overnight Returns

Overnight returns can be triggered by a single news announcement, creating sharp changes as trading begins. For example, on Sunday, May 11, 2025, the White House announced major progress on trade negotiations with China, including a 90-day truce. By the time U.S. markets opened the next morning, the S&P 500 had already jumped over +3%[2] vs. the previous night’s close. That entire move happened before investors could trade stocks during normal hours, and anyone not exposed/invested overnight missed it.

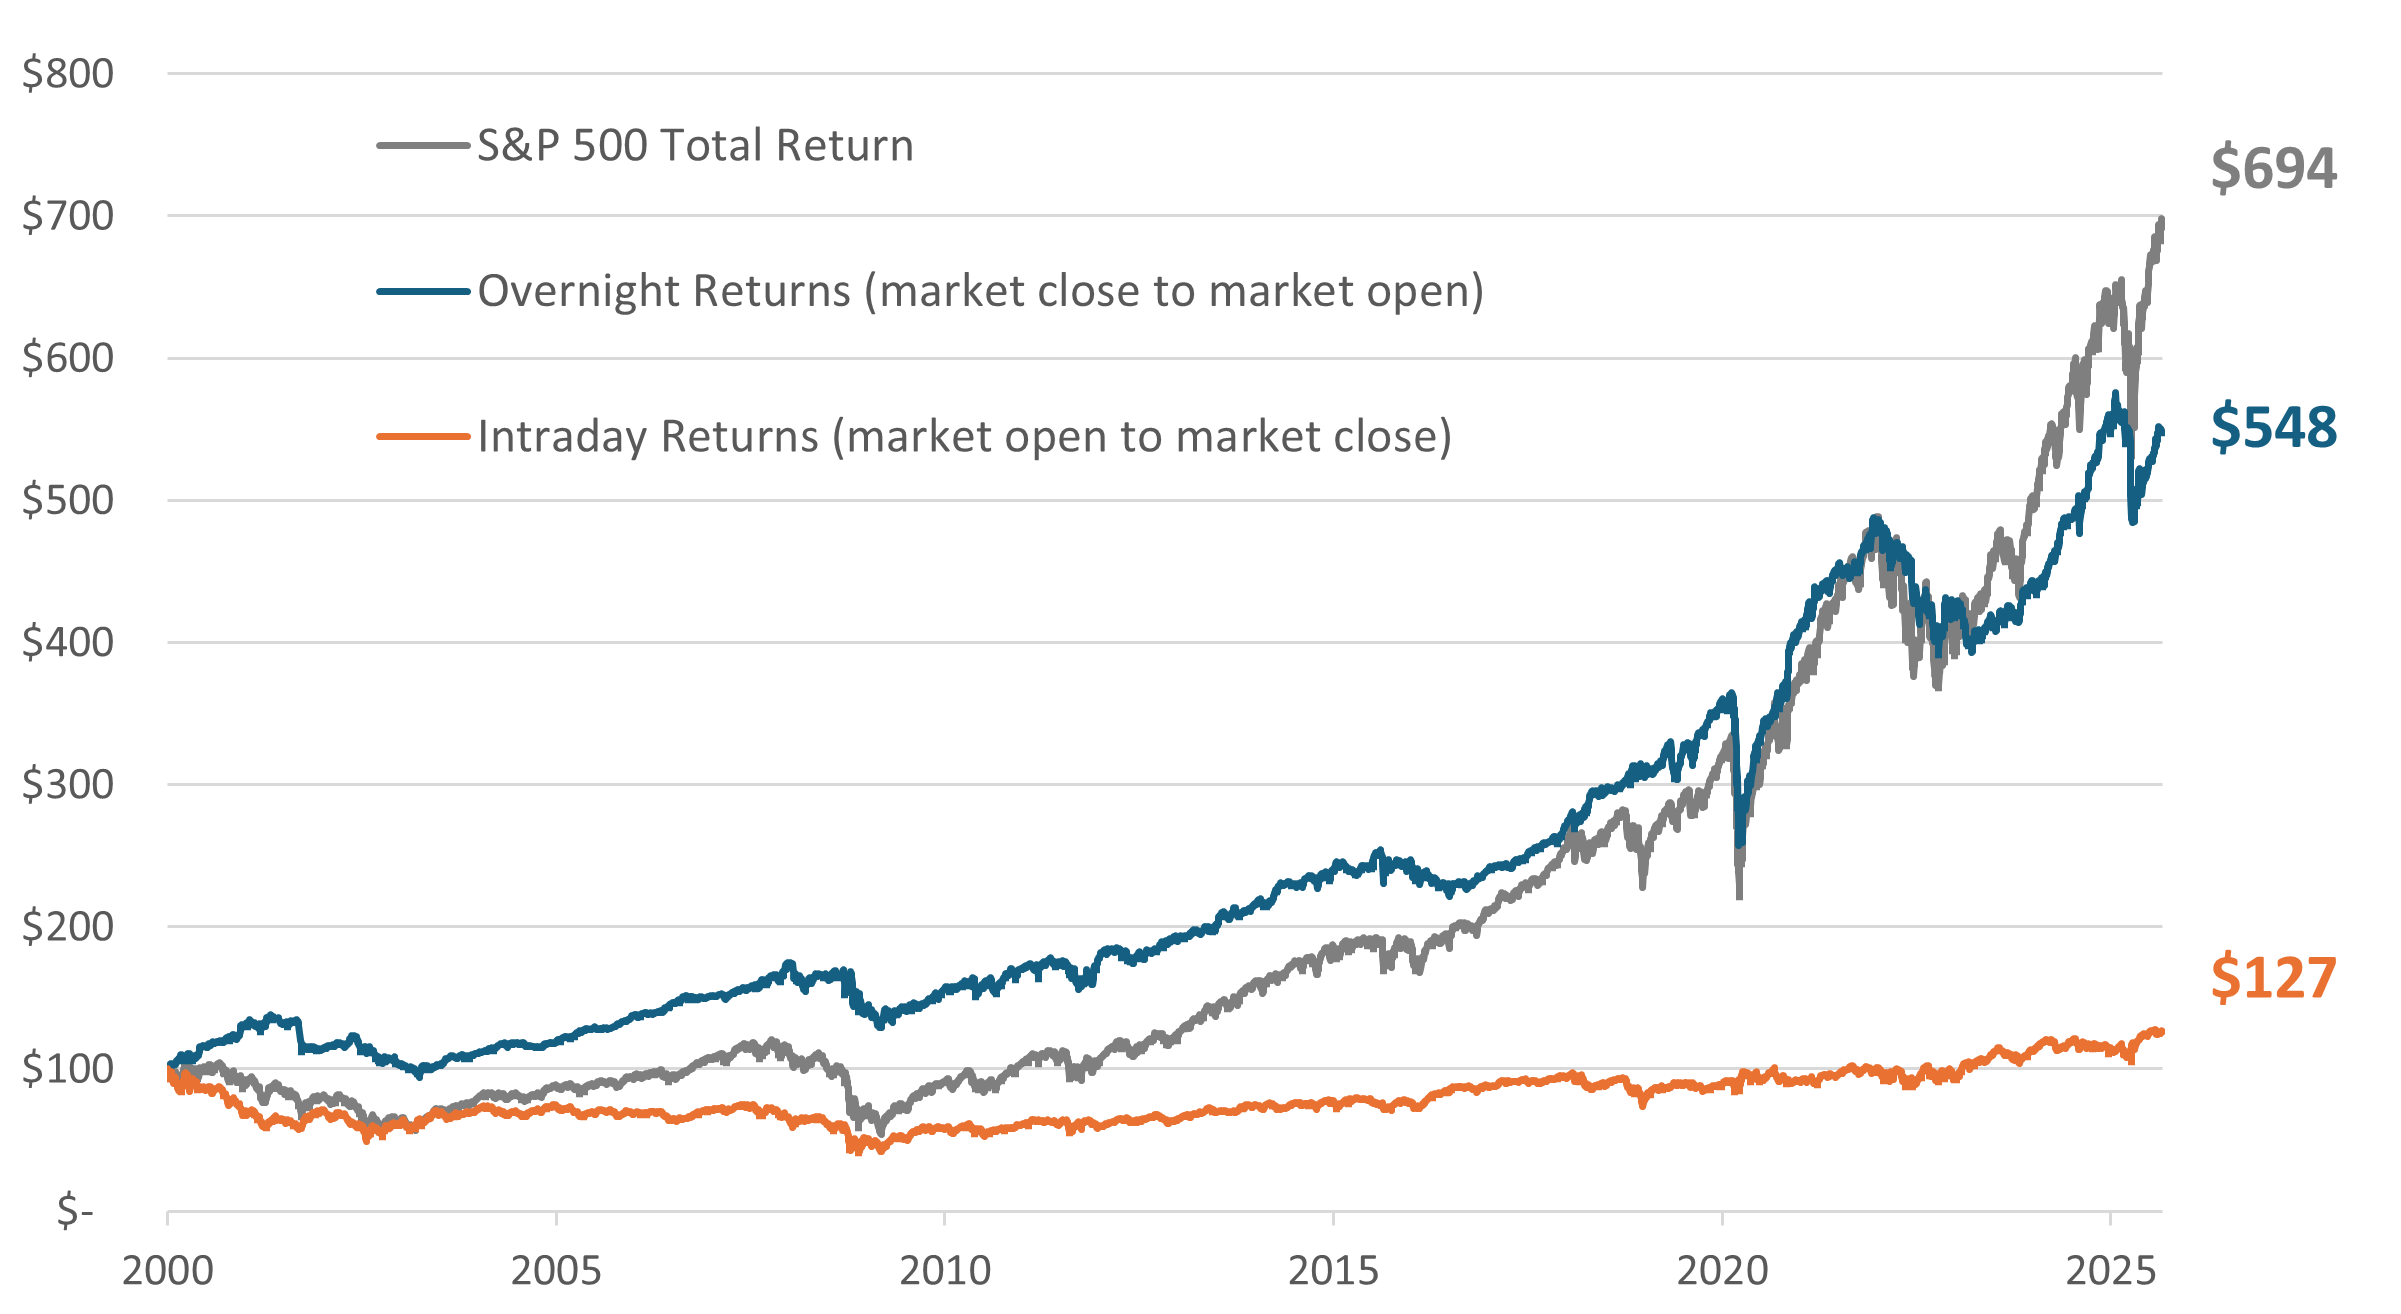
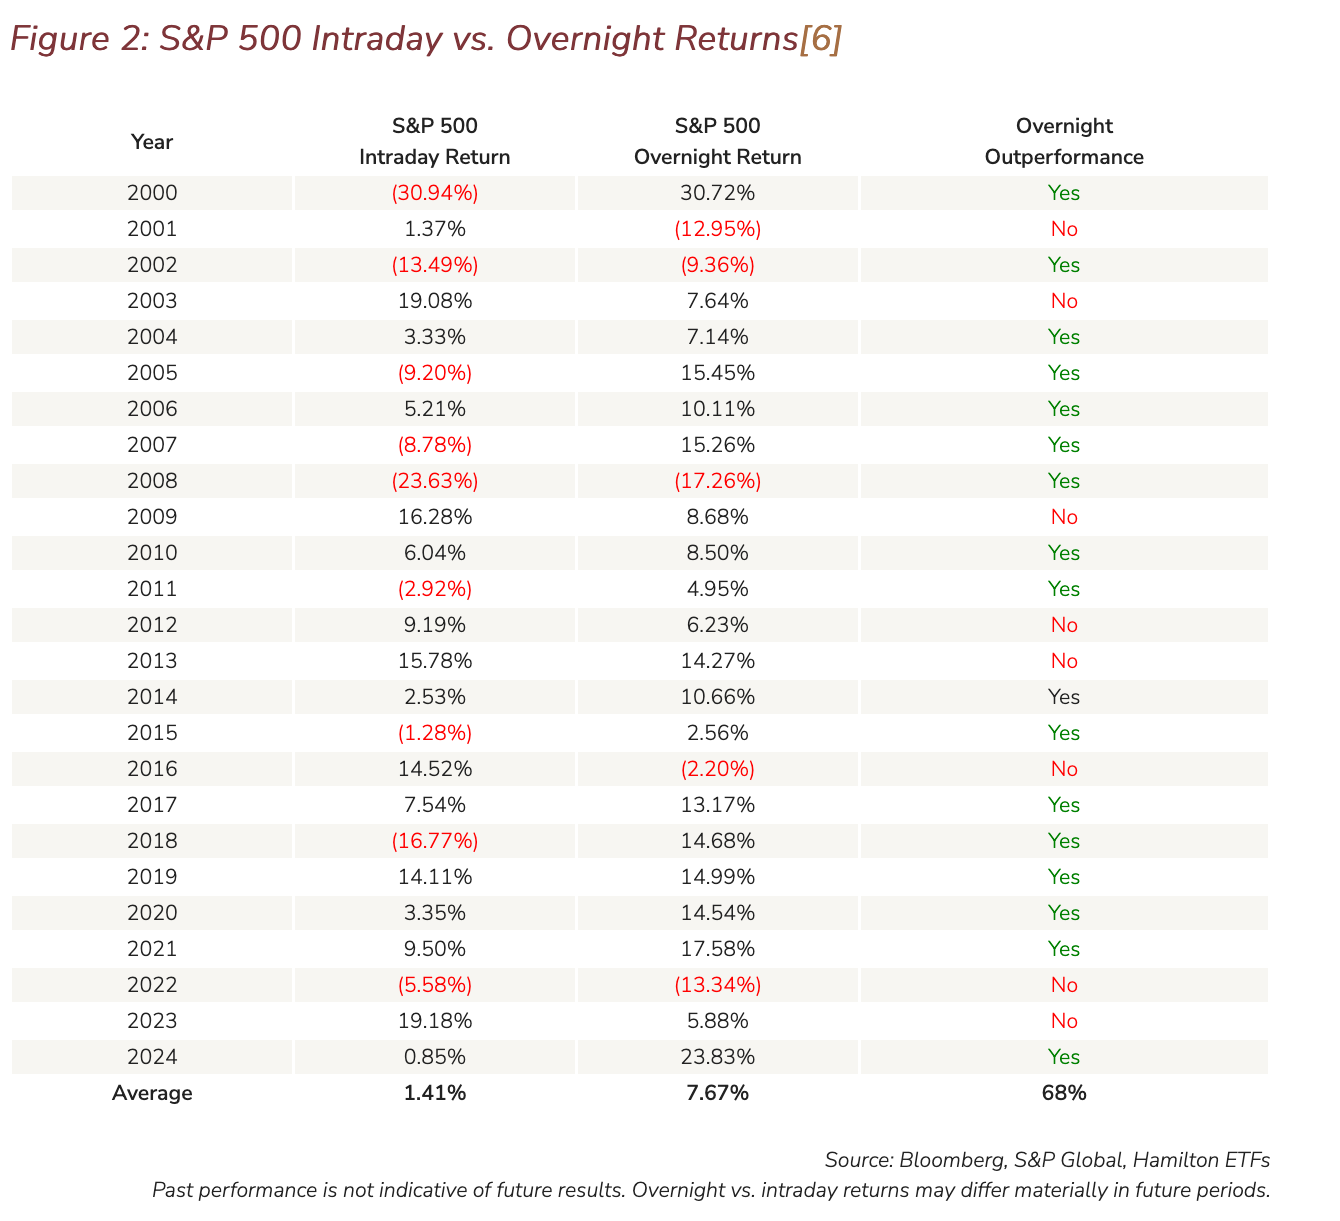
Looking at the bigger picture, overnight returns accounted for the majority of long-term market performance. Since 2000, the S&P 500 has delivered far stronger returns overnight than during the trading day. On average, annualized overnight returns were +7.67%, compared to just +1.41% during standard trading hours[3]. Put another way, a $100 investment in the S&P 500 held only during the day would have grown to about $127, while the same investment held only overnight would have grown to about $548 (Figure 1, 2).

Intraday vs. Overnight Returns[4]

As noted, overnight returns have historically accounted for the majority of positive market gains in the S&P 500. For vanilla equity investors, if they stayed invested overnight, they maintain that exposure. For a covered call ETF investor, the upside capture overnight can be limited by the call option. By selling call options each morning that expire at the same-day market’s close, DayMAX™ ETFs  only limit upside during regular trading hours, when the upside has historically been more limited, and they are fully exposed overnight, when there has historically been more money to be made (see charts below).

Figure 1: S&P 500 Intraday vs. Overnight Returns[5]

Source: Bloomberg, S&P Global, Hamilton ETFs
Past performance is not indicative of future results. Overnight vs. intraday returns may differ materially in future periods. 

Source: Bloomberg, S&P Global, Hamilton ETFs
Past performance is not indicative of future results. Overnight vs. intraday returns may differ materially in future periods.

DayMAX™ ETFs: Daily Options + Overnight Returns

DayMAX™ ETFs are built to generate frequent income while maintaining exposure to overnight returns. Unlike traditional covered call strategies that write options for weeks or months, DayMAX™ ETFs sell daily (specifically, zero-days-to expiration, or 0DTE) index call options each morning that expire at the market’s close. This structure means: Continue Reading…

Retired Money: Are pricey U.S. stock valuations a threat to new Retirees? Plus David Chilton on retiree market timing

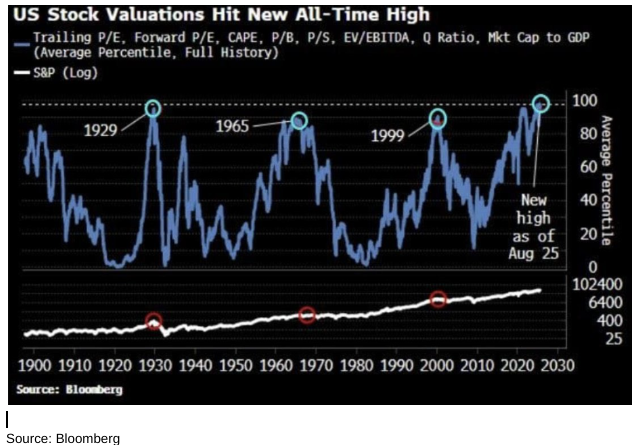
My latest MoneySense Retired Money column looks at the currently near record high valuations of U.S. stocks and the risks that may pose to those in the Retirement Risk Zone. Full column can be accessed by clicking on the highlighted headline: Why retirement planners are getting defensive. 

Retirement Club co-founder Dale Roberts recently posted a typical anxious link to a Globe & Mail column by Dr. Norman Rothery, (CFA) which suggested the current environment of Trump-inspired Tariffs and global Trade Wars, are causing plenty of anxiety for this group.

In the piece posted under Managing Risk in Retirement – and headlined With today’s market, investors close to retirement face precarious times – Rothery said investors on the cusp of retirement are “facing peril from a combination of the unusually lofty U.S. stock market and political uncertainty that’s disrupting world trade.”

U.S. stocks trading at “worrying levels”

The U.S. stock market is “trading at worrying levels,” based on several Value factors, Rothery said: the S&P 500 Index is “trading at a cyclically adjusted price-to-earnings ratio (developed by Robert Shiller) near 39, which is above its peak of 33 in 1929 and it is approaching its top of 44 in late 1999, based on monthly data. Similarly the index’s price-to-sales ratio is approaching its 1999 high. A broader composite measure that includes many different market factors indicates that the U.S. market’s valuation is at record levels. “

Rothery, who also publishes StingyInvestor.com, concluded that it’s “likely that the U.S. stock market will generate unusually poor average real returns over the next decade or so.” Unfortunately, the U.S. stock market now represents about 65% of the world’s market by market capitalization based on its weight in the MSCI All-Country World Index at the end of August. So if the U.S. market flops, “It’ll likely take the rest of the world with it – at least temporarily,” Rothery cautioned.

This could impact recent retirees just beginning to draw down portfolios, due to “sequence of returns risk.” That means that those in the so-called Retirement Risk Zone  who suffer early losses could down the road be in danger of outliving their savings. Rothery also reference the famous 4% Rule of financial planner and author William Bengen: the theory that investors in a 55/40/5 portfolio should be able to sustain retirement savings for 30 years provided the annual “SafeMax” withdrawal not exceed 4% a year (actually 4.7%) after adjusting for inflation. Bengen just released a new book titled A Richer Retirement: Supercharging the 4% Rule to Spend More and Enjoy More, which the Retired Money column plans to  review next month.

What recent Retirees can do to lower their risk

Retirement Club members anxiously posed questions on the related chat room about whether they should be moving to cash and bonds, gold or other alternatives to U.S. stocks. To this, Dale Roberts – who also runs his own Cutthecrapinvesting blog – warned against getting too defensive but agreed a move to a 70% fixed income/30% stocks allocation might work for some nervous early retirees. Personally, he has trimmed back on his US growth stock exposure and added to defensive ETF sectors like consumer staples, healthcare and utilities. He also mentioned a US equity ETF trading in Canadian dollars: XDU.T

Advisors and their clients suffer from Optimist bias

Advisor John De Goey came to a similar cautious stance in a recent (Sept 12) speech at the MoneyShow in Toronto, archived here on YouTube. Titled Bullshift and Misguided beliefs (see this recent Hub blog) De Goey expanded on his usual themes of advisor bullishness and complacent investors, also articulated in his book Bullshift. Continue Reading…