Tag Archives: Financial Independence

Of harness racing and asset allocation

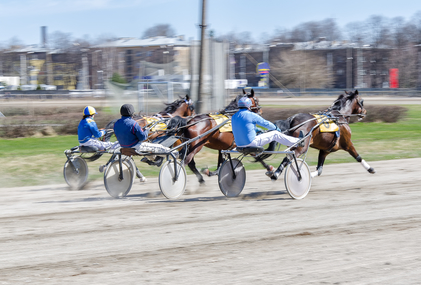
Harness racing. Racing horses harnessed to lightweight strollers.
Harness racing: go Horse #5!

Here’s my latest MoneySense blog, which bears the headline When dividend investing trumps a balanced portfolio.

That’s an accurate depiction of the content but here at the Hub we’re sticking with the more offbeat headline used above. Because this column really does begin with a true story about harness racing in Florida.

How can that possibly relate to asset allocation and dividend investing? Click the above link to find out, or the Hub’s version below. And yes, the happy winner depicted below clutching a winning ticket is my wife, Ruth Snowden.

She’s known in her industry by that name. When we got married more than a quarter century ago she was concerned I might take offence that she didn’t want to use my surname in business circles. My response won’t surprise those who know us: “Honey, you can call yourself whatever you want as long as you pay half the mortgage!”. Of course, the mortgage has long been paid off, consistent with the Hub’s philosophy that “the foundation of Financial Independence is a paid-for home.” Continue Reading…
Reflections From The Early Days Of Spending In Retirement, Part 3 — Taxes! 

patgass
Patricia Gass

By Patricia Gass, CPA

Special to the Financial Independence Hub

This week’s skill-testing question:

What’s The One Expense In Retirement That Most People Get The Least Satisfaction Out Of Spending?

Hint:

fireplaceI love a warm fire on a cold, snowy day. But that same fire, if not properly contained, can do  damage to anything in it’s way. Kind of like taxes.

Perhaps extreme to compare a roaring fire to taxes, but hear me out. Whatever goes into the fireplace (or to the government), you will never see (or spend) again.

Fortunately, much can be done with a little knowledge and planning. It’s useful to think of taxes as yet another, substantial retirement expense that needs to be managed.

Revisit/Understand Your Overall Financial Situation

At least 10 years before retirement, do some critical thinking about your finances.

Where will your retirement income and (cash flow) come from and when? What is the breakdown between “tax-paid” and “tax-deferred” money? Will your retirement cash flow be enough to meet your needs (or too much … a nice problem to have!)? How likely are you to receive an inheritance (or other money) that could push you into a higher tax bracket? Would it make sense to retire early and withdraw some funds sooner at a lower tax rate?

Know (And Plan For) Your Tax Rate Continue Reading…

Let’s give the word Retirement an early Retirement

Here’s a piece I did recently for Money Magazine, entitled Let’s retire the word Retirement. For the convenience of one-stop shopping and archival purposes, I’ve also reproduced the piece below, with a few changes and links added since it was originally published in the current issue of the magazine.

By Jonathan Chevreau

This magazine, like its sister web site and its competitors, is devoted to the topic of money. That’s an obvious statement but stay with me.

We all need money to live, both in the present and the future. This basic fact has created the entire financial industry, dedicated to the notion of saving for a rainy day so we’ll have enough money both for today’s needs as well as tomorrow’s. And the week after, the year after that and so on, bringing us ultimately to the concept of Retirement.

Retirement is the greatest marketing bonanza ever conceived for the financial industry. If a mutual fund company, bank, insurance firm or ETF maker runs an ad, what is the major concept behind its marketing?

senior couple of old man and woman sitting on the beach watching
How Advertising portrays Retirement

Typically, it features a mature couple frolicking on a beach or golf course, care-free, active, smiling, still in love and doing nothing that resembles work.

I don’t know when work acquired such a bad reputation but I’d venture  to say that in Canada, this phenomenon started to gather steam when London Life popularized its Freedom 55 campaign. Continue Reading…

TFSA makes progressive retirement system slightly less so: Malcolm Hamilton


Here’s my latest MoneySense blog, a followup to all the media coverage on two controversial reports that called for the Tories to renege on its promise to double TFSA contribution room once the federal books are balanced. The blog, entitled Leave the TFSA Alone, is based on an email exchange with retired actuary Malcolm Hamilton, who led off the MoneySense Retire Rich event last November. Speaking of which, another is scheduled this April.

By Jonathan Chevreau

Hamilton_Chevreau_3_3221
Malcolm Hamilton (L) & Jon Chevreau, 2012, MoneySense.ca

One of Canada’s better-known retirement experts, Malcolm Hamilton, doesn’t think limits need to be doubled on Tax-Free Savings Accounts but his reason for saying so is not the fiscal consequences for Ottawa. “I just think that a larger TFSA will ultimately threaten RRSPs and that the existing TFSA is sufficiently large for most Canadians.”

In an email exchange, Hamilton said he worries about the “apparently coincidental release of two reports highly critical of the TFSA in an election year.” Given its close affiliation with the NDP party, the critique of TFSAs is to be expected from the Broadbent Institute, he said.

Feds backing away from TFSA?

But the other report, from the Parliamentary Budget Officer (PBO) is more of a concern, since “it may signal that the federal government is backing away from the TFSA.”

Continue Reading…

At age 62, couple celebrating 25 years of Financial Independence

billy-akaisha-puerto-escondido
Billy and Akaisha Kaderli

By Billy and Akaisha Kaderli,

Special to the Financial Independence Hub

At the age of 62, we are beginning our 25th year of financial independence. That is quite a feat!

From the beaches on Nevis, West Indies, to the shores of Phuket, Thailand we have travelled extensively through these decades, and what a ride it’s been!

Young and strong in those early years, we were willing and able to tackle just about anything. Now we tend to be a bit more cautious but we’re not letting up. We still climb into the backs of pickup trucks, ride the chicken buses and soak in volcanic hot pools. The time has passed quickly from when we were the youngest, grayless couple in a group of retirees, to now where we blend in with the retiree crowd.

Still, no one can take away the dance we danced and we are filled with gratitude for all the miles and smiles. Continue Reading…