Tag Archives: Financial Independence

8 things to know before applying for Life Insurance

What should someone know before applying for life insurance?

To help you prepare for life insurance application processes, we asked insurance experts and business leaders this question for their best advice. From researching the required health tests to budgeting monthly costs, there are several tips that may help you when applying for life insurance.

Here are eight things to know before applying for life insurance:

● Know What Test Might be Done
● Clarify Term Life vs. Whole Life
● Determine Your Why
● Gather Your Paperwork Early
● Check Your Health Prior
● Assess Length of Policy
● Budget Monthly Costs
● Figure Out Future Needs

Know What Tests Might be Done

In the past, my life insurance companies would test for marijuana and reject applications for applicants who tested positive for marijuana use. However, since marijuana is legal in several states, but still illegal at the federal level, it is wise to work with an insurance expert to help work you through the process so you can find the right policy at the best rates to meet your needs. — Chris Abrams, Marcan Insurance

Clarify Term Life vs Whole Life Insurance

Learn the difference between term life insurance and whole life insurance so you can select the option that works best for your situation and budget. Term life insurance is an agreement between you and your insurance provider that lasts between 10-30 years. This type of insurance does not usually require a health exam. On the other hand, whole life insurance is truly meant to last your lifetime and carries additional benefits. However, it is also more costly. Understanding how these policies differ can help you make an educated decision about your life insurance. — Brian Greenberg, Insurist

Determine Your Why

The reasons why you are getting life insurance factor into the coverage amount and type of coverage you’ll receive. This can also help motivate you to stay consistent with payments. Most people who have families that rely heavily or solely on them for financial support and stability might opt to get sufficient life insurance coverage in the event of an unexpected death. Depending on the amount and type of life insurance, you provide an income replacement for your family in your absence. –– Rronniba Pemberton, Markitors

Gather Your Paperwork Early

Before applying for life insurance, it’s important to know what kind of personal information you’ll need to give the company. Some companies require detailed medical records while others just require simple information such as your name, date of birth, place of residence, and social security number. Prepare documents accordingly to ensure there won’t be any surprises along the way. — Tim Mitchum, WinPro Pet

Check Your Health Prior

Before applying for life insurance, you should be aware of your health. If you are rejected for life insurance, you could be affected down the road. You could have trouble getting life insurance from another company. Your credit score could even be lowered. The cost of life insurance could be raised out of your reach due to poor health. Learn if you have a preexisting condition. You can be denied life insurance if you have preexisting conditions. Check on the status of your own health condition before asking a life insurance examiner to look at you. — Janice Wald, Mostly Blogging Academy
Continue Reading…

Why the 4% Rule doesn’t work for FIRE/Early Retirement


By Mark and Joe

Special to the Financial Independence Hub

The 4% rule is a common rule of thumb in many retirement planning circles, including the Financial Independence, Retire Early (FIRE) community in particular.

What does the 4% rule actually mean?

Should the 4% rule be used for any FIRE-seeker?

Does the 4% rule really matter to retirement planning at all?

Read on to find out our take, including what rules of thumb (if any) we’re using at Cashflows & Portfolios for our early retirement dreams.

The 4% rule is really a starting point for a safe withdrawal rate

Unlike 2 + 2 = 4, the 4% rule is not really a universal truth for any retirement plan at all.

It is, however, in our opinion, a great starting point to understand the impacts of asset decumulation, related to inflation, over time.

As you’ll read more about in the sections below, the 4% rule is fraught with many problems. None more so than for an early retiree or FIRE-seeker. In some cases, for the FIRE community, we believe the 4% rule should no longer be used at all.

Are any financial rules really rules?

Backing up, here is the source for the 4% rule.

The article from 1994!

4% rule

Despite the geeky photo, by all accounts, Bill Bengen was one heckuva guy and a smart guy as well!

Potentially no other retirement planning rule of thumb has received more attention over the last 25-30 years than Bengen’s publication about the 4% rule. This publication in 1994 has triggered a new generation of devotees and arm-chair financial planners that are using this quick-math as a way to cement some retirement dreams. We believe that is a mistake for a few reasons.

First, let’s unpack what the 4% rule really means.

What does the 4% rule actually mean?

From the study:

“In Figures 1 (a)-l(d), a series of graphs illustrates the historical performance of portfolios consisting of 50-percent intermediate-term Treasury notes and 50-percent common stocks (an arbitrary asset allocation chosen for purposes of illustration). I have quantified portfolio performance in terms of “portfolio longevity”: how long the portfolio will last before all its investments have been exhausted by
withdrawals. This is an intuitive approach that is easy to explain to my clients, whose primary goal is making it through retirement without exhausting their funds, and whose secondary goal is accumulating wealth for their heirs.”

Unpacking this further, for those that do not want to read the entire study, here is something more succinct from Bengen:

Assuming a minimum requirement of 30 years of portfolio longevity, a first-year withdrawal of 4 percent, followed by inflation-adjusted withdrawals in subsequent years, should be safe.


“Should be safe”.

Again, the theory is one thing. Reality is something different and the financial future is always subject to change. Furthermore, if you’re blindly following this formula without considering whether it’s right for your situation, let alone putting in some guardrail approach to monitor your portfolio value at various checkpoints, you could end up either running out of money prematurely or being left with a huge financial surplus that you could have spent during your retirement. We’ll prove that point in a bit from another leading author.

Should the 4% rule be used for any FIRE-seeker?

Probably not. For many reasons.

Recently, Vanguard published an outstanding article about the need to revise any thinking about the 4% rule for the FIRE movement – a driver for this post.

Although the 4% rule remains a decent rule of thumb we believe most FIRE-seekers should heed the cautions in the Vanguard post. Here are some of our thoughts based on the article’s contents.

  • Caution #1 – FIRE-seekers should not rely on past performance for future returns

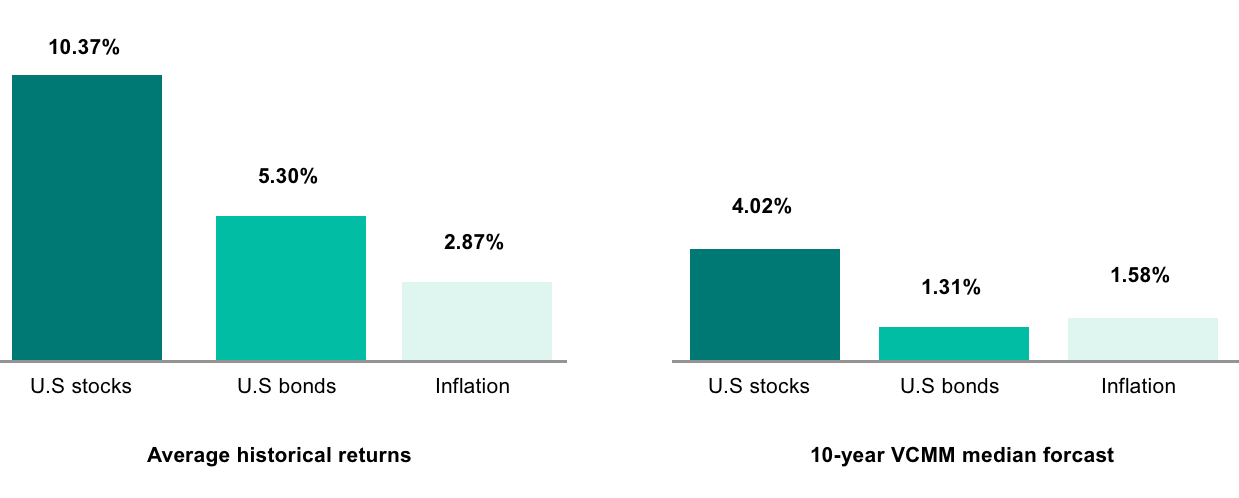
We agree. In looking at this Vanguard set of assumptions below, and based on our own personal investing experiences, we believe historical returns should not be used to guarantee any future results.


Source: Vanguard article – Fueling the FIRE movement

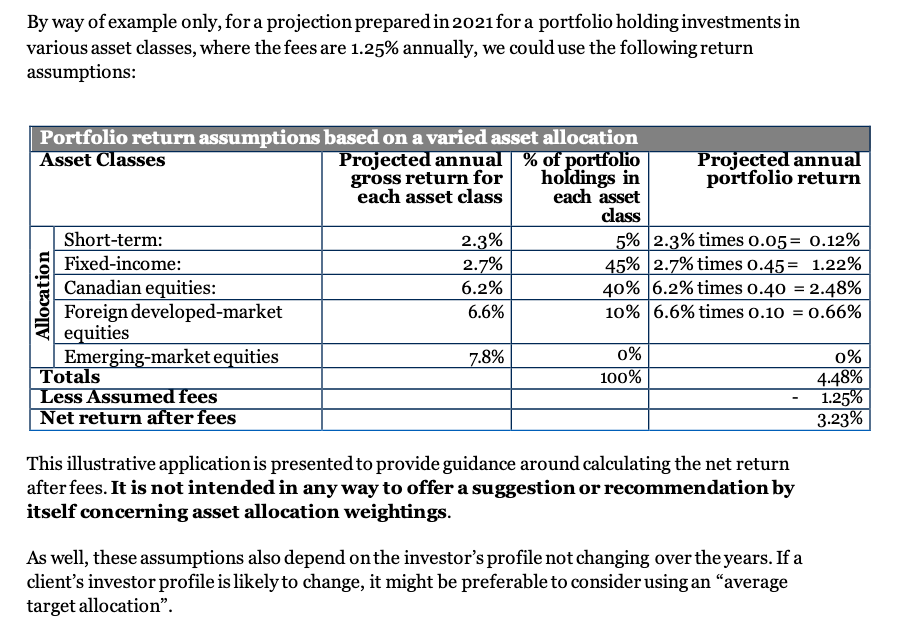
While the FP Canada Standards Council doesn’t have a multi-year (10-year) return model in mind, they did highlight in their latest projection assumption guidelines that going forward, investor returns may not be as juicy as in years past.


Source: FP Canada Standards Council.

This means for any historical studies, while interesting, may not be a great predictor of any future outcomes.

  • Caution #2 – The FIRE-seeking time horizon is longer

Bengen noted in his 1994 study:

“Therefore, I counsel my clients to withdraw at no more than a four-percent rate during the early years of retirement, especially if they retire early (age 60 or younger). Assuming they have normal life expectancies, they should live at least 25-30 years. If they wish to leave some wealth to their heirs, their expected “portfolio lives” should be some longer than that. “

Bengen goes on to say:

“If the client expects to live another 30 years, I point out that the chart shows 31 scenario years when he would outlive his assets, and only 20 which would have been adequate for his purposes (as we shall see later, a different asset allocation would improve this, but it would still be uncomfortable, in my opinion).
This means he has less than a 40-percent chance to successfully negotiate retirement–not very good odds.”

To paraphrase, Bengen’s study was relevant to 30 years in retirement. Not 35 years. Not 40 years and certainly not 50 years like some FIRE-seekers may need if they plan to retire at age 40 and live to age 90 (or beyond).

This is simply a huge reminder that your time horizon is a critical factor when it comes to retirement planning.

  • Caution #3 – FIRE-seekers may need to live with more stocks

Bengen’s 1994 study was based on the following:

“Note that my conclusions above were based on the assumption that the client continually rebalanced a portfolio of 50-percent common stocks and 50-percent intermediate-term Treasuries.” Continue Reading…

Letting go can lead us to Opportunity and Freedom

Photo by Sebastian Staines on Unsplash

By Akaisha Kaderli, RetireEarlyLifestyle.com

Special to the Financial Independence Hub

Often, we have the idea that letting go means the loss of something valued. This implies that there might be grief and pain involved.

Out of fear we envision ourselves in some barren emotional wilderness, with nothing around that is familiar so there has to be that dreaded chaos, right?

 And who wants that?

But what if letting go leads us to brilliance? To our own personal freedom of expression? What if this is Life’s way of steering our personal growth in a manner where we display our best talents?

Letting go could mean opening up.

Examples

 Art/music

Have you ever heard a musician or singer who is technically perfect: but there seems to be no soul? No felt connection to the audience?

Yes, all the notes are there and in the right place, but … something is missing.

There is no grab at my heart. I could just as well be chopping carrots in the kitchen for soup. It’s just routine, and maybe I should have bought a bag of frozen carrots instead.I always know when I hear someone “Who’s got it.” My eyes well up and I can’t reign it in. That’s my validation signature.

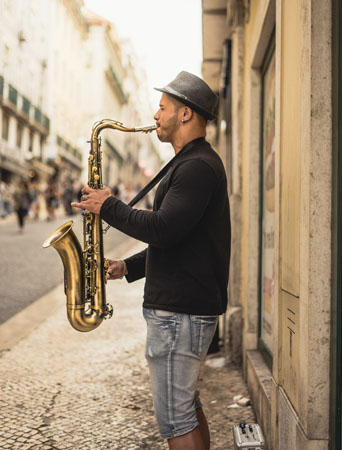
Photo by Daniel Angele on Unsplash

Chills on my arms, my eyes are glued to the performer and I am transported. The artist has whisked me away, and I want to go.

It could be a jazz singer who scats, a sax player having a riff or Billy Joel hitting the high notes for Christy Lee.

They let go and have entered “The Zone.”

Sports

Ok, here’s another example.

We have all seen outfielders throw their bodies at a fly ball just to catch that thing. Or a basketball player speed down a court and ram a ball into a basket. Ballerinas, ice skaters, skateboarders spin incomprehensibly – how can a physical body DO that?

Maybe as a skier you have caught air and you know that sensation of flight for yourself.

That’s my point.

To let go, is to leave the ground and enter genius territory.

Fear and contraction

When we begin to learn something new – cooking, Latin dancing, painting on canvas, surfing – there are basics. We learn the techniques, the rules, the boundaries. And then to develop proficiency, we leave them behind. Continue Reading…

Is everyone thinking of Retiring?


By Dale Roberts, Cutthecrap investing

Special to the Financial Independence Hub

It’s just a coincidence perhaps. But much of my blog and reads for the week research landed on that retirement theme. Everyone’s thinking of retiring or writing about retirement. And why not? That is a big end goal for most of us; some form of financial freedom. This Sunday Reads post offers a nice slice of retirement thinking, from the emotional to the money side of things. And of course, there’s some non-retirement ‘stuff’ in here as well.

This is a very good topic and post on My Own Advisor – the emotional side of retirement. In fact on this site I wrote an article that offered that waiting for your spouse was the hardest part of retirement.

Mark offers up on that period after the retirement honeymoon stage (after year one) …

At this point in retirement, the honeymoon is over and potentially it isn’t as enjoyable for some as they may thought.

Maybe some folks go back to work – as part of FIWOOT [Financial Independence: Work on own Terms]. There are only so many rounds of golf you can play …

I’ve read feelings of disenchantment can set in for some. Even depression. That’s certainly something I wish to avoid. By maintaining some form of work into my routine (may or may not be daily), it is my hope that I can stay active (socially, physically, cognitively) to support my health in early retirement and far beyond.

We certainly have to take greater care when we design our life in retirement. We need to be busy and we have to have purpose – from my life experience and from many studies. Having the money to retire in some form is just the half of it, or less.

The waiting is the hardest part

In my post link above, I touched on my first taste of semi-retirement experienced alone. My wife still works and will likely work for a a few more years. I also took off down east to be with my daughter as I launched this blog …

That said, I got a good taste of that ‘waiting’. And as Tom Petty (RIP) sang ‘The Waiting Is The Hardest Part’. While I have a very generous amount of loner in me I was surprised at how uncomfortable a feeling that was – that working alone and being alone for many hours on end. I couldn’t wait for my daughter to finish work and head up to the cottage for dinner and a walk along the beach.

I may have got a taste of what if feels like to make that transition.

The Boomers Retire

On the retirement front Jonathan Chevreau takes a look at a new edition of The Boomers Retire. The book is co-authored by Alexandra Macqueen, a Certified Financial Planner who co-authored Pensionize Your Nest Egg with famed finance professor Moshe Milvesky. David Field is an investment advisor and financial planner and co-creator of the CPP Calculator.

From Jonathan’s post on MoneySense …

“That’s just responding to the reality of retirement income planning for the growing numbers of the ‘pensionless’,” Macqueen says. “If you don’t have lifetime income, you’ll need to create it or take your chances. Whatever you decide, here’s a collection of the relevant facts, principles and issues you’ll need to take into consideration when you’re making your plan.”

While the book is written for advisors and planners, it is also a good read for the rest of us offers Jon.

Of course Alexandra is no stranger to this site. A retirement and pension expert Alexandra penned one of the most read (and most important) posts on this site.

Must read: Defined benefit pension planning. Bad advice could cost you your retirement.

And the Maple Money Podcast is on point this week as well with how to design your retirement lifestyle, with Mike Drak. Mr. Drak is a co-author of retirement heaven or hell, which will you choose? Continue Reading…

7 things you can do now to have a Debt-free Life

By Emily Roberts

For the Financial Independence Hub

Living debt-free might seem like a distant pipe dream to many, and that’s unfortunate. Being crippled with debt is difficult, and even more so when you feel like the situation is hopeless. The reality is that most people who have large amounts of debt could be making simple steps every day to turn their situation around. The issue for many is knowing where to start. Let’s take a look at what you can do today to get on the road to a debt-free life.

Take a long hard look at your Financial Situation

The first thing you have to do is know exactly how much debt you have. This will allow you to get a clear assessment of your finances and start working on repaying them. Not only that, but there could be cases where your situation might not be as bad as you thought. For instance, did you know that entries on your credit report have to be removed after a certain period? This means that some of the debt that you thought you had may have been expunged from your report a long time ago. This is why you need to keep a close eye on your credit report and get your annual statutory copy from the one of the three major credit reporting agencies. Once you know exactly what you owe, you can build a plan.

Call your Creditors

The next thing you have to do is get in touch with your creditors and work on a plan. There are some cases where you can work with a professional who will help consolidate all of your debt and have you pay a fixed sum per month. This can be a good option in some cases, but you don’t necessarily have to hire someone. Calling your creditors and speaking with them directly could help you shave off a few dollars of your debt. Also note that the more you can pay upfront, the more they will be willing to lower the amount of money you owe. Try to get them to report the payment to the credit reporting agencies in writing as well so it can be reflected on your credit score.

Use your Credit Cards wisely

If you have multiple credit cards, we would suggest that you start paying them off one by one. Tuck away the one with the highest balance and commit to paying it in full. Set up automatic payments if you have to. This will allow you to both reduce your overall debt and significantly improve your credit score by lowering your credit utilization ratio.

You then have to use your other cards wisely. A lot of people believe the myth that paying the minimum is something credit card companies will reward, but that’s complete hearsay. In reality, companies love people who use credit responsibly, and one of the best ways to do that is to use as little of your credit as possible. So, if you want to be viewed favorably by creditors, aim to keep your total utilization ratio under 30%.

If you want help with credit card debt and feel like you don’t have the discipline to pay them off on your own, we suggest you check out Tally. Their app will allow you to manage your credit cards all in one place and could even help you save on interest if you qualify for their low-interest line of credit. They will help you pay your cards automatically through an easy-to-understand interface, ensuring you don’t have to deal with a late fee ever again.

Know what you’re signing up for

Very few people take the time to read the fine print when they get a credit card and more people should. One piece of research reviewed credit card agreements for clarity and found that the majority of people surveyed could not understand them. That’s a big problem when considering that credit card agreements can include provisions that will allow them to change the interest rate at will. Continue Reading…