Tag Archives: Financial Independence

There’s more to Retirement than Financial Planning

The retirement industry is starting to wake up to the fact that just because a client has achieved a certain level of retirement savings doesn’t mean that they will automatically enjoy a happy retirement.

Life just doesn’t work that way and the truth is that financial planning fails without lifestyle planning: you need to have a good handle on what you are actually saving for and why.

Our level of happiness is not determined by how much money we have; rather, it is how we choose to live our lives. In our new transition guide we have compiled a list of key attributes that if focused on will help you live longer, healthier and happier lives. By focusing on these attributes you will be well on your way to a happy and fulfilling life.

Today I would like to share some thoughts I have on one of these attributes, which is our relationship with time.

Time: Your most precious resource

“Don’t say you don’t have enough time. You have exactly the same number of hours per day that were given to Helen Keller, Pasteur, Michelangelo, Mother Teresa, Leonardo de Vinci, Thomas Jefferson, and Albert Einstein.” – H. Jackson Brown

Visiting my mother at the nursing home always reminds me that I’m getting old and every day is bringing me closer to the end. It is not a negative thought; rather, it’s an important reminder to focus and use my remaining time on this planet wisely on the things that really matter. Rushing around stressed out because I’m wasting my time is a major happiness killer for me. Watching my mother I often wonder if I am living my “why,” the best I can? Can I do better? Am I doing the best for my family?  For my friends? Am I making the world a little better?

Best Before Date

Today I’m working hard at getting into shape. My time investment is a priority of mine as it will increase the odds of me living longer, and also help push back my “best before date” increasing the amount of quality time I have at my disposal.

I view “quality time” as the period of my life when I am healthy enough to do the things I love:  golfing, fishing, traveling etc. Once you pass the “best before date” and have lost your health it really doesn’t matter how much money or time you have left because you will not be healthy enough to spend it. That’s just the way it is.

Black Swan Events
Continue Reading…

Benefits of hiring a “Discretionary” Portfolio Manager

Canadian investors have been following a variety of recent debates about the structure of the advisor/client relationship. I’m going to cut to the chase quickly.

If you seek core qualities and competencies from your investment professional, such as the following list, you need to conduct some research. Your mission is to find a way to hire a “discretionary” portfolio manager (DPM) for your ongoing wealth management needs.

Continue Reading…

Dear Generation X: Here’s how to fix your Finances

But let’s skip the scaremongering and over-generalizations and get to some common sense advice.

How do you balance paying off debt, saving, and investing with the everyday costs of supporting a family? Let’s start by setting up a simple plan for each of these categories to ensure that you are on the right financial path. Here’s how to fix Generation X finances:

Treat consumer debt like a financial sin

You can’t move the needle forward financially if you’re constantly spending more than you earn. But when your mortgage payment, car payment(s), daycare costs, groceries, and gas take up your entire available budget then you have no wiggle room to plan for unexpected costs.

Not only that, when the “I deserve this” moments come up and you want to treat yourself or your family to dinner, a movie night, or a vacation you end up going into debt (just this one time) to make ends meet.

Start with a list of everything you currently spend over a period of three months. Where does all your money go? Find a way to slash expenses so that you’re no longer going into debt just to get through the month.

Make it a rule: No new debt this year

Now it’s time to tackle your current debt, whether that’s in the form of a lingering line of credit or (gasp!) a high-interest credit card. If it’s the latter, put all savings and extra spending on hold and throw every extra dollar at that debt until it’s paid off.
Continue Reading…

What the first week of Retirement is really like

By Fritz Gilbert, RetirementManifesto.com

Special to the Financial Independence Hub

I have no idea why I’m fascinated by the “First Week Of Retirement,” and I’m curious if others also wonder about it? I suspect many do and dedicate this post to those of you who wonder what the first week of retirement is really like.

Now that I’m living the first week of retirement, how would I describe it? Is it what I thought it’d be, or is it different? Is it a big deal, or just another week? Is it weird, or normal? Is it scary, or exciting?

Yes to all of that. And no to all of that.

What does Retirement taste like?

Have you ever tried to explain what something tastes like? Let’s go with chocolate, as an example. How would you describe it? What words would you use? Describing the first week of retirement is like describing the taste of chocolate. It’s really good, but it’s hard to describe.

Yeah, the first week of retirement is alot like that.

It’s good, but I can’t think of the right words to describe it. Regardless, today we’re going to try.

What the first week of Retirement is really like

Is It Like Taking A Vacation?

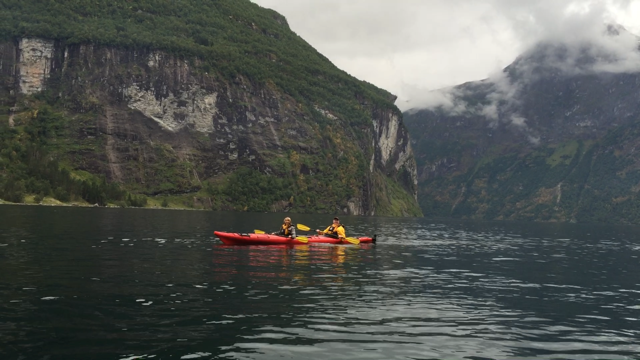
A Vacation In Norway. Is it like that?

As I write these words, I’m 5 days into my retirement (a true rookie). Is the first week of retirement like being on vacation? On one hand, kinda sorta, but that falls far short of describing the reality. It’s similar in that you’re off work for a few days, but it’s very, very different in the knowledge that You’re Never Going Back To Work.is


A Vacation that never ends will always feel different than a two-week vacation. Full Stop. So, imagine the first half of your vacation, where you’re all pumped up and excited. But you know it lasts for the rest of your life. Yeah, it’s more like that.

Only different.

I love swimming in my local mountain lake.

Is it like Saturday every day?

With less than a week of retirement under my belt, the “Saturday” analogy seems to be a better description of what the first week of retirement is really like. Like the Saturday’s you’ve experienced for decades, you’re free to do what you want to do. You’re ok letting your email go unchecked for a day or two. You can stay up later, you can sleep in.

You’ve got time to head up to the lake for that swim.

But it’s different because you know that there’s no Monday looming on the horizon.

What’s chocolate taste like?

Yeah, it’s hard to describe.

Is it scary, or exciting?

I had a friend ask me if I was “scared.” I answered that I was 98% excited and 2% scared. Sure, there’s some apprehension, but it’s a really small piece of my mindset in Week 1. At this stage of the game, I’m just learning my way around this thing called retirement, and enjoying the sensation of the very first Tastes Of Freedom I’ve worked so hard to earn. It’s only scary if you make it scary.

I know we’ll travel through many phases during our retirement journey, and I’m sure some will be more “scary” than others. We’re planning to take it all in stride. One day at a time, with some thoughts on where we want this thing to lead while leaving some freedom to enjoy the Serendipity of the thing.
You can choose what you want your retirement to be. Don’t choose scary. Life’s too short.

Choose the attitude with which you’ll live your life.

I’m choosing excited (and yeah, just a wee bit scared). Continue Reading…

Why Sean Cooper quit his full-time job after 8 years

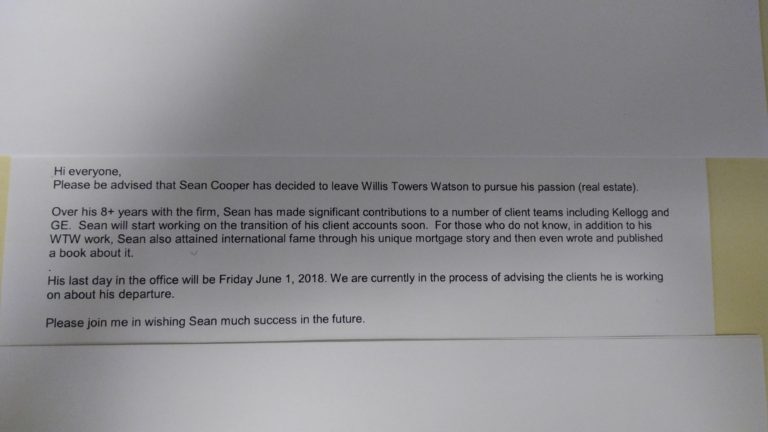
What a thoughtful goodbye email. Gosh, it’s hard to keep a secret! I guess everyone knows about my mortgage burning story, even my colleagues at work!


By Sean Cooper

Special to the Financial Independence Hub

If you follow me on Instagram, you may have already heard the big news. After 8 years, I’m quitting my full-time job at the pension consulting firm. I gave my employer plenty of notice. I handed in my resignation 2 months ahead of time. June 1st will be my last day in the office. To celebrate this big career milestone, I’ve booked a weeklong trip to New York City and Boston.

I always planned to quit my full-time job. I just didn’t think it would happen so soon. I’m at a crossroads in my life. I’m 33 years old and not getting any younger. It’s time to make some tough “adult” decisions. I can either take the easy road and keep working for a company where I’m comfortable, or take the hard road and become a full-time entrepreneur. I chose the latter.

Keeping a promise to myself

A promise I made to myself after I burned my mortgage in September 2015 is that I’d slow down and get a better work-life balance. Unfortunately, that just wasn’t happening.

I’m someone who’s super ambitious. So, 6 weeks after burning my mortgage papers, I started writing a book. With the success of my book and speaking career, I’m finding myself busier than ever. I’m probably working harder now than when I was paying down my mortgage (no joke).

I’m still putting in the 80+ hour workweeks, waking up at 6:30AM and working until midnight or 1AM most days – and for what? I’m mortgage-free. I don’t have to work this many hours, but the problem is I love what I do. I enjoy my side hustle as a personal finance journalist, money coach and speaker more than my full-time job. I couldn’t keep working at this insane pace forever. I was tired all the time. Something had to give.

So with mixed emotions, in early April I made the difficult decision of choosing my budding career as a personal finance expert over my full-time career. It wasn’t an easy choice, but I was ready to make the jump.

Taking a risk

This was probably the most difficult decision I’ve ever had to make. It wasn’t easy to walk away from a steady, full-time job with benefits and a defined benefit pension plan. It was especially difficult for someone as risk adverse as me (I did after all pay off my mortgage in record timing in 3 years).

When I shared the big news with those closest to me – friends, family and coworkers – I didn’t know what to expect. Thankfully everyone has been supportive of my decision. Saying goodbye to my coworkers will be especially tough. My coworkers are like family to me. They were there when I burned my mortgage and launched my book.

It’s going to take me a while to get up and running. Luckily I have time and money. My house is paid off. I also (still) rent out the main floor of my house. The rental income alone can support me. I also have savings to last me for the years to come.

From a personal standpoint, it helps that things are less complicated. I’m single (I’m half joking when I say I’m still looking for a frugal girlfriend). I don’t have a spouse or children to look after. (Although this is a double-edged sword since I don’t have a spouse’s income to rely on either.) I’d probably hesitate to do the same thing if my circumstances were different and I was married with children.

You’ll never get rich working for someone else

Continue Reading…