Tag Archives: investing

Big questions about Investing and Personal Finance

By Michael J. Wiener

Special to the Financial Independence Hub


We spend a lot of time worrying about interest rates, stock markets, inflation, gold, and cryptocurrencies, and how they affect our investment portfolios and personal finance.  Here I explain how I think about these issues.

Are interest rates going up?

I don’t know.  But the answer can’t end there.  We have to make choices about our mortgages and investments, and interest rates matter.  Some will express predictions confidently, but they don’t know what will happen.

I prefer to think in terms of a range.  Let’s say that we think interest rates will average somewhere between 0% and 7% over the next decade.  This range is wide and reflects the fact that we don’t know what will happen.  Because current interest rates are still low, the range is shifted toward rate increases more than decreases.  The goal now is to balance potential downside with potential upside over this range.

With mortgages, the main concern is the downside: will we be okay if mortgage rates rise to 7%?  We may not be happy about this possibility, but we should be confident we could handle such a bad outcome without devastating consequences.  This is why it’s risky to stretch for a house that’s too expensive.

Bonds and other fixed income investments are a good way to moderate portfolio volatility.  However, long-term bonds have their own risks.  If you own a 25-year bond and interest rates rise two percentage points, anyone buying your bond would want to be compensated for the 25 years of sub-par interest.  This compensation is a drastically reduced bond price.  For this reason, I don’t own long-term bonds.  I stick to 5 years or less.

But can’t we do better?  Can’t we find some useful insight into future interest rates?  No, we can’t.  Not even the Bank of Canada and the U.S. Federal Reserve Board know what they’ll do beyond the short term.  They set interest rates in response to global events.  They do their best to predict the future based on what they know today, but unexpected events, such as a war or new pandemic, can change everything.

If we get overconfident and think we have a better idea of what interest rates will be than somewhere in a wide range like 0% to 7%, all we’re doing is leaving ourselves exposed to possible outcomes we haven’t considered.

Is the stock market going to crash?
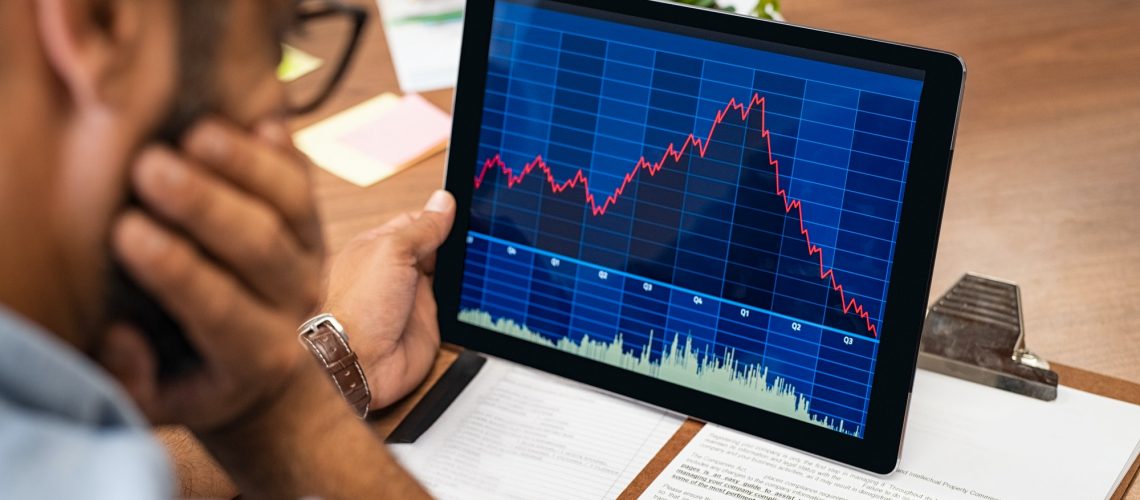
I don’t know.  With stock prices so high, it’s reasonable to assume that the odds of a stock market crash are higher than usual, and that a crash might be deeper than a typical crash.  But that doesn’t mean a crash is sure to happen.  The stock market could go sideways for a while.  Or it could keep rising and crash later without ever getting back down as low as today’s value.

People who are convinced the market is about to crash may choose to sell everything.  One risk they take is that the crash they anticipate won’t come.  Another risk is that even if stock prices decline, they may keep waiting for deeper declines and stay out of the market until after stock prices have recovered.

Those who blissfully ignore the possibility of a stock market crash may invest with borrowed money.  The risk they take is that the market will crash and they’ll be forced to sell their depressed stocks to cover their debts.

I prefer to consider both positive and negative possibilities.  I choose a path where I’ll still be okay if stocks crash, and I’ll capture some upside if stocks keep rising.  If we could fast-forward 5 years, it would be easy to see whether we’d have been better off selling everything to cash or leveraging like crazy.  But trying to choose between these extremes is not the best approach.  I prefer to invest in a way that gives a reasonable amount of upside with the constraint that I’ll be okay if stocks disappoint.

Is inflation going to get worse or return to the low levels we’ve had in recent decades?

I don’t know.  Either outcome is possible.  Higher inflation is bad for long-term bonds, which is another reason why I avoid them.  With short-term bonds and cash, you can always choose to invest these assets in a different way without taking as big a hit as you’d take with long-term bonds.

I choose to protect against inflation with stocks.  When prices rise, businesses are getting higher prices for their goods and services.  However, this protection only plays out over long periods.  Over the short term, stocks can drop at the same time that inflation is high.  Some people like to look at historical data and declare that stocks offer no inflation protection.  These people are usually playing with mathematical tools they don’t understand very well.

All of these considerations play into the balance I’ve tried to strike with my allocation levels to stocks, bonds, and cash.  I’m trying to capture some upside from good outcomes while protecting myself from disaster if I get bad outcomes.

Is gold going up?
I don’t know.  You might think my balanced approach would mean that I’d have at least a small position in gold, but I don’t.  I have no interest in investing in gold.  It offers no short-term protections against inflation or anything else.  And over the long-term stocks have been far superior.

Gold produces nothing, and it costs money to store and guard.  Gold’s price has barely appreciated in real terms over the centuries.  In contrast, millions of people wake up every day to work hard at producing profits for the businesses that make up the stock market, and money invested in stocks over the centuries has grown miraculously. Continue Reading…
Dividend Stocks: Completing the Income Puzzle

Franklin Templeton, iStock

By Les Stelmach and Ryan Crowther

Franklin Bissett Investment Management

(Sponsor Content)

It’s no secret that yields on fixed income investments have been in a prolonged slump for decades, challenging both individual investors to meet their income needs and institutional investors like pension funds and insurance companies to deliver on their obligations to retirees.

While some investors have moved further out the fixed income risk spectrum in pursuit of higher yields, others are diversifying their income sources by adding to their investments in shares of dividend-paying companies.

Dividends are playing catch-up

Despite recovering economic conditions, dividend-paying stocks lagged the overall market in 2021. Given continued uncertainties directly and indirectly related to the COVID-19 pandemic, dividend growth in general reflected some conservatism. Many factors influencing earnings growth in 2021 were sector-specific. Some industries continued to deal with subdued demand compared to pre-pandemic levels, while in other cases, regulators prohibited dividend increases at the onset of the pandemic.

Lately, however, dividend payers’ shares have performed well for several reasons:

  • Despite rising inflation, supply-chain pressures and labour shortages, corporate fundamentals have generally remained supportive as revenues, earnings and profit margins have continued to perform well.
  • Valuations for many dividend stocks are firmly anchored to those fundamentals, insulating them somewhat from market concerns over valuations in a higher-rate environment.
  • In addition to many companies initiating, restoring or raising their dividend payouts, the share prices of many dividend-paying stocks benefited from market momentum in a “best of both worlds” environment.
  • Market sentiment has shifted in response to signals from both the U.S. Federal Reserve and the Bank of Canada indicating a faster pace of interest rate increases in combination with quantitative tightening.

Dividends likely to grow

The average earnings per share growth for the Canadian S&P/TSX Composite and the U.S. S&P 500 Indices spiked last year. Dividend increases were broad-based throughout the year. Barring any major economic setbacks, we expect continued steady dividend growth from companies across many sectors. Average cash as a percentage of total assets held by constituents of the S&P/TSX Composite Index is at levels not seen in more than 20 years: another positive development for dividend growth.

In Canada, we are finding certain sectors particularly attractive:

Financials: Banks are an example of dividend growth held back by regulators from the pandemic’s onset. In 2021, even though  earnings grew, dividends were temporarily constrained; however, this restriction was lifted last November. Most recently, we have seen the Canadian banks increase dividends between 10% and 25%, but we believe there could be room for further increases. Banks retain excess capital, and at the very least, we believe the group will resume their annual pattern of increases from this point. In our view, Canadian banks are on very solid footing and offer some of the most attractive valuations.

Commodity-related: Commodity prices are high as economic activity resumes from pandemic lows, which is positive for the energy and materials sectors, and by extension, industrials. We have seen a remarkable recovery in oil prices since the precipitous drop in the spring of 2020 when the global economy shut down in response to the spread of COVID-19. At that time, a number of energy stocks had their dividends cut as the depth and duration of the economic downturn were unknown.

Since then, the oil and gas sector has staged a dramatic comeback, with higher prices boosting cash flows. Along with the recovery of prices, we also have seen a significant pick-up in dividends. Companies are employing various dividend strategies. Some prefer methodical increases to the base dividend level at a rate sustainable under a range of commodity price scenarios; others are considering variable dividends or periodic special dividend payments on top of the base dividend level. We believe boards and management teams are exercising a certain degree of caution to avoid being vulnerable if oil or gas prices experience a sharp decline in the future.

Real estate: In certain property categories (primarily retail), real estate investment trusts (REITs) had to absorb higher vacancies and deferred rent payments from tenants as stores were temporarily closed due to pandemic restrictions. These stresses often manifested as flat cash distribution profiles or, in some cases, temporary reductions in distributions. Although it’s too early to be certain of a return to historical norms across all property classes, we are seeing encouraging signs in rents and occupancy, and we note some REITs are again raising distributions.

Utilities and telecoms have maintained their dividends throughout the pandemic and we expect their dividend growth trajectories will be in line with historical experience.

Risks and opportunities

Consistent and growing dividends are characteristic of higher-quality, established companies that by definition tend to sit comparatively lower on the equity risk spectrum. It’s important to remember that like any stock, they are subject to equity market levels of volatility; but stable to growing dividends can reduce part of that risk as investors continue to receive income distributions even in a volatile market. In a rising market environment, investors could benefit both from the dividend yield and a higher stock price. Continue Reading…

Risk Management: A Four-Letter Word?

By Noah Solomon

Special to the Financial Independence Hub

Since the global financial crisis of 2008, markets have for the most part been a one-way train. Even the precipitous decline of the Covid-crash of early 2020 was erased so quickly that several months later it seemed like little more than a bad dream.

In such a favourable and long-lasting environment, risk management has increasingly become regarded as a four-letter word. Any attempt to mitigate risk and protect investors from large losses has been a money losing proposition. It has been a drag on returns and has done little to reduce volatility. Simply stated, risk management isn’t of much use when there has been no risk to manage.

Defining a Bubble: Like Catching Water in a Net

There is no universally accepted definition of a bubble. Identifying one is part art and part science and can only be done with certainty in hindsight once a bubble has become a matter of record.

Parabolic gains in markets in and of themselves may or may not signal a bubble. Similarly, situations where valuations stand significantly higher than their long-term historical averages cannot be conclusively classified as bubbles.

Further complicating matters, bubbles tend to be accompanied (if not caused) by a broad-based mindset among investors, which by definition is difficult, if not impossible to measure or define.

Behavioral Characteristics of Bubbles: Zero Fear & Speculative Frenzy

One of the most common and powerful characteristics of bubbles is a widespread belief that stocks can only go up. Aided and abetted by historical precedent, many investors have become emboldened by growing faith in a perpetual Fed “put,” whereby the central bank will move aggressively to support (and even reverse) any significant decline in markets.

Relatedly, this complacency has led to a surge in speculative madness during which a growing number of investors have piled into riskier assets, causing parabolic gains. One does not have to look far to see several signs of such behaviour, including:

  • Meme stock madness: GameStop and AMC, two companies in declining industries which respectively rocketed up 120x and 38x from their post-pandemic lows to their 2021 highs.
  • Crypto craziness: Dogecoin, which was originally conceived as a parody, went up nearly 300x to a market cap of $90 billion, spurred by tweets from Elon Musk.
  • Electric vehicle ecstasy: Hertz’s stock surged by simply announcing that it would purchase a fleet of Teslas. Similarly, Avis tripled in a day based on the mere suggestion that it might follow suit!

The Daunting and Consistent Math of Bubbles: It’s A Long Way Down

In the world of statistics, a 2 sigma event refers to something that occurs only 5% of the time. Using this framework, a market that is 2 sigmas above its long-term trend can be considered to be in bubble territory (or at the very least quite frothy). Using the same logic, a market that stands at 2 sigmas below its long-term trajectory can be thought of as mouth-wateringly cheap (or at least as somewhat of a bargain).

Founded in 1977, Boston-based Grantham Mayo Van Otterloo (GMO) is an investment management firm with roughly $75 billion in assets under management. It is well-known for its strong track record of asset allocation. The firm successfully identified and navigated both the tech bubble of the late 1990s and the real estate/financial bubble of 2006-7.

GMO analyzed the available data over financial history across all asset classes and identified more than 300 2 sigma observations. In developed equity markets, every single one of these observations over the past 100 years has fully deflated with prices falling back to their long-term trends. This pattern strongly suggests that:

  1. The higher markets go, the lower their expected future returns.
  2. The higher markets go, the longer and greater pain investors will have to endure to get back to trend.

Importantly, if you think that the recent decline in stock prices presents a golden opportunity to scoop up cheap assets, the fact that the S&P 500 currently stands about 40% above its long-term trend should be cause for sober second thought. This prospective downside is corroborated by Warren Buffett’s favourite valuation gauge, otherwise known as the Buffett Indicator, which is the ratio of the total value of the U.S. stock market to GDP. The indicator currently stands at 193%, which is approximately 50% above its historical average.

Make Mine a Triple

Using the 2 sigma definition of a bubble, in early 2021 it looked as if we might have a standard bubble. However, as the year progressed, the 2 sigma deviation progressed into an even rarer 3 sigma anomaly, which comes with an associated increase in potential pain.

Adding to concerns, real estate assets have arguably joined the bubble-party in stocks. Houses in the U.S. stand at the highest multiple of family incomes ever: even ahead of levels that prevailed prior to the housing bubble of 2006-2007. Alarmingly, this lofty multiple is lower than the corresponding level in other countries (Australia, the UK, China, and our very own Canada). Continue Reading…

Get started on your investing journey

RBC/Getty Images

By Michael Walker,

Vice-President & Head, Mutual Funds Distribution & RBC Financial Planning, RBC

 (Sponsor Content)

Whether you’re investing to build up a nest egg for retirement, to buy your first home or for a special vacation, finding the right investing solutions can play a big role in helping you achieve your financial goals.

If you’re just starting on your investing journey, however, I know that taking that first step can feel overwhelming.

To help get you started, I’ve responded below to four of the most common questions I hear about investing:

  • Do I have enough money to get started?

You don’t need to have a lot of money to start investing. It’s important to start early, however, as even small amounts of money can grow into big investments with the power of compounding.

As a simple way to think of this, compounding enables your investment to generate earnings and then those earnings are reinvested. In other words, compounding helps you grow earnings on your earnings.

The basic idea is to start investing with an amount you’re comfortable with and increase that amount over time. Once you’ve decided how much you can invest, consider setting up an auto-deposit that automatically moves that money from your chequing account into your investment account on a regular basis. This could be weekly, bi-weekly, monthly: whatever works for you and your finances. Then, as your available funds increase, you can increase the amount you deposit.

In this way, you’re benefiting from paying yourself first and the money you’re depositing will be in your investment account before you can even miss it.  

  • How do I decide which investing options are right for me?

Finding the right investing solutions starts with understanding your investing style. Here are some questions you can ask yourself, to help determine that style:

  • Why do I want to invest? How does this fit into my overall financial goals?
  • Do I want to make my own investing decisions and do I have the time to manage my own investments?
  • Am I comfortable with virtual investing, knowing there are professionals managing my investments in the background?
  • Do I want advice and support from an advisor, and if so, how much?
  • Do I want to combine doing some investing on my own with working with an advisor?  

Once you understand your investing style it will be much easier to determine the investing options that suit you best. Continue Reading…

TFSA contribution limit and overview

The federal government kept the annual TFSA contribution limit at $6,000 for 2022: the same annual TFSA limit that we had since 2019. It’s still good news for Canadian savers and investors, who as of January 1, 2022, have a cumulative lifetime TFSA contribution limit of $81,500.

The Tax Free Savings Account (TFSA) was introduced in 2009 by the federal conservative government. The TFSA limit started at $5,000 that year: an amount that “will be indexed to inflation and rounded to the nearest $500.” The TFSA limit is expected to increase to $6,500 in 2023.

TFSA Contribution Limit since 2009

The table below shows the year-by-year historical TFSA contribution limits since 2009.

Year TFSA Contribution Limit
2022 $6,000
2021 $6,000
2020 $6,000
2019 $6,000
2018 $5,500
2017 $5,500
2016 $5,500
2015 $10,000
2014 $5,500
2013 $5,500
2012 $5,000
2011 $5,000
2010 $5,000
2009 $5,000
Total $81,500

Note that the maximum lifetime TFSA limit of $81,500 applies only to those who were 18 or older as of December 31, 2009. If you were born after 1991 then your lifetime TFSA contribution limit begins the year you turned 18.

You can find your TFSA contribution room information online at CRA My Account, or by calling Tax Information Phone Service (TIPS) at 1-800-267-6999.

TFSA Overview

The Tax Free Savings Account is a flexible vehicle for Canadians to save for a variety of goals. You can contribute every year as long as you’re 18 or older and have a valid social insurance number.

That means young savers can use their TFSA contribution room to establish an emergency fund or save for a down payment on a home. Long-term investors can use their TFSA to invest in ETFs, stocks, or mutual funds and save for the future. Retirees can continue to save inside their TFSA for future consumption or withdraw from their TFSA tax-free without impacting their Old Age Security or GIS.

Unlike an RRSP, any amount contributed to your TFSA is not tax deductible and so it does not reduce your net income for tax purposes.

  • Your contribution room is capped at your TFSA limit. Excess contributions will be taxed at 1 per cent per month
  • Any withdrawals will be added back to your TFSA contribution room at the start of the next calendar year
  • You can replace the amount of your withdrawal in the same year only if you have available TFSA contribution room
  • Any income earned in the account, such as interest, dividends, or capital gains is tax-free upon withdrawal

How to open a TFSA

Any Canadian 18 or older can open a TFSA. You are allowed to have more than one TFSA account open at any given time, but the total amount you contribute to all of your TFSA accounts cannot exceed your available TFSA contribution room.

To open a TFSA you can contact any bank, credit union, insurance company, trust company or robo-advisor and provide that issuer with your social insurance number and date of birth.

The most common type of TFSA offered is a deposit account such as a high-interest savings account or a GIC.

You can also open a self-directed TFSA account where you can build and manage your own savings and investments.

Qualified TFSA Investments

That’s right: you’re not just limited to savings accounts and GICs. Generally, you can put the same investments in your TFSA as you can inside your RRSP. These types of allowable investments include:

  • Cash
  • GICs
  • Mutual funds
  • Stocks
  • Exchange-Traded Funds (ETFs)
  • Bonds

You can contribute foreign currency such as USD to your TFSA. Note that your issuer will convert the funds to Canadian dollars. The total amount of your contribution, in Canadian dollars, cannot exceed your TFSA contribution room.

If you receive dividend income from a foreign country inside your TFSA, the dividend income could be subject to foreign withholding tax.

Gains inside your TFSA

Some investors may be tempted to put risky assets inside their TFSA account to try and earn tax-free capital gains. There are two advantages to this strategy: Continue Reading…