Tag Archives: investing

Looking under the hood of a Guaranteed Universal Life Policy

By Jessica Walter

Special to the Financial Independence Hub

Though it can be morbid and upsetting to think about, it’s important that seniors have life insurance in place so that their families don’t have to worry.

Despite this, 54% of Americans say they are unlikely to purchase life insurance. As well as this, according to research organization LIMRA, 51% of all households say they would rely on life insurance payouts to pay bills and maintain their lifestyle, in the event of the main breadwinner passing away. That’s why it’s so important to choose a life insurance policy that works for you, and brings you the best benefits and flexibility.

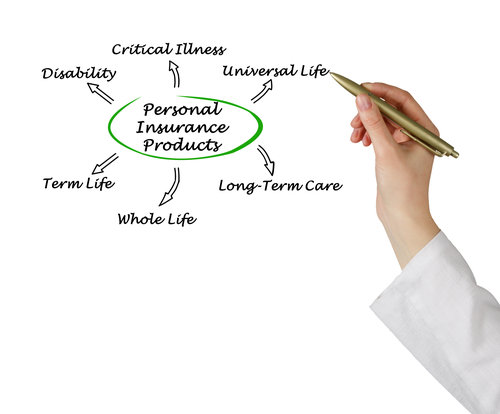
Understanding the different types of available insurance policies is vital, as it could make a big difference to the amount you pay in premiums, as well as how much the family will receive in the event of a death.

What Is a Guaranteed Universal Life Policy?

A guaranteed universal life policy is one of the best ways for seniors to get coverage for life, for the lowest possible cost. Whether you qualify will depend on your health, and your age. The main positive of a GUL plan is its ability to meet a wide range of budgets.

This type of plan is similar to a whole life insurance policy, but is made more affordable by gaining cash value in the initial years. This value is then used to offset an increase in premiums in the future. This is in contrast to a whole life insurance policy, which would continue to gain cash value, but requires higher premiums to be paid. A guaranteed life insurance policy is one of the most popular around, and will meet the needs of the majority of healthy people, but it isn’t the only insurance policy available.

The Benefits of a Guaranteed Universal Life Insurance Policy
Continue Reading…

How to create a winning retirement income strategy

A successful retirement begins with a successful retirement income strategy.

One of the things that investors of all ages fear is that they won’t have a good financial plan in place so that they have enough retirement income to live on once they’ve stopped working.

Here are some ways to ease that anxiety:

In retirement, try to even out (equalize) your income with your spouse’s income, to lower overall taxes. Here’s how:

1.) Have the higher income spouse pay the household bills

The easiest way to even out income between two spouses is to have the higher-income spouse pay the mortgage, grocery bills, medical costs, insurance and other non-deductible costs of family life.

2.) Set up a spousal RRSP

Registered retirement savings plans, or RRSPs, are a form of tax-deferred savings plan designed to help investors save for retirement. RRSP contributions are tax deductible, and the investments grow tax-free.

3.) Pay interest on your spouse’s investment loans

If the lower-income spouse takes out an investment loan from a third party, such as a bank, the higher-income spouse can pay the interest on that loan.

RRIFs are a great long-term retirement income strategy

Continue Reading…

Men and women approach taxes & investing differently

By Gennaro De Luca

Special to the Financial Independence Hub

Anyone who is in financial services, and especially wealth management, knows there are big differences between men and women in terms of how they invest. But what isn’t as well known is that there are also big differences between men and women when they do their tax returns.

I started working at a bank at the age of 19, have been in financial services since 1990, and have spent the past 18 years in wealth management. But I also have a company that specializes in doing tax returns for small businesses, families and students. All this experience has provided a lot of insight into how men and women differ when it comes to financial matters.

Let’s first look at tax returns. Nine times out of ten it is the woman who takes the bull by the horns to get the family’s taxes done. Women tend to be more involved and are much more apt to ask questions of their accountant or tax preparer. Men may not ask any questions at all; they just hand over their documents and see you later.

What kind of questions am I talking about? Women want to know things like this:

  • What kind of tax credits are we eligible for?
  • Are there any government benefits we are eligible for?

That latter point is especially important for women who have small children. Indeed, many young families are really squeezed nowadays, so every opportunity for a tax break is vital.

Here is a perfect example from a client that illustrates what I mean. The woman is a teacher who could claim certain expenses for driving her car to work. Her husband is not a teacher, but does work for an employer. She asked us if her husband is also eligible for this same deduction because, like her, he drives a car for his employer and has lots of expenses.

As it turned out, he was eligible for what is known as a T2200, which is a declaration of conditions of employment –- effectively work-related expenses –- and in his case it meant deductions of $10,475, which resulted in a tax saving of over $3,000 on his tax return. But if his wife had never asked the question, none of this would have been claimed.

Men are more resistant to change

Another difference with doing taxes concerns technology. Today more than 80% of tax returns in Canada are done digitally, Continue Reading…

The Pros and Cons of Universal Life Insurance

By Lorne Marr, LSM Insurance

Special to the Financial Independence Hub

Universal Life Insurance gives you flexible, cost-effective coverage that lasts a lifetime. It can be personalized to suit your changing needs and has a combined tax-advantage investment component that you can manage according to your risk tolerance and financial goals. Universal Life Insurance was invented by the recently deceased George R. Dinney in 1962. He explains the concept in his authorship of “Life Insurance as a Game.”

Universal Life Insurance allows you to adjust your premium payments (reasonable limits apply) as your needs or situation change. It is the ideal choice for people interested in flexible coverage. Unlike term insurance, which covers for a set number of years, universal coverage protects your family for life, as long as you keep up with the premium payments.

The policy has an investment component that gives you the opportunity to grow your wealth, so you have the option of using your life insurance while you are still alive. This means you can fund financial goals or leave more to your beneficiaries.

All the premium payments you make go into a policy fund. This fund pays for the cost of your coverage plus investments. The balance remaining after coverage costs are invested on a tax-advantaged basis. There are a variety of investment options for you to choose from, based on your risk tolerance and financial objectives.

How much your investment will grow depends on the performance of your investments and the amount of your premiums. The money in the investment portion of your account is yours. You can use it to make premium payments or a source of savings. You can use it as collateral for a loan, withdraw it outright or just let it grow for financial security for your loved ones. Don’t forget that borrowing or withdrawing funds from your policy reduces its cash value.

Pros of Universal Life Insurance

Universal Life Insurance provides many benefits, such as: Continue Reading…

“Botched” CRM2 implementation just adding to investor confusion: veteran adviser

Tim Paziuk

By Tim Paziuk

Special to the Financial Independence Hub

After 37 years in the financial services industry I realize I shouldn’t be surprised, and I’m not. I’m shocked. Shocked by the confusion created by the very people who are charged with the responsibility of watching out for us, mainly the Canadian Securities Administration (CSA).

Here is the first paragraph from the overview on the CSA website

The Canadian Securities Administrators (CSA) is an umbrella organization of Canada’s provincial and territorial securities regulators whose objective is to improve, coordinate and harmonize regulation of the Canadian capital markets.

I draw your attention to the words ‘improve, coordinate and harmonize’. In my opinion, they have done more to hinder and confuse the average Canadian than to provide clear and complete information.

Let me give you some background on the recently implemented program referred to as the Client Relationship Management Model – Phase 2 (CRM2).

According to the Ontario Securities Commission:

The Client Relationship Model – Phase 2 (CRM2) amendments to NI 31-103 that came into effect on July 15, 2013 are being phased-in over a three-year period. These amendments introduce new requirements for reporting to clients about the costs and performance of their investments, and the content of their accounts. The requirements apply to dealers and advisers in all categories of registration, with some application to IFMs as well. For more information about these amendments, see CSA Notice of Amendments to NI 31-103 and to 31-103CP (Cost Disclosure, Performance Reporting and Client Statements). Continue Reading…