All posts by Financial Independence Hub

How to stop comparing yourself to Others: 12 Tips

What is one tip to help stop comparing yourself to others?

To help you stop comparing yourself to others, we asked personal coaches and thought leaders this question for their best advice. From practicing gratitude to asking yourself questions that challenge you, there are several things you may put into practice to help you stop comparing yourself to others.

Here are 12 tips to stop comparing yourself to others:

  • Practice Gratitude

  • Look Back and Count Your Gains

  • Admire Your Differences Instead

  • Override Your Dissatisfaction With Positive Affirmations

  • Celebrate Others

  • Take a Break from Social Media

  • Remember Everyone Has Their Challenges

  • Identify and Celebrate Your Own Strengths

  • Practise Meditation To Stay Grounded in Yourself

  • Focus on Your Own Personal Growth

  • Choose To Practise Good Values

Ask Yourself Questions That Challenge You

Practice Gratitude

When you regularly practice gratitude, you don’t have time to focus on what others have. You’re not inclined to compare yourself to them or think about what you lack. With a gratitude mindset, you’re focused on what you have, and how appreciative you are of having it. Gratitude resets your mind and redirects your energy towards building up more of what you already have rather than trying to catch up to someone else. — Chris Abrams, Abrams Insurance Solutions

Look Back and Count your Gains

It’s easier said than done, but try thinking about or even making a list of the things you used to want that you have or are closer to having now. For example, maybe 10 years ago you wanted to be moving up in your career and getting closer to buying a house. Rather than beating yourself up about what your friend or that person on Instagram is doing, ask yourself what you’ve already achieved that a past version of you would be proud of, or what you’ve learned that a younger version of you didn’t understand.

When you frame challenges and comparisons this way, you’re not only able to see your strengths and what you’re capable of much more clearly, but you’re also setting yourself up to be a better version of yourself as opposed to a better version of someone else. — Gigi Ji, KOKOLU

Admire your Differences instead

When you compare yourself to others, you mentally put yourself below them. You convince yourself that you don’t have something that someone else does have and you take your power away. But, if you admire your differences instead of comparing them, you put positive energy out into the world and that gives you the power.

The power to appreciate what you have, the power to learn from what others have, and the power to choose how you view the world and yourself in it. It’s easier to be positive than to be negative, so take the easy and healthy route and admire someone instead of comparing yourself to them. –– Staci Brinkman, Sips by

Override your Dissatisfaction with Positive Affirmations

Drown out the comparisons with positive affirmations. The moment that you start to compare yourself to someone, think of something that you do well and tell yourself that instead. It’s a simple trick, but over time, your mind gets the idea and will stop seeing yourself as less than, and instead as equal to, and the comparisons will fall away. It will take time, and it feels funny at first, but it’s a reminder that we’re our harshest critic, instead of our greatest support, and the latter takes practice. — Tony Staehelin, Benable

Celebrate Others

Many people do compare themselves to others these days and that tends to make them more self-absorbed. One way to stop that attitude is to celebrate others’ achievements. You can avoid the comparison syndrome by focusing on other people and learning to be happy for them in their moments. This can take some practice. It may not feel good at first because many are motivated to draw attention to themselves. However, you will care less about where you stand in society the more you learn to focus on other people. Focusing on others will make you happier and then the comparisons don’t have as much power over you. — Bruce Tasios, Tasios Orthodontics

Take a Break from Social Media

My top tip to stop comparing yourself to others is to take a break from social media. Social media is likely only one place you compare yourself to others, but it’s a big one. If you scroll on your phone for a few hours a day and in that time, feel bad about yourself, it’s time to take a break. Disconnect from social media for a bit and focus on yourself! If you choose to get back on social media, unfollow anyone who makes you feel bad about yourself. — Macy Sarbacker, Macy Michelle

Remember Everyone has their Challenges

Comparing yourself to others is fruitless because everyone has their own set of challenges. These challenges are often not visible to those on the outside. Individuals can never hope to know the struggles of others by comparing themselves to the success they see on the surface.

Wanting what others have lacks perspective because we often do not know what other people are carrying with them. A successful executive may appear to have a wealthy lifestyle when in reality they have the misfortune of tumultuous family life or chronic illness. Comparing yourself to others is pointless when you are unaware of what others are truly dealing with. — Katy Carrigan, Goody Continue Reading…
Recession or Stagflation?


By Dale Roberts, cutthecrapinvesting

Special to the Financial Independence Hub

Many economists and market experts are suggesting that the outcome for 2022 and into 2023 might be that we experience a recession or stagflation. That’s not a good choice we might think. And of the two ‘options’, we might prefer a recession. A recession might do enough to quell inflation. And we do have to stomp out inflation hard the first time. That is, central bankers have to raise rates aggressively enough to hurt the consumer enough to reduce demand and get inflation well under control. If they let inflation fester, it may resurface and cause even more trouble as it did in the 1970’s stagflation era. Recession or stagflation, who knows what we will get. The idea is to be aware and prepared.

Recession or stagflation?

In the Globe & Mail (paywall) Ian McGugen asked the question: What comes next: stagflation or recession?

Given that it may be the very unfortunate war in Ukraine that pushes us over the edge I suggested that a Russcession is coming. From Ian …

As anyone who has read a bear-market headline has gathered by now, the economic outlook is turning ugly. The question that lingers is just what form of ugliness it will take.

In one scenario, soaring interest rates and climbing oil prices clobber the economy, leading to a painful but short recession that stamps out today’s roaring inflation.

In another scenario, a recession may be averted, but inflation isn’t. The economy stumbles along in a stagflationary funk as rising prices continue to ransack consumers’ wallets.

Of course, we don’t know what we’re going to get. We can also add a soft (economic) landing in the mix. The central bankers raise rates and make enough noise to spook the consumer enough to bring down inflation while not creating a recession. Or perhaps we get a soft and quick recesssion? Who knows? Nobody knows.

That’s why we prepare for the the unknown, for a future that we do not know.

A must read: the new balanced portfolio.

The history of bears and corrections

Here is a post that looks at the history of stock market corrections and bear markets (a correction of 20% or more). As of this writing (originally in mid June) U.S. stocks recently tipped into bear market territory. Canadian stocks are now in correction mode (down 10% or more).

It is important to be aware of the potential for portfolio decline, and also to know how long you might have to grin and bear it as you buy stocks on the way down.

And yes, if you’re in the accumulation stage, you’re a buyer. Building wealth can be and should be super easy, but it can be emotionally taxing. Maybe a better way to frame it is that building wealth is super easy, keeping that wealth is not so easy.

Stock market corrections and bear markets are wealth building turning points. We need to hang on to our past gains (don’t sell). Corrections and lower stock prices are wonderful long-term wealth building opportunities. Some of the best buying opportunites are offered during corrections and bear markets.

Not cheap, yet?

And sure, U.S. stocks are not that cheap. From Scott Barlow, citing a Goldman Sach’s report: Despite the 18% YTD S&P 500 decline, equity valuations remain far from depressed. The median S&P 500 constituent’s P/E ratio of 18x ranks in the 87th percentile since 1976. For context, in March 2020 the median stock’s P/E was 14x .

Translation: at current valuations, U.S. stocks were still more expensive only 13% of the time, from 1976. That said, it is near impossible to time the markets. The dollar cost averager will find very good value along the way. The dollar cost averager will be buying at the market bottoms and will be lowering their average cost per share.

And recently I offered that Canadian stocks are looking good with respect to valuations.

And how about international markets?

Keep buying.

The upside of rising rates

Our savings account rates and bond yieds will increase. They are increasing. At EQ Bank many GICs are now above 3% and even 4%.

Stocks are looking better but there may be more pain to come. Continue Reading…

7 simple ways to pay off Debt in Retirement

By Lyle Solomon

Special to the Financial Independence Hub

Carrying debt into retirement can ruin your golden days. You will most likely have a limited income after retirement. Though you can boost your Social Security income by taking the proper steps, your spending may rise yearly due to inflation, causing your budget to collapse. The burden of debt and the high expense of medical bills can wreck your retirement.

According to a CNBC report, the total debt burden of America’s senior citizens has increased by 543 per cent in the last two decades. 70% of baby boomers are in credit-card debt and are unsure how they can get out of it. It is recommended to pay off your obligations as soon as possible and enjoy your golden years. Repaying your debts during retirement is always a good idea. But how will you go about it? Here are some of the ways to repay your debt in retirement so that you can enjoy your golden years.

1.) Sort your debts by priority

The first stage in debt management in retirement is prioritizing which bills to pay off first. So, make a list of all your loans, including their interest rates and remaining balances. Unsecured debts, such as credit cards, typically carry high-interest rates because no collateral is required. I recommend that you begin paying off loans with the highest interest rates first, which will help you save money in the long term. Furthermore, unlike student loans or mortgages, you cannot deduct interest payments from your tax returns on unsecured debts.

It is preferable to pay off unsecured obligations first, as they are not usually tax-deductible.

2.) Seek professional debt assistance

Are you drowning in high-interest unsecured debt? If this is the case, you may be working hard to repay your obligations but cannot do so due to the constant high-interest rates. In that case, you can seek professional assistance by contacting a reliable debt relief business. The company’s debt advisers will examine your debts and develop a reasonable payback plan based on their findings. You can enroll in a credit card consolidation process to repay your huge credit-card debt. Settling debts can be possible under the guidance of a professional debt relief company. They will  negotiate with your creditors to lower the excessive interest rates. Once your creditors have agreed, you can begin making single monthly payments for all of your debts. In this manner, you may pay off your unsecured obligations without worrying about coordinating multiple payments. You can also save money on interest payments because your debts’ interest rates will likely be reduced.

3.) Examine your budget again

Hopefully, you have a budget to keep a proper spending plan and preserve money for your financial well-being. The more you put into your monthly loan payments, the faster you’ll be debt-free. As a result, you must save more to increase your monthly loan payments.

To do so, go over your budget and identify places where you may decrease costs and save money. You can save money on things like eating out, entertainment, cable TV subscriptions, etc. You can save a significant amount of money to put towards your monthly debt payments.

4.) Follow your preferred debt repayment plan

You can use any debt payback method, debt snowball or avalanche. The debt snowball strategy requires prioritizing the debt with the lowest outstanding sum first. At the same time, you must make minimum payments on all of your other loans. After you have paid off that loan, you must focus on the debt with the second smallest outstanding balance, and so on. Continue Reading…

What you need to know before investing in All-in-One (Asset Allocation) ETFs

By Michael J. Wiener

Special to the Financial Independence Hub 


I get a lot of questions from family and friends about investing.  In most cases, these people see the investment world as dark and scary; no matter what advice they get, they’re likely to ask “Is it safe?”  They are looking for an easy and safe way to invest their money.  These people are often easy targets for high-cost, zero-advice financial companies with their own sales force (called advisors), such as the big banks and certain large companies with offices in many strip malls.  An advisor just has to tell these potential clients that everything will be alright and they’ll be relieved to hand their money over.

A subset of inexperienced investors could properly handle investing in an all-in-one Exchange-Traded Fund (ETF) if they learned a few basic things.  This article is my attempt to put these things together in one place.

Index Investing

Most people have heard of one or more of the Dow, S&P 500, or the TSX.  These are called indexes.  They are a measure of the price level of a set of stocks.  So, when we hear that the Dow or TSX was up 100 points today, that means that the average price level of the stocks that make up the index was up.

It’s possible to invest in funds that hold all the stocks in an index.  In fact, there are funds that hold almost all the stocks in the whole world.  There are other funds that hold all the bonds in an index.  There are even funds that hold all the stocks and all the bonds.  These are called all-in-one funds.

Most people know they know little about picking stocks.  They hear others confidently talking about Shopify, Google, and Apple, but it all sounds mysterious and scary.  I can dispel the mystery part.  Nobody knows what will happen to individual stocks.  Bold claims about the future of a stock are about as reliable as books about future lottery numbers.  However, the scary part is real.  If you own just one stock or a few stocks, you can lose a lot of money.

When you own all the stocks and all the bonds, it’s called index investing.  This approach to investing has a number of advantages.

Investment Analysis

Investors who pick their own stocks need to pore over business information constantly to pick their stocks and then stay on top of information to see whether they ought to sell them.  When you own all the stocks and all the bonds, there’s nothing to analyze or track on a frequent basis.

Risk

Owning individual stocks is risky.  Any one stock can go to zero.  Owning all stocks has its risks as well, but this risk is reduced.  The collective stocks of the whole world go up and down, occasionally down by a lot, but they have always recovered.  We can’t predict when they’ll drop, so timing the market isn’t possible to do reliably.  It’s best to invest money you won’t need for several years and not worry about the market’s ups and downs.

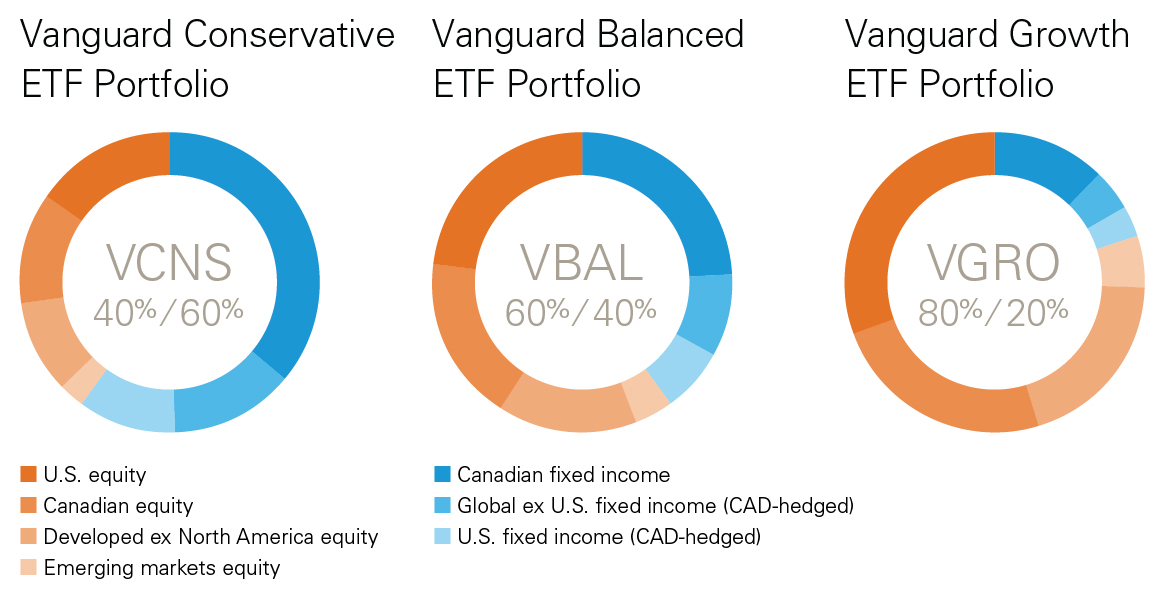
To control risk further, you can invest in funds that include both stocks and bonds.  Bonds give lower returns, but they’re less risky than stocks.  Taking Vanguard Canada’s Exchange-Traded Funds (ETFs) as an example, you can choose from a full range of mixes between stocks and bonds:
ETF Symbol     Stock/Bond %
      VEQT           100/0
      VGRO           80/20
      VBAL           60/40
      VCNS           40/60
      VCIP           20/80

Cost

Sadly, many unsophisticated investors who work with financial advisors don’t understand that they pay substantial fees.  These investors typically own mutual funds, and the advisor and fund company help themselves to investor money within these funds.  There is no such thing as an advisor who isn’t paid from investor funds. Continue Reading…

6 ways a Recession resembles a Bad Mood

LowrieFinancial.com: Canva custom creation

By Steve Lowrie, CFA

Special to the Financial Independence Hub

There’s been a lot of talk about recessions lately: Whether one is near, far, or perhaps already here. Whether we can or should try to avoid it. What it even means to be in a recession, and how it’s related to current market turmoil.

To put market and recessionary concerns in perspective, it might help to describe six ways a recession resembles a bad mood. There are some intriguing similarities!

1.) There is no Precise Definition

We all know what a bad mood feels like. But there is no clear definition for a nebulous mix of real and perceived setbacks, and how they’re going to affect us.

Likewise, there is no single signal to tell us exactly when a recession is underway or when it’s over. Instead, recessions can trigger, and/or be triggered by a number of conditions connected in various fashions and to varying degrees. These usually include a declining Gross Domestic Product (GDP), along with rising unemployment, sinking consumer confidence, gloomy retail forecasts, disappointing corporate balance sheets, a bond yield curve inversion, stock market declines, and similar combinations of objective and subjective events.

In the U.S., the National Bureau of Economic Research (NBER) intentionally defines a recession rather vaguely as follows (emphasis ours):

“A recession is a significant decline in economic activity that is spread across the economy and that lasts for more than a few months.”

Closer to home, the Bank of Canada and/or the minister of finance typically let us know once we’re in a recession. As described here, they base their calls on guidance from the 2015 Federal Balanced Budget Act, economic indicators coming out of Statistics Canada, and economic analyses from Canadian economists such as C.D. Howe Institute’s Business Cycle Council.

Globally, the World Bank Group has stated, “Despite the interest in global recessions, the term does not have a widely accepted definition.”

2.) You usually can’t spot one except in Hindsight

How do you know when you’re in a bad mood? Often, you don’t, until you’re looking back at it.

Recessions are similar. Since a widespread downturn must linger for a while before it even qualifies as a recession, governments typically only declare one after it’s underway. For example, triggered by the abrupt arrival of the global pandemic, Canada and the U.S. alike entered into their shortest recessions to date, beginning and ending in first quarter 2020. However, neither government announced the news until July and August, respectively.

3.) Sometimes, we get stuck for a while

Hopefully, your bad moods come and go, resulting in more good times than bad. But sometimes, one misfortune feeds another until you feel gridlocked. It may take a while before improved conditions, a more upbeat attitude, or a blend of both help you move forward.

In similar fashion, recessions can become a self-fulfilling prophecy. As Nobel Laureate and Yale economist Robert Shiller describes, “The fear can lead to the actuality,” in which (for example) economic conditions might feed inflation, which inverts the bond yield curve, which signals a recession, which shakes corporate and consumer confidence, which leads to unfortunate reactions that further aggravate the challenges. And so on. When this occurs, a recession and its related financial fallout may last longer than the underlying economics alone might suggest.

4.) They’re Inevitable

It’s never fun to be in a bad mood, but we can all agree they’re part of life. It would be unhealthy, exhausting even, if we were endlessly giddy every minute of every day.

Similarly, nobody celebrates a recession. But it helps to recognize they aren’t aberrations; they are part of natural economic cycles. And while they may not be anyone’s favorite tool for the job, they can sometimes help rein in runaway spending, earning, and pricing for companies, consumers, and creditors alike. Continue Reading…