All posts by Financial Independence Hub

Are all Pension incomes created equal?

Image Shutterstock

By Ian Moyer

Special to the Financial Independence Hub

Pension incomes are not created equal. They come in all shapes and sizes. They are as varied as the people who have accumulated them and who seek to use them. 

In this seemingly infinite variety, in this mathematical complexity, there is a common thread as far as advisors are concerned: delivering clients the most after-tax income possible. 

CPP, OAS, Defined Benefit Pension, Dividend Income, Interest Income, RRIFs, Part Time Employment Income, Corporate Dividends, TFSAs: These are just a few of the various sources of income individuals may have access to when they exit the workforce.  Upon retirement, decisions about what, when, and how much income to draw upon, move to the forefront.

Tax is key to coordinating multiple income streams

Coordination here is key as each of these sources of income is subject to different tax rates, different tax deferrals and different estate taxes. Tax is key, in other words.

Recent or prospective retirees need more than a competent advisor at this stage. Understanding the tax rates, tax deferral rates and the implications regarding OAS and Income Splitting is one thing. But accounting for these sources of income and the complicated ways in which they interact requires an algorithm.

The specialized software, Cascades, cascadesfs.com, performs these calculations, giving users informed withdrawal strategies. Designed by financial advisors in partnership with software developers, Cascades uses actual tax rates, not average tax rates, projecting for the duration of retirement, including longevity risk.

Because numbers require context to be meaningful, let us consider prospective retirees Bill and Anne Smith.

Case Study: a Couple in their late 60s

Retirement Plan: Bill and Ann are 68 and 67 currently. They have been retired for a few years but still have RRSPs and a LIRA and want to know if they should start using them for income or defer payments until age 71. 

Income Sources: Both have CPP and OAS. Anne has a defined benefit pension from having worked as a teacher. 

Investments: Bill has a healthy RRSP and Anne has a modest RRSP and a LIRA. They have maxed out their TFSAs and each have about $100,000 additionally in individual non-registered accounts. 

Total: 12 different income sources and investment accounts to manage for retirement income
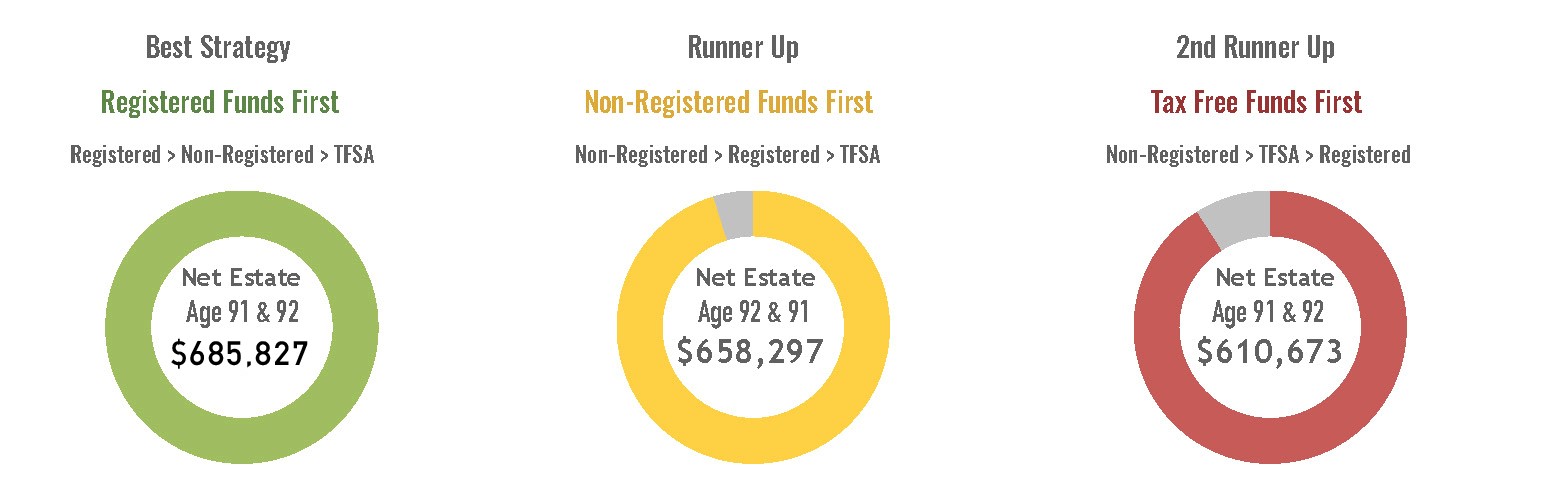
Cascades provides direction in the following way. Users — whether they be Anne and Bill themselves, or their advisors — fill in a detailed online questionnaire, submit their responses and in under ten seconds they have a report. This report (an excerpt is shown at the top of this blog) automatically gives three potential strategies and shows which one works best. For Anne and Bill, drawing down and re-investing their registered accounts first is expected to save them over $75,000 in their estate compared to a complete deferral of their registered money. 

As far as Bob and Linda Sanderson are concerned, on the other hand, a Cascades report advises them to do just the opposite and ultimately predicts a savings of $125,000. Here’s how:

Quite different withdrawal recommendations for this younger couple

Bob and Linda are both 55 and currently working. They plan to retire in 10 years. They have a rental property they maintain that they plan to sell in 15 years and want to know how to plan for the long-term. 


Income Sources: Both will receive CPP and OAS. Bob will receive a small defined benefit pension. Both will earn rental income until sale of the property. Both will receive corporate dividends until age 80 from a holding company. 

Investments: Both have large RRSPs, nearly capped TFSAs, and a small amount of non-registered savings. Additionally, Linda has a small LIRA. 

Total: 18 different income sources and investment accounts to manage for retirement income.
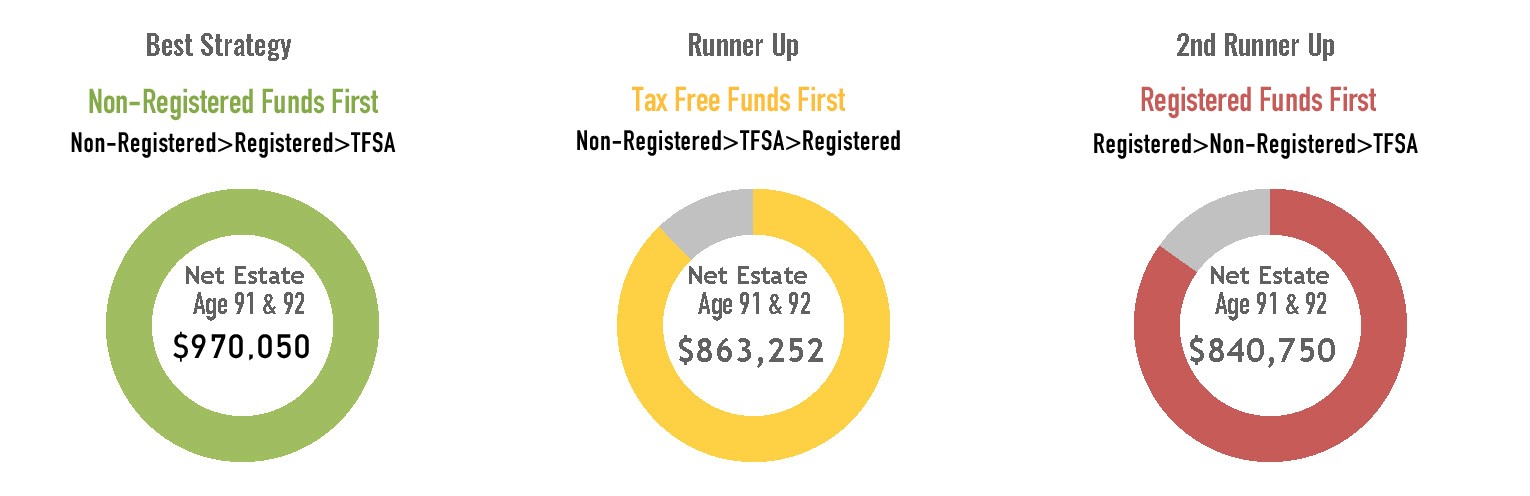
Cascades proposes three withdrawal strategies and highlights the best plan. Using all of their non-registered savings before rolling over registered investments will save Bob and Linda over $125,000 in their estate compared to an early drawdown of their registered money. Cascades software is designed to help users do their due diligence on the matter of retirement planning. The results are specifically tailored to the retirement in question and they are reliable, informed and rigorously defined as they are by Canada’s vast and varied tax laws.

.
Ian Moyer is the founder of Ian C. Moyer Insurance Agency Inc. and Cascades Financial Solutions Inc.
Is 2019 gold’s year to shine? A Q&A with Harvest president & CEO Michael Kovacs

Harvest Portfolios Group Inc. launched a global gold ETF yesterday (on January 15, 2019.) In the sponsored Q&A below, Harvest President & CEO Michael Kovacs explains why the company is launching the Harvest Global Gold Giants Index ETF (TSX: HGGG) now, the thinking behind this unique ETF and why the ETF aligns with the Harvest value strategy of conservative growth and income.

Why is Harvest launching a gold ETF?

We are not gold bugs, but we have been looking at the gold market for some time, especially gold company shares. They have been in a bear market for the better part of six years, so share prices are low. We see considerable value there.

A lot of the smaller companies are out of business because they couldn’t make money at these lower prices. Others that are struggling are being acquired by the big companies. Consolidation is a sign of a market bottom and while there is always downside risk in investing, we think a lot of that risk is out of the market.

So your focus is just the largest global producers?

Yes. If you’re a large firm you’re able to take advantage of the situation.  So we looked at the top global gold companies – the biggest by market cap – and are focusing on just the top 20. So if gold rises there is a lot of upside potential.

The other thing is that we’re in the late stages of the economic cycle. I don’t know whether we are in the ninth inning, or we have some extra innings ahead, but at some point US markets will start to weaken. Interest rates will top out and probably decline. We will see some decline in the US dollar as well. The US dollar has been on a tear and like any cycle it will probably come to an end.

At that point investments like gold make a lot of sense. There’s inherent leverage in the equities if gold prices rise.

Why is that?

In a simplified example, let’s say you are Barrick Gold Corporation producing gold at $800 an ounce. Gold is worth about $1,250 an ounce, so your margin is $450. If gold rises by $250 to $1,500, you’re increasing your profit margin by 55%. That goes directly to the bottom line.  So we think it is an opportune time to be looking at large gold producers.

Are you worried about inflation?

We do not see a lot of inflation. There may be some inflationary pressures, but the world has changed so much with technology. Continue Reading…

5 tips for new parents wanting to own their own home

By Ernesto Mar Domingo

(Sponsored Content)

Owning a house may sound daunting. It can be an instant switch that can make you feel excited, nervous and really conflicted.

Although home ownership is a trial and error thing, it is a possible goal if you aim for it. One thing that can help you with this journey is a solid house-buying battle plan.

Like any other major purchases, you need help, research, and a strong resolve, but as a parent, you may be more motivated on this goal. After all, there is nothing greater than getting your own roof for your family.

Ready to embark on this ride to successful homeownership? Here are five tips to get you on your way.

1.) Know what you and your family need

We all have a certain dream house. While we may rather live in a castle or a glass house, we have our family to account for.

It is crucial that you choose with your brain and not your heart. To do this, you need to acknowledge what your family needs. You need to think of your lifestyle and look for a home that perfectly fits this kind of living.

Knowing what you need in a home is the first step in owning one. There are many kinds of houses: apartment, single-family home, condominium space or even a cottage in the countryside.

Aside from this, you also need to write down how many rooms, bathrooms, kitchens, and other utilities you need. Do you need a garden? A large garage? Balconies facing the sunsets? You should take all of this into consideration.

However, be realistic. You can’t exactly buy the best and grandest home you can imagine. Unfortunately, we have what we call a budget. In the end, choosing a house will still go down on how much you can afford.

2.) Save. Save. Save.

The biggest question in owning a home is glaringly challenging: how much can you afford?

But do not let this keep you down. With a grueling but fruitful savings regime and iron-clad perseverance, you can save up enough money for your dream home.

How?

You can:

  1. Create a budget plan.
  2. Give your savings a time frame to move things up.
  3. Cut down any unnecessary bills and payment.
  4. Earn larger amount money.

3.) Stick to your budget

The idea of maximizing all your income and savings sounds reasonable enough, right? Unfortunately,  it is not practical. Continue Reading…

Cheering for Daniel-san to crane-kick the FAANG stocks


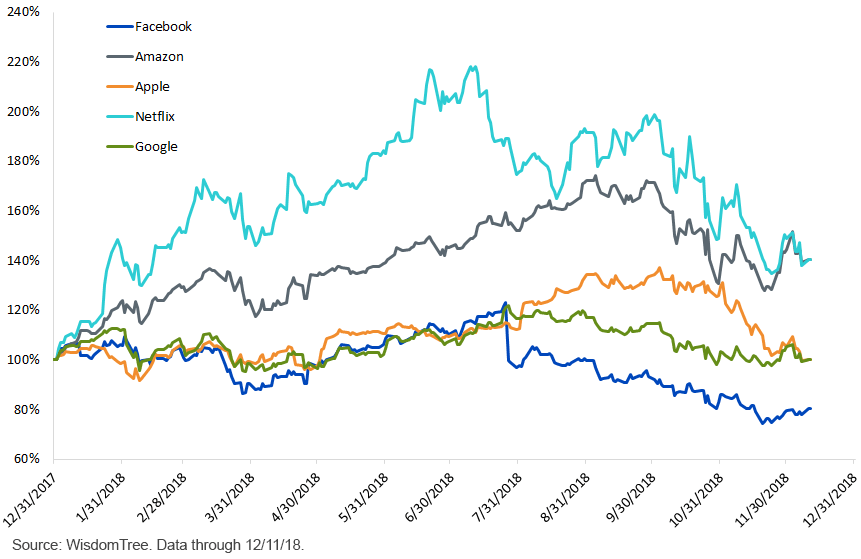
Figure 1: Share Price Performance, YTD 2018

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

FAANG. What an acronym. A FAANG stock, cobra logo on its uniform, is like the antagonist in the classic 1984 movie The Karate Kid.

The FAANG (Facebook, Apple, Amazon, Netflix and Google-parent Alphabet) is unstoppable as he sweeps the leg and kicks the proverbial “value stock,” Daniel-san, in his broken ribs. No mercy. Miyagi, Daniel-san’s mentor, cannot help him.

At least that was the situation until a few months ago, when both Apple and Amazon reached valuations north of $1 trillion.

When I wrote about the top-heaviness of FAANG stocks in market capitalization-weighted indexes earlier this year, these five stocks alone accounted for about one-eighth of the U.S. stock market. Since then they have been cracked, with Facebook and Netflix taking the hardest hits.

Not many of us have issues with Netflix as an organization. But the other four FAANGs’ public reputations are on tenterhooks.

Amazon gives millions of small businesses sleepless nights, while its employees complain of poor working conditions. Want to talk about business risk? Wake up one morning to President Trump doing a Teddy Roosevelt trust-buster impersonation. You’re unstoppable until Daniel-san gets into the crane position.

Or look at the half-dozen reasons that reasonable people hate Facebook. One of them is probably our collective inability to prevent hundreds of images of our children from being plastered on its site, even if we are not “on Facebook.” If you don’t like it, tough luck. The BBC cites an Ofcom study finding that 70% of people do not think it is OK to share images of others without permission. It’s that other 30% that the rest of us have to worry about.

But there’s so much more.

Facebook is beset by accusations about “fake news” and political biases.  Also, how about your high schooler’s shrinking attention span and growing self-doubt as friends post solely their life’s highlights?

Stock market sentiment is a fragile thing: $408 billion is a lot to pay for a company that you and your next-door neighbour dislike.

And while we’re talking about aiding and abetting our society’s mass experiment with device-addicted zombie scatterbrains, there’s Apple. It sells the pipe to the smoker.

There is no shortage of people itching for Daniel-san to kick some of these companies in the face, in the interest of civil society. Our industry wants to talk about environmental, social and governance (ESG) screens. Great. Let’s talk candidates.

Google cannot be forgotten. The internet was supposed to be a utopia of free discourse.  Free discourse, unless the Chinese Communist Party’s censors give you heat.

When a company like Sears or Woolworth’s rolls over, most of us feel bad, nostalgic even. But there is something unsettling when the top of the S&P 500 is populated by companies that are dinner table pariahs.

If Daniel-san is doing that awesome crane pose and kicking some of these FAANGs across the face, there are value-investing “Miyagis” out there watching from the sidelines, giving a slow nod of approval.

Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.


Make Investing great again …. one day? Part 2


By Aman Raina, Investment Coach, Sage Investors

Special to the Financial Independence Hub

In Part 1, I shared some thoughts on a recent report by the Ontario Securities Commission (OSC) outlining the challenges the financial services industry is having in getting Millennials to invest. The OSC report had a great opportunity to address those investing pain points, but like so many financial literacy initiatives, the messaging is not clear, consistent, and understandable. The report identifies solutions, yet they are separate and not integrated and use a lot of industry jargon that people just won’t connect with. They emphasize processes over results. What is the outcome we want Millennials to achieve with investing?

Another way?

In this post, I’d like to share from my experience as Investment Coach and as someone who works with people to develop their investing competencies, some approaches that I found have better motivated people and not just Millennials into becoming more engaged with investing. They address the pain points people have with expressed about investing which include; being scared of investing, feeling overwhelmed by the process, feeling paralyzed when trying to make a decision, and not knowing how to start and take that first step. These are my takes and perspectives. They are by no means the most definitive and all encompassing. 

The First Step: Define the investing path

The OSC report identified taking the first step in investing as a major pain point for people. For most people, after they have the epiphany that they should start growing their savings and invest, the most common series of events that occur include opening a brokerage account, buying some books or researching investing on the Internet or simply doing what their peers are doing. They buy a few stocks and some work out and some don’t and that’s where the fear pain point comes in.

The default for investing seems to be buying stocks, but does this really apply to everyone? In Part 1, I said that investing can be a very boring, repetitive, and time consuming process. Investing in stocks requires a major time commitment to analyze and evaluate stocks and managing the portfolio. For a lot of people, they really couldn’t be bothered to learn about investing because they have other more pressing priorities in their life … and that’s OK.

There are different investing paths we can take but ultimately we want to be on an investing path that compatible our life situation. If I don’t have the time to invest maybe I should consider working with a financial advisor, maybe use a robo-advisor service. Maybe buying a basket of Exchange Traded Funds (ETF’s) is a better path than buying individual stocks. 

Why are you investing?

It is critical that at the people define right away the appropriate investing path they want to travel. It begins with defining what the end of the path looks like (Why am investing?) as well how the road will be travelled. Will I travel it alone (Do-It-Yourself) or with someone else?

Once you’ve been able to answer these questions and defined a path, then you will have defined and reduced your scope of investments that you will use and begin work on building your investing competencies. Why learn about investing in stocks when you will be investing in ETFs?

The investment industry doesn’t really take the time to work with people on defining their investing path because they established a default that people that come to them want to invest in stocks when in reality they may have no interest or tolerance for it. The starting point is such a difficult pain point for many because once they begin to follow an investing path that was not compatible with their life and quickly they fell off it and into a ditch, it becomes harder to emotionally get back at it. These type of conversations need to happen before opening a broker account or signing up for an investing course.

Building investing competencies

I view financial literacy to be more about building competencies, more specifically investing competencies. From my experience, the people that have this investing thing pretty figured out possess three competencies. My role as an Investment Coach is to help people develop these investing competencies. 

Competency 1: Education – Principles versus Formulas

Once we have defined an investing path, we can target our learning to focus on developing our investing competencies in those areas. If we are committed to investing in individual stocks then we should focus our education on learning that area. Most investing education focuses on the mechanical aspects of investing and those mechanics which involve formulas, spreadsheets, and math trigger people’s pain points of finding investing overwhelming. Continue Reading…