All posts by Jonathan Chevreau

Retired Money: What retirement savers can learn from the finances of pro athletes

My latest MoneySense column looks at the seemingly enviable situation of professional athletes, and what us ordinary folk can learn about what it’s like to retire from a (typical) five-year career of earning big bucks, but then having a half century ahead of them. Click on the highlighted text to retrieve the full story: Why so many athletes run into financial trouble.

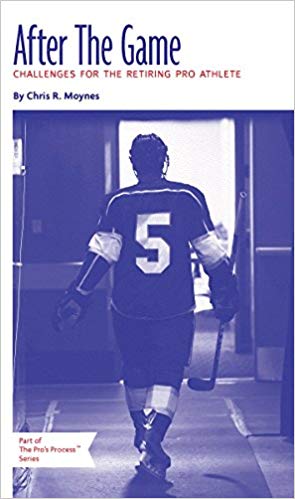
The article is based on an interview with Chris Moynes, a financial planner who specializes in managing money for NHL and other pro athletes, and reviews his book After the Game. it is available at Amazon.com or directly through his web site at www.onesports.ca, as is an earlier book called The Pro’s Process.

Most pro athlete careers average about 5.5 years. The median is just 4 years (so half have careers that last less than that) and of course a sudden critical injury could end it all at any moment. Of course, while it lasts the pay is astronomical compared to what mere mortals can generate in regular jobs: an average US$2.4 million per season. That means the average pro athlete will earn about $13 million over that short career. However, citing sportrac.com, Moynes says 200 of the 683 players in the NHL earn less than US$1 million per year, because the stats are skewed by the huge salaries of the biggest stars.

The 6 financial “Landmines” facing pro athletes

The opening chapter of After the Game outlines the six biggest “landmines” facing pro athletes. First is overspending and the combination of big paycheques spread over a short career. They seldom understand finances and often make poor investment choices, typically being prime targets for those selling “can’t miss” investments like nightclubs, casinos, real estate ventures and other private-equity type deals. Continue Reading…
Franklin Templeton Canada unveils suite of low-cost passive Regional and Country ETFs

On the heels of BMO’s entry into the low-cost asset allocation ETF space (see Hub blog here), one of the world’s largest active money managers has unveiled a suite of low-cost passively managed regional and country ETFs for the Canadian market.

Franklin Templeton Investments Canada today announced the expansion of its Franklin LibertyShares ETF offerings with its first suite of passive ETFs. (Franklin LibertyShares originally entered Canada in 2017 with four actively managed funds branded as Franklin LibertyShares).

The new passive funds gives investors exposure to a specific region or country at rock-bottom fees (below 10 basis points). It says (and I agree) that the management fees for these new Canada, United States, Japan and Europe (excluding U.K.) passive ETFs are amongst the lowest in the industry, ranging between 5 to 9 bps.

The company says these include the first Japan passive ETF and Europe (excluding U.K.) passive ETF available on a Canadian exchange. The ETFs are market-cap weighted.

In a press release, Franklin Templeton Investments Canada president and CEO Duane Green said: “With market-moving events like trade tensions and Brexit, investors and their advisors as well as institutional investors are looking to precisely act upon specific country and regional market views … These new passive ETFs provide Canadian investors with individual country and regional exposure options … at a very low cost.”

Here are the new ETFs and their ticker symbols:

Franklin FTSE Canada All Cap Index ETF (FLCD) invests primarily in equity securities of Canadian issuers, seeking to replicate the performance of FTSE Canada All Cap Domestic Index. The management fee is 5 bps.

Franklin FTSE U.S. Index ETF (FLAM) invests primarily in equity securities of mid- and large-capitalization U.S. issuers, seeking to replicate the performance of FTSE USA Index. Management fee is 7 bps.

Franklin FTSE Japan Index ETF(FLJA) invests directly or indirectly, primarily in equity securities of mid- and large-capitalization Japanese issuers, seeking to replicate the performance of FTSE Japan Index. Fee 9 bps.

Franklin FTSE Europe ex U.K. IndexETF(FLUR) invests primarily in equity securities of mid- and large-capitalization issuers in developed markets in Europe excluding the United Kingdom, seeking to replicate the performance of FTSE Developed Europe ex U.K. Index. Fee 9 bps. Continue Reading…

FP: RRSPs still have at least 3 advantages over TFSAs

My latest Financial Post column has just been published. It being the height of RRSP season, it looks at some well-known and some less well-known advantages RRSPs still have over the new kid on the block: TFSAs. Click on the highlighted text for the full story online: Three reasons why RRSPs still matter — and one of them you probably didn’t know. The article is also in Wednesday’s print edition on page FP6 under the headline RRSPs still matter despite rise of TFSAs.

The Tax-free Savings Account (TFSA), which was introduced just over ten years ago, is often described as the “mirror imaqe” of the RRSP. That is, the RRSP provides an upfront tax deduction by lowering your taxable income for the year you make the contribution. The TFSA does not, which can be a strike against it in some eyes; on the other hand, once you reach retirement, the TFSA comes into its own by NOT being taxable, and therefore not resulting in clawbacks of Old Age Security (OAS) benefits or (for very low-income seniors) the Guaranteed Income Supplement (GIS) to the OAS.

On the other hand, as many seniors are discovering to their chagrin, all those RRSP tax savings you enjoyed during your (hopefully) high-income earning years come back to haunt you: once the RRSP becomes a Registered Retirement Income Fund (RRIF) at the end of the year you turn 71 (the alternative is the unpalatable act of cashing it all out and being taxed then and there, or annuitizing), then you’ll be on the hook for forced annual — and taxable — RRIF withdrawals. Ottawa giveth and Ottawa taketh away.

But, as the FP piece argues, some decades can elapse between an RRSP contribution and the ultimate RRIF withdrawals, and when you add in the ongoing tax sheltering of an RRSP — on top of the upfront tax contribution — then the experts quoted in the piece believe the RRSP comes out, certainly if you’re at or near the top tax brackets.

Below is the arithmetic provided by Mathew Ardrey, wealth adviser at TriDelta Financial, which was too long to include in the FP version. He cites the example of someone who has $10,000 of income and can invest in either a TFSA or a RRSP:


Same tax rate
RRSP TFSA
Income before taxes to save $10,000 $10,000
Tax at 50% $0 ($5,000)
After-tax available to contribute $10,000 $5,000
FV with 5% return for 25 years $33,864 $16,932
Tax at 50% ($16,932) $0
After-tax withdrawal in retirement $16,932 $16,932
Lower tax rate in retirement
RRSP TFSA
Income before taxes to save $10,000 $10,000
Tax at 50% $0 ($5,000)
After-tax available to contribute $10,000 $5,000
FV with 5% return for 25 years $33,864 $16,932
Tax at 25% ($8,466) $0
After-tax withdrawal in retirement $25,398 $16,932
Higher tax rate in retirement
RRSP TFSA
Income before taxes to save $10,000 $10,000
Tax at 25% $0 ($2,500)
After-tax available to contribute $10,000 $7,500
FV with 5% return for 25 years $33,864 $25,398
Tax at 50% ($16,932) $0
After-tax withdrawal in retirement $16,932 $25,398


Tridelta Financial’s Matthew Ardrey

“The part of the example I would focus on, is what is a reality for many Canadians, their income is higher while they are working than in retirement. Because of this, there is a clear advantage of receiving the deduction at a higher marginal tax rate and paying tax in retirement at a lower marginal tax rate,” Ardrey concludes.

Foreign income taxed less harshly in RRSPs than TFSAs

But that’s not all! As the FP column mentions, there are at least two other advantages RRSPs have over TFSAs. One is that foreign income is taxed more in TFSAs than in RRSPs: Continue Reading…

Vanguard unveils 2 more Asset Allocation ETFs

A year after Vanguard Canada shook up the ETF industry with its ground-breaking suite of three Asset Allocation ETFs (VGRO, VBAL, VCNS) it today followed up with two new iterations, bringing the total to five.

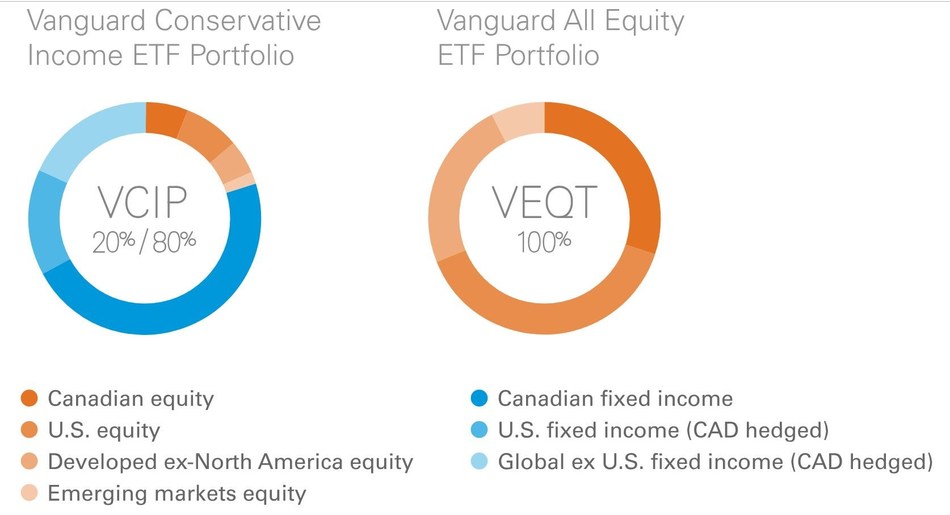
As you can see from the adjacent illustration, the two new ETFs include an all-equity ETF, VEQT; and a very conservative fund, VCIP, dubbed the Vanguard Conservative Income ETF Portfolio, which is 80% in fixed income. (The previous conservative entry, VCNS, was 60% fixed income). Both new ETFs begin trading on the TSX today.

Note that the color key above applies to BOTH funds: that is, Orange refers to four equity ETFs contained in both funds; blue refers to the three fixed-income ETFs that are present only in VCIP, since VEQT is 100% equity/orange. At least one sharp-eyed reader has noted the potential for confusion here.

In any case, the original suite of three ETFs were hailed by the financial press, including Yours Truly here and for the MoneySense ETF All-stars. The newcomers are further along the risk spectrum (100% equities) or further along the conservative income spectrum. And consumers have responded, injecting more than $1 billion into them, according to Kathy Bock, Managing Director of Vanguard Investments Canada Inc. Vanguard Canada now offers 39 ETFs, containing a total of C$17 billion in assets under management.

Here is the description of the two new ETFs contained in a press release:

Vanguard Conservative Income ETF Portfolio (TSX: VCIP) – The Vanguard Conservative Income ETF Portfolio seeks to provide a combination of income and some long-term capital growth by investing in equity and fixed income securities with a strategic allocation of 20% equities and 80% fixed income, made up of seven underlying Vanguard index ETFs.

Vanguard All-Equity ETF Portfolio (TSX: VEQT) – The Vanguard All-Equity ETF Portfolio seeks to provide long-term capital growth by investing primarily in equity securities with a strategic allocation of 100% equities, made up of four underlying Vanguard index ETFs.

Vanguard Canada head of product Tim Huver said “Canadian investors have embraced our ‘all-in-one’ asset allocation ETFs based on their sound portfolio construction, low-cost and simplicity. These ETFs have been among our most popular over the past year and we are committed to giving Canadians greater flexibility by offering two new investing options on both sides of the risk profile spectrum.”

Retired Money: Whether you’re a stock or a bond may determine when to take CPP/OAS

When to take CPP/OAS? My latest MoneySense Retired Money column passes on a fresh perspective on the old topic of whether you should take CPP or OAS early or late. You can find the full piece by clicking on the highlighted text here: Why aggressive stock investors should consider taking CPP early.

One of the main sources cited in the piece is fee-for-service financial planner Ed Rempel, who has contributed guest blogs to the Hub in the past. See for example Should I take CPP early? Some Real Life Examples or Delay CPP and OAS till 70? Some case studies.

Ed Rempel

When he recently turned 60, Rempel opted himself to take CPP himself because of course he considers himself primarily a “stock” when it comes to investing (using the concept from Moshe Milevsky’s book, Are you a stock or a bond?). He figures he can get good enough returns by investing the early CPP benefits that he will more than make up for the higher payouts CPP makes available for waiting till 65 or 70. Same with OAS, which he figures even balanced investors should take as soon as it’s on offer at age 65.

The corollary of this is that if you consider yourself primarily a fixed-income investor, then you should probably take CPP and perhaps OAS too closer to age 70. Compared to taking CPP at 65, taking it at 70 results in 42% more payments, while OAS is sweeter by 36% by delaying the full five years.

The MoneySense piece also quotes retired financial advisor Warren Baldwin, who chose to take CPP himself by age 66. Like Rempel and most financial advisors, Baldwin has a healthy exposure to equities. But he also cites a couple of other reasons for his decision. Baldwin, (formerly with T. E. Wealth), figures the value of the CPP fund to pay you the pension at age 65 is at least $250,000: more if you factor in its inflation indexing. The latter is an important consideration, especially for those (like Yours Truly), whose Defined Benefit pensions are not indexed to inflation.

Baldwin took his own CPP at 66, a year after his final year of full-time employment income. He did so “mainly for the cash flow and portfolio maintenance.”  But Baldwin has other reasons too. “I do not want to leave the CPP too long into the future in case the government changes the terms on it or the rate of income tax might rise … Look at how many changes they have made in the last 20 years.”

If a retiree’s marginal tax bracket jumped from 35% to 45%, Baldwin says deferred CPP would face a heavier tax load, while if benefits are taken earlier they would be taxed at more modest rates. And if retirees also have significant sums accumulated in RRSPs and RRIFs, the extra income might push up their Marginal Tax Bracket.

CPP survivor benefits also need to be considered

Warren Baldwin

Finally, Baldwin considers the “estate value” of CPP. “If two spouses have the maximum CPP and one dies, the survivor will not get much from the ‘survivor-ship’ aspect of CPP … So, if the ‘value’ of the CPP at 65 is in the range of $300,000, then if you die before you collect, there is quite a loss. Continue Reading…