All posts by Jonathan Chevreau

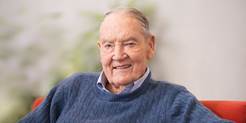
Vanguard announces the passing of founder John C. Bogle

The investment industry is saddened to learn of the passing of Vanguard founder John C. Bogle today. A true giant of the industry, Bogle was virtually the creator of index mutual funds and ETFs, and passive investing in general. Below is the press release issued today by Vanguard, which we reprint in full. I have added a few subheads and made only very minor edits.  

VALLEY FORGE, PA (January 16, 2019) — Vanguard announces the passing of John Clifton Bogle, founder of The Vanguard Group, who died today in Bryn Mawr, Pennsylvania. He was 89.

Mr. Bogle had legendary status in the American investment community, largely because of two towering achievements: He introduced the first index mutual fund for investors and, in the face of skeptics, stood behind the concept until it gained widespread acceptance; and he drove down costs across the mutual fund industry by ceaselessly campaigning in the interests of investors. Vanguard, the company he founded to embody his philosophy, is now one of the largest investment management firms in the world.

“Jack Bogle made an impact on not only the entire investment industry, but more importantly, on the lives of countless individuals saving for their futures or their children’s futures,” said Vanguard CEO Tim Buckley. “He was a tremendously intelligent, driven, and talented visionary whose ideas completely changed the way we invest. We are honored to continue his legacy of giving every investor ‘a fair shake.’”

Mr. Bogle, a resident of Bryn Mawr, PA, began his career in 1951 after graduating magna cum laude in economics from Princeton University. His senior thesis on mutual funds had caught the eye of fellow Princeton alumnus Walter L. Morgan, who had founded Wellington Fund, the nation’s oldest balanced fund, in 1929 and was one of the deans of the mutual fund industry. Mr. Morgan hired the ambitious 22-year-old for his Philadelphia-based investment management firm, Wellington Management Company.

Mr. Bogle worked in several departments before becoming assistant to the president in 1955, the first in a series of executive positions he would hold at Wellington: 1962, administrative vice president; 1965, executive vice president; and 1967, president. Mr. Bogle became the driving force behind Wellington’s growth into a mutual fund family after he persuaded Mr. Morgan, in the late 1950s, to start an equity fund that would complement Wellington Fund. Windsor Fund, a value-oriented equity fund, debuted in 1958.

In 1967, Mr. Bogle led the merger of Wellington Management Company with the Boston investment firm Thorndike, Doran, Paine & Lewis (TDPL). Seven years later, a management dispute with the principals of TDPL led Mr. Bogle to form Vanguard in September 1974 to handle the administrative functions of Wellington’s funds, while TDPL/Wellington Management would retain the investment management and distribution duties. The Vanguard Group of Investment Companies commenced operations on May 1, 1975.

The “Vanguard experiment”

To describe his new venture, Mr. Bogle coined the term “The Vanguard Experiment.” It was an experiment in which mutual funds would operate at cost and independently, with their own directors, officers, and staff—a radical change from the traditional mutual fund corporate structure, whereby an external management company ran a fund’s affairs on a for-profit basis.

“Our challenge at the time,” Mr. Bogle recalled a decade later, “was to build, out of the ashes of major corporate conflict, a new and better way of running a mutual fund complex. The Vanguard Experiment was designed to prove that mutual funds could operate independently, and do so in a manner that would directly benefit their shareholders.”

First index mutual fund in 1976

In 1976, Vanguard introduced the first index mutual fund — First Index Investment Trust — for individual investors. Ridiculed by others in the industry as “un-American” and “a sure path to mediocrity,” the fund collected a mere $11 million during its initial underwriting. Now known as Vanguard 500 Index Fund, it has grown to be one of the industry’s largest, with more than $441 billion in assets (the sister fund, Vanguard Institutional Index Fund, has $221.5 billion in assets). Today, index funds account for more than 70% of Vanguard’s $4.9 trillion in assets under management; they are offered by many other fund companies as well and they make up most exchange-traded funds (ETFs). For his pioneering of the index concept for individual investors, Mr. Bogle was often called the “father of indexing.”

1977: Direct to investors

Mr. Bogle and Vanguard again broke from industry tradition in 1977, when Vanguard ceased to market its funds through brokers and instead offered them directly to investors. The company eliminated sales charges and became a pure no-load mutual fund complex—a move that would save shareholders hundreds of millions of dollars in sales commissions. This was a theme for Mr. Bogle and his successors: Vanguard is known today for maintaining investment costs among the lowest in the industry.

A champion of the individual investor, Mr. Bogle is widely credited with helping to bring increased disclosure about mutual fund costs and performance to the public. His commitment to safeguarding investors’ interests often prompted him to speak out against practices that were common among his peers in other mutual fund organizations. “We are more than a mere industry,” he insisted in a 1987 speech before the National Investment Company Services Association. “We must hold ourselves to higher standards, standards of trust and fiduciary duty. Change we must—in our communications, our pricing structure, our product, and our promotional techniques.”

Mr. Bogle spoke frequently before industry professionals and the public. He liked to write his own speeches. He also responded personally to many of the letters written to him by Vanguard shareholders, and he wrote many reports, sometimes as long as 25 pages, to Vanguard employees — whom he called “crew members” in light of Vanguard’s nautical theme. (Mr. Bogle named the company after Admiral Horatio Nelson’s flagship at the Battle of the Nile in 1798; he thought the name “Vanguard” resonated with the themes of leadership and progress.)

In January 1996, Mr. Bogle passed the reins of Vanguard to his hand-picked successor, John J. Brennan, who joined the company in 1982 as Mr. Bogle’s assistant. The following month, Mr. Bogle underwent heart transplant surgery. A few months later, he was back in the office, writing and speaking about issues of importance to mutual fund investors. Continue Reading…
Retired Money: Is $1 million the magic number for Findependence?

My latest MoneySense Retired Money column was just published, focused on Monday morning’s release of the 2019 RBC Financial Independence in Retirement poll.

Click on the highlighted headline to retrieve the full article: The Magic numbers for your Findependence nest egg revealed.

And yes, they did use my term Findependence in the headline, which is a neologism I coined and is of course merely a contraction for Financial Independence.

May as well save a few keystrokes and/or syllables!

As I note in the column, I like the fact that RBC uses the term Financial Independence instead of the more commonly used “Retirement.” The two are not the same thing: it’s possible to be financially independent but not retired (that’s the case for myself and possibly many who frequent this website). But as I also note, it’s pretty hard to be retired if you’re NOT also financially independent. If the distinction eludes you, read my book Findependence Day.

In its poll, RBC can’t resist throwing out the figure $1 million as the level many non-retired Canadians believe is necessary to amass: not for “Retirement” per se, mind, but for what they call “a comfortable financial future.”

Call it what you will but RBC identifies four “top motivators” to accumulating such a nest egg: being debt-free, having things to make life more comfortable, having money to take part in desired experiences, and having enough to travel wherever you want.

BC needs $1 million for Findependence, Quebec just $427,000

So how much does it take to get there? Apparently, those in British Columbia need a little more than the rest of us: $1.07 million, compared to a national average of $787,000. Continue Reading…

FP: Enhanced CPP too late for Boomers but a boon for younger generations

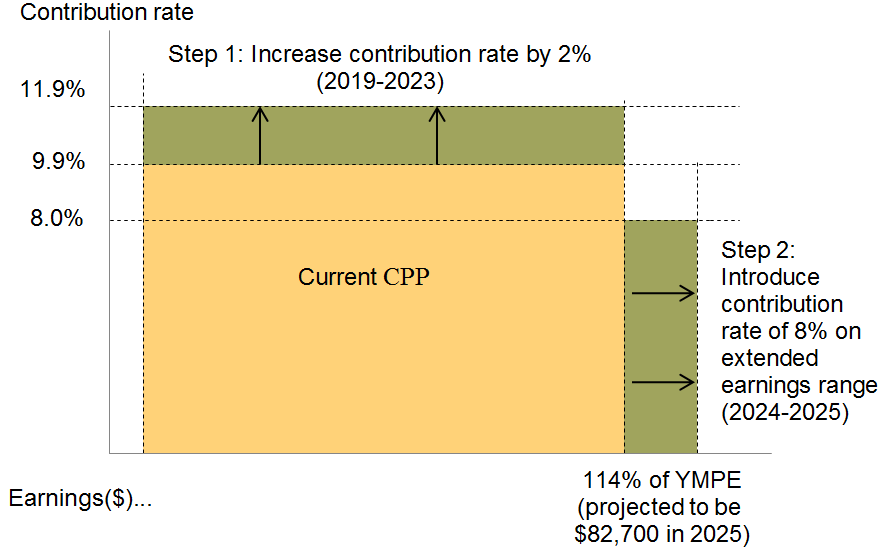
CPP enhancement will occur in two phases: fin.gc.ca

My latest Financial Post column has just been published, both online and on page FP6 of the Friday paper. You can click on the full piece by clicking on the highlighted headline: Everything you need to know about the enhanced CPP — from how much you’ll pay to how much you’ll get.

It summarizes the new enhanced Canada Pension Plan regime, which has (as of this month) started to show itself in slightly higher payroll deductions for both employers and employees.

Won’t fully kick in for 45 years

But as the piece explains, the enhanced CPP won’t fully kick in until 45 years from now, and most Baby Boomers will be retired before feeling any benefits beyond that of the normal practice of delaying CPP till age 70. And as one source explains, even the expanded CPP still isn’t as generous as Social Security is in the United States. Not only do they pay slightly higher payroll premiums to fund Social Security, but they also pay based on a much higher level of income.

U.S. Social Security still more generous

US contributions are up to US$132,900 in income, compared to about half that in Canada: a Year’s Maximum Pensionable Earnings limit (YMPE) of $57,400 in effect in 2019. CPP was originally designed to “replace” about 25% of the average worker’s income but the enhanced CPP will take that up to about 33.3% once it’s fully implemented. Gradually, the limit will rise to $65,400 (rounded down, 2019 dollars.)

While the full payout is 45 years away, benefits start edging up this year. Until now, the maximum CPP benefit at the traditional retirement age of 65 was $1,154.58 assuming earnings at or beyond the YMPE, according to Doug Runchey, of Vancouver Island-based DR Pensions Consulting.

The maximum benefit will be $1,207.83 in 2026, and eventually reach $1,753.78 by 2065. That’s a whopping $21,045 a year!

Too late for the Boomers

Still, Runchey says, “if you’re thinking of applying for your CPP earlier than 2025, the enhanced CPP will be of little value for you.”

As I said at the outset, that’s unlikely to be helpful for Baby Boomers at or on the cusp of retirement. Even so, the combination of an enhanced CPP and the decade-old Tax-free Savings Accounts (TFSAs) is something most Boomers wish they had when they were young!

For more on the enhanced CPP, go to the Government of Canada’s website here.


Your first resolution: add $6,000 to your TFSA

Welcome to 2019! Now that it’s January you can contribute $6,000 to your Tax-free Savings Account (TFSA), a program that’s now been around a full decade. That means couples can between them contribute $12,000.

The previous annual maximum was $5,500, but because of Ottawa’s promised inflation “bump” it has now officially been adjusted to $6,000. Recall that it was originally $5,000 when the program was introduced back in January 2009. Hard to believe it’s been ten full years now!

As the chart below illustrates, the cumulative limit (shown on the far right column) is now $63,500, which means a couple can between them invest $127,000. The first inflation adjustment was in 2014, when the limit reached $5,500. Under the Harper Tories it actually was almost doubled to $10,000 for calendar 2015 but one of the first things the Trudeau Liberal administration did was to reverse it back to $5,500 in 2016. It’s been $5,500 for three years until the new $6,000 limit that’s now in place.

2009$5,000$5,000
2010$5,000$10,000
2011$5,000$15,000
2012$5,000$20,000
2013$5,500$25,500
2014$5,500$31,000
2015$10,000$41,000
2016$5,500$46,500
2017$5,500$52,000
2018$5,500$57,500
2019$6,000$63,500

In the early years of the program, it might have been tempting to dismiss the original $5,000 as being an “insignificant” amount but obviously $63,500 is a hefty amount and anyone who has been contributing the maximum from the get-go should with tax-free growth have considerably more than that by now: I often hear from readers who have more than $100,000 in them, although December’s brutal stock market action is likely to have set them back a bit.

Maximize the time value of money

Why contribute the new $6,000 right now? I view this as a “time value of money” exercise and you may as well maximize the compounding effect of tax-free growth, assuming you are focusing on equities. Except for profoundly conservative investors, I’d recommend that Millennials and Generation X members use the TFSA primarily for Growth (equities or stocks, or equity ETFs). Baby boomers at or near Retirement could use Balanced Funds or ETFs (like VBAL from Vanguard, which is 60% stocks to 40% bonds, spread around thousands of securities around the world.) That’s likely the one we’ll use ourselves this week: we put the money into our discount brokerages on January 1st, but will actually invest it before the week is out, once markets are open.

Keep in mind that you can keep adding to your TFSA well into old age: I know a lady who is more than 100 years old who continues to do just that! That’s a lot of potential growth, which is why a balanced product may make sense. Of course, those who value interest income and wish to eschew stock-market risk can also use bond ETFs or GICs in their TFSAs: these days even 2-year GICs can be found that pay 3% or more.

Happy new year!

Positive if muted returns for most major asset classes in 2019, Franklin Templeton forecasts

Despite Tuesday’s 3% plunge in US stock markets, Franklin Templeton money managers are optimistic most major asset classes will deliver positive if muted returns in 2019.

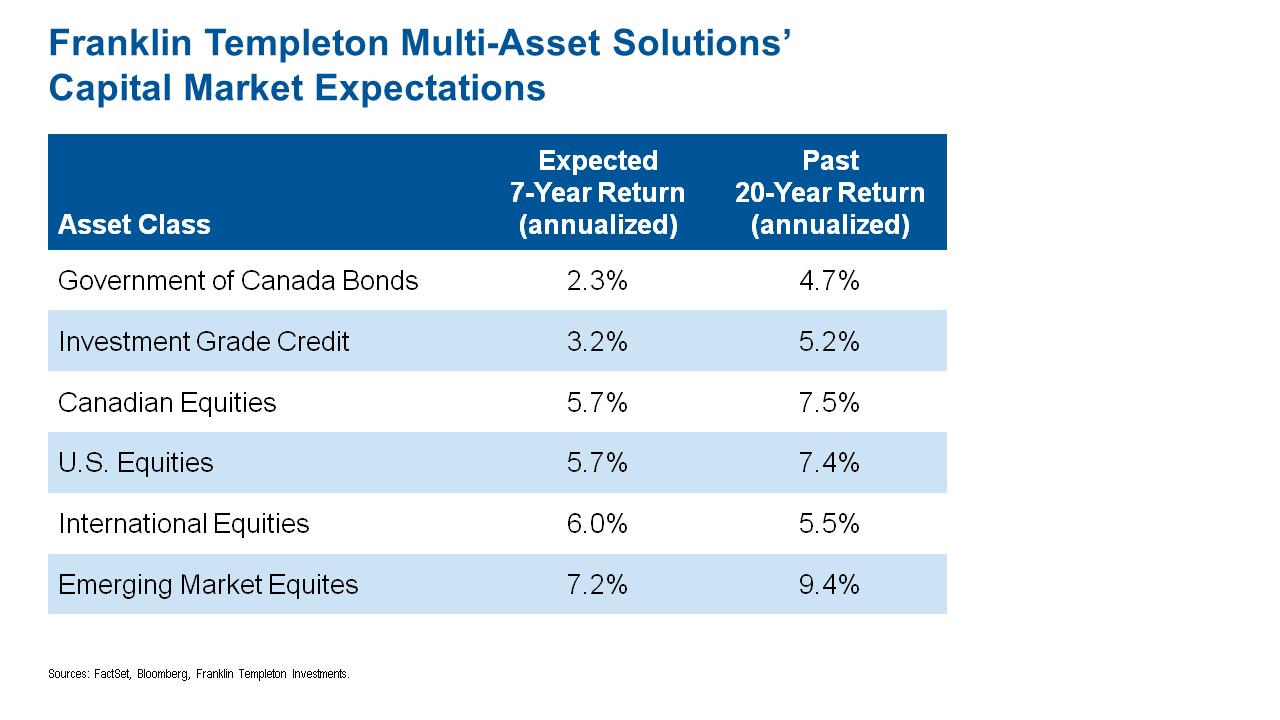
At the 2019 Global Market Outlook event in Toronto, William Yun, New York-based executive vice president for Franklin Templeton Multi-Asset Solutions, projected 7-year annualized returns for Canadian equities of 5.7%, compared to a 7.5% average the last 20 years [as shown in above chart]; 5.7% for U.S. equities (versus 7.4% historically), 6% for international equities (versus 5.5%), and 7.2 versus 9.4% for Emerging Markets. On the fixed income side, he is projecting 2.3% annualized 7-year returns for Government of Canada bonds (versus 4.7% historically the last 20 years), and 3.2% for investment grade corporate bonds (versus 5.2%).

All this is in an environment of continued desyncronized global growth (of 3%) and moderate inflation expectations. Long term, Yun is particularly optimistic about the long term growth of Emerging Markets equities, which at 5% is two-and-a-half times the 2% growth expectation for developed market equities. This optimism is based on positive population growth and labor productivity in Emerging Markets. Globally, inflation “remains muted” and “we don’t see many excesses in the global economy generally.” There are however, some excesses in the U.S. labor market.

More normalized interest rate environment

William Yun, Franklin Templeton Multi-Asset Solutions

Capital spending growth patterns are supportive and trending upwards since the 2016 US election, with the transition from very low interest rates post the financial crisis to a “more normalized interest rate environment.” The opportunity is to reinvest capital to more productive assets, as opposed to allocating to corporate share buybacks.

With respect to central bank balance sheets, markets are normalizing around the world, transitioning from excessive Quantitative Easing to Quantitative Tightening and shrinking balance sheets. Assets quadrupled at the Fed between US$1 trillion in 2008 to $4 trillion today as the Fed committed to buying bonds, with liquidity tapering off. He has similar expectations for the ECB, which has announced the ending of its QE programs, and it’s the same with Japan and China. “Central bankers are pulling back on Quantitative Easing.” There is a “restart of normalization in interest rate policy.”

Rising volatility 

Even as the Dow Jones Industrial Average was in the process of tanking almost 800 points Tuesday, Yun predicted rising volatility after a period of relative calm. In that environment, “investing passively [in index products] has been the way to go but we anticipate volatility returning.” With higher interest rates and more volatility, it may be a time for active management, Yun said, acknowledging his own firm’s expertise in active security management.

Emerging Markets gross domestic product (GDP) continues to rise relative to the rest of the world, from 40% in 1990 to 60% in 2017, and Yun expects that percentage to move higher still. The trend is driven by rising consumption growth for the middle class, which benefits industries like consumer staples and consumer discretionary stocks, technology and even investment management.

Emerging Markets are showing reduced reliance on developed markets, which are slowing. Whereas in 2007 eight of the top trade markets were with the United States, in 2017-2018 China has supplanted the US, with 8 of the top 14 destinations.

In short, Yun sees  a supportive global market for risk assets but lower returns: positive growth and moderate inflation, with increased volatility.

Ian Riach, Fiduciary Trust Canada

Ian Riach, Chief Investment Officer for Fiduciary Trust Canada and a senior vice president of Franklin Templeton Multi-Asset Solutions,  says it makes sense in this environment to make some “dynamic” (i.e. tactical) shifts to long-term Strategic Asset Allocation. Currently, the firm is underweight Canadian equities and Canadian bonds, because the loonie has been getting weaker and Canada is facing a number of challenges ranging from trade to energy to a shrinking manufacturing base, all of which “affects growth going forward.” In the short term, Riach expects short-term interest rates in the United States will be higher than in Canada, “given that they are growing more quickly than us.”

Flat yield curve

Even after the recent rate back-up, “we think Government of Canada bonds are expensive, Continue Reading…