Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

How small business owners can survive a security breach


By Gloria Martinez

Special to the Financial Independence Hub
Photo by Markus Spiske on Unsplash

There are myriad reasons why a malevolent actor would want to breach your small business’ data and info and/or attempt to defraud your company. Money (holding business info or operations ransom) is a big one, but your business also holds plenty of useful, sensitive data on customers, clients, business partners, trade secrets, and finances. Whatever the reason, data breaches are becoming the norm — not the exception — for small businesses around the world, and the cost can be substantial. Here’s what to do if you’ve been hit.

Plug the leak and and figure out what happened

If you are a network security pro or have your own in-house team that can perform this task, that’s great. However, the majority of small business owners feel lost and adrift following a security breach. The smart first step is to hire digital forensic specialists. These experts can do most of the technical work for you, from plugging up the initial breach point, tracking down the responsible parties (which is key for any sort of legal action), and finally doing the necessary legwork to shore up your defenses (so it won’t happen again).

This is also the time to contact your service providers. It’s highly unlikely that your breach exists in a vacuum. We’re talking your point-of-sale software company, internet provider, credit card processor, and accounting firm, so it’s wise to take the appropriate actions.

Boost security and consider Legal Representation

Your next step is to do what you can on your end to improve your data security. Employ the obvious, FTC-recommended actions like changing company passwords, security codes, and physical locks (yes, data breaches can occur when unauthorized people have actual, physical access to your workspace). Then, as the FTC suggests, “you may consider hiring outside legal counsel with privacy and data security expertise. They can advise you on federal and state laws that may be implicated by a breach.” Legal representation is vital for two major avenues — either taking action against those responsible or defending your business from liability (compromised personal data can put you in a serious legal pickle).

Make changes to prevent future breaches

A few solid ways to protect your small business from future security issues include separating personal and business accounts, beefing up your security and data permissions, and retraining employees about proper security protocols. The sad fact is that many security breaches are due to employees — whether malicious or unintentional. That’s why it’s absolutely critical that you take the time to carefully screen your hires to make sure they are reliable and trustworthy. This means holding quality job interviews where you ask the right questions to get an accurate sense of the candidates you’re vetting.

Notify those affected

Legal considerations aside (notification of a data breach may be forced based on state laws), being honest and upfront with your customers, clients, and business partners is always a good idea. It builds trust, for one. It also allows them to shore up things on their end, as security breaches are rarely just limited to the primary target.

Small businesses are generally easy targets for malicious actors for a variety of reasons. For one, they simply do not believe they are big enough to be hacked or breached. They also don’t have the time, money, or resources to devote to major cybersecurity. Knowing that you are vulnerable is half the battle, and the other half is staying calm but decisive when something does happen. Take these steps so you can recover and move on from a security breach.

Gloria Martinez loves sharing her business expertise and hopes to inspire other women to start their own businesses. Her brainchild is Womenled.org. Gloria’s vision is to help all women advance in the workplace and celebrate their achievements.
The Benefits of Travel

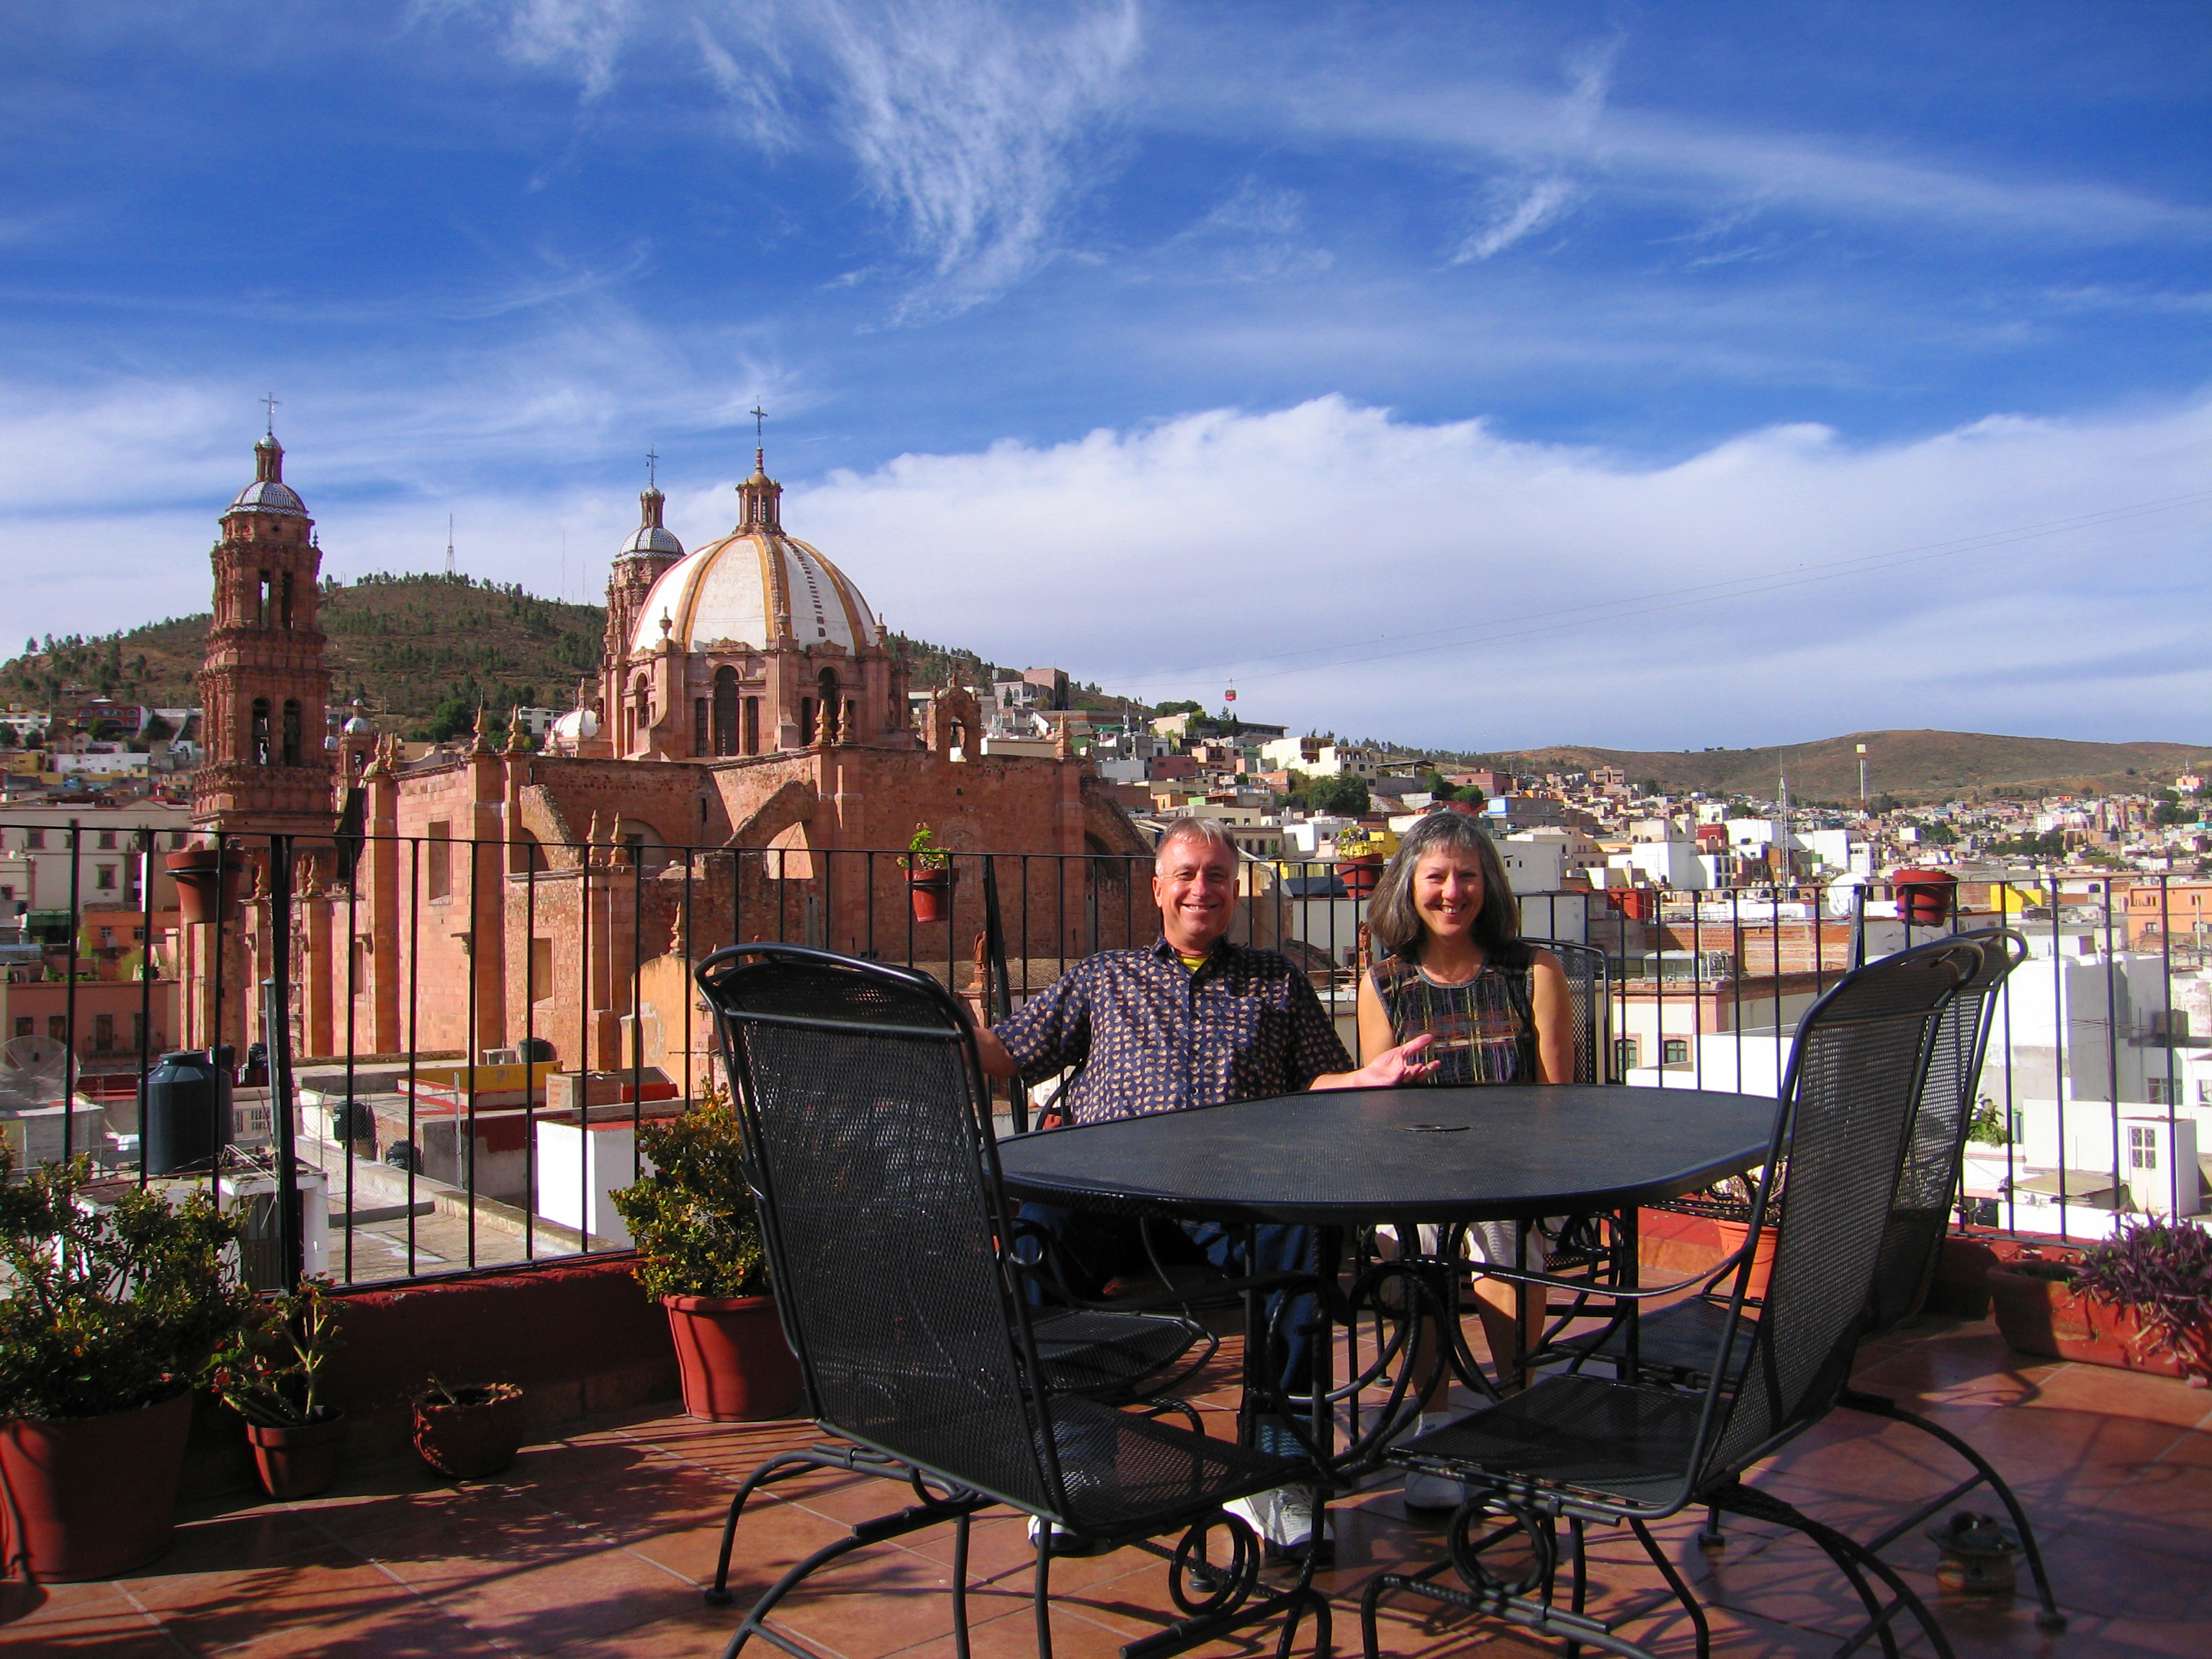
Billy and Akaisha take in the view from their hostel in Zacatecas, Mexico

By Akaisha Kaderli

Special to the Financial Independence Hub

We understand that not everyone likes to travel. No doubt it can be challenging, but there are significant benefits if you choose to enliven your routine with a little excursion.

Traveling makes you smarter

From the beginning of choosing a location, packing your suitcases and figuring out the logistics of who will water your plants or sit with your pet, traveling takes you out of your routine. Anything new and different like this that engages your brain causes new neurological pathways to grow.

Learning a new language, taking a cooking or painting class while on your trip and meeting new people all place you in unique situations, and your brain strengthens.

Traveling is healthy for you!

Traveling makes you strong

For some people, all these new patterns outside the everyday routine can be perceived as a hassle. Yes, and that’s good! We learn flexibility, creativity and self-reliance. Those are great attributes to have and they are useful to daily living.

Flexibility of mind, finding new solutions to new challenges and our sense of who we are and how we cope all get stronger.

Traveling helps you become an interesting story teller

When things don’t go according to plan, those seemingly challenging circumstances make for the best stories!

If everything goes perfectly on your trip or vacation, and people ask “How did you enjoy yourselves? How was your trip?” then all you can say is “Great!” Continue Reading…

U.S. Growth stocks: You’d better be Seabiscuit

This is Part 2 of a two-part blog series on the prospects for Growth and Value Stocks.

Read Part 1 Growth Stocks: Where’s the Beef?

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub

When your starting point is a 1.4% dividend yield,1as is the case with the S&P 500 Growth Index, the group of stocks that make up the basket need to have long-term dividend growth that performs like Seabiscuit, the super horse. No tripping out of the gate or getting bumped in the stretch.

Latching on to the concepts in my white paper, Dividend Growth’s Drivers: Picking Apart Quality, we present figure 1, which shows the interrelationship between the percentage of earnings that are retained (as opposed to paid out as dividends) and the return on equity (ROE), which is net income as a percentage of shareholders’ equity.

This relationship is thedriver of dividend growth, and as the years go on, concepts like figure 1 have become core tenets of second-decade WisdomTree.

Figure 1: The Critical Equation

The Critical Equation

Figure 2 uses the critical equation to calculate long-term dividend growth at prevailing profitability levels.

As it stands, the S&P 500 Growth Index’s 23.2% ROE implies long-term dividend growth of 16.8%. That could happen, yes. Anything canhappen. But here’s a better idea: expect downward revisions instead.

Figure 2: Implied Dividend Growth Estimate 

Implied Dividend Growth Estimate

After all, look at the historic record in figure 3. There isn’t a single five-year period that had growth stocks’ earnings running forward at a 16.8% clip, not even in the roaring 1990s. In contrast, value stocks’ implied dividend growth is on planet Earth. 

Figure 3: Dividend Growth Rate, 5-Year Periods, 1995–Present 

Dividend Growth Rate 5Year Periods 1995Present

Does anything jump out in figure 3? Look at the dividend growth experience of growth and value from 2010 to 2015 and from 2015 to the present.

Those growth stocks start to look less like Seabiscuit and more like also-rans if recent years are any indication. Granted, value indexes are dominated by banks, and the period from 2010 to 2018 was characterized by the benefit of their reinstated dividends. Nevertheless, if growth stocks were only able to increase their dividends at a high single-digit rate during this period of irrepressible economic expansion, what happens if recession hits? Let someone else pay 22 times earnings to find out. 

Slow and Boring? Better than Growing Out of 1%

The S&P 500 Value Index has a dividend yield that is about double that of the S&P 500 Growth Index (2.7% vs. 1.4%). This kind of gap makes it nearly impossible for the latter index to ever grow out of its valuation.

If U.S. growth could not differentiate its … ahem … dividend growth relative to value from 2010 to 2018, what makes anyone think the next several years will be different? For growth stock skeptics, the WisdomTree Fund that hits value is the WisdomTree U.S. High Dividend Index ETF (HID/HID.B). 

It retains 38% of its earnings, pays out the other 62% as dividends and has an ROE of 13.5%. That ROE is satisfactory enough. Using the “critical equation,” it has long-term implied dividend growth of 5.1%, which is less than the levels of the S&P 500 Growth Index. But when the starting point is a 1.4% forward dividend yield, companies that populate indexes like the S&P 500 Growth Index would have to run up their dividends at a 15% or 20% annual pace for a long time before the math even thinks about shifting in their favour.2

For investors who do not want to commit to value because they keep getting burned, a fund like the WisdomTree U.S. Quality Dividend Growth Index ETF (DGR/DGR.B), which tracks the WisdomTree U.S. Quality Dividend Growth Index CAD, seeks to target companies that rank well on our ROE x earnings retention framework. 

Critically, its dividend weighting methodology also checks valuations at the door. That gives it a starting dividend yield of 2.7%, about 130 bps more than the S&P 500 Growth Index. It also has an explicit screen for ROE and return on assets (ROA). Its 15.8x forward earnings multiple is 3.3 multiple points below the S&P 500 Growth Index.

Over the next 5 or 10 years, we’ll take DGR.B or HID.B over S&P 500 Growth Index. This is where the rubber meets the road, when the cap-weighted U.S. large-cap growth indexes start to be priced like they’re Seabiscuit, when in reality they’re an underlay.

1Sources: WisdomTree, Bloomberg, as of 11/15/18.

2Sources: WisdomTree, Bloomberg. Unless otherwise stated, all data in this blog as of 11/15/18.    


Jeff Weniger, CFA serves as Asset Allocation Strategist at WisdomTree. Jeff has a background in fundamental, economic and behavioral analysis for strategic and tactical asset allocation. Prior to joining WisdomTree, he was Director, Senior Strategist with BMO from 2006 to 2017, serving on the Asset Allocation Committee and co-managing the firm’s ETF model portfolios. Jeff has a B.S. in Finance from the University of Florida and an MBA from Notre Dame. He is a CFA charter holder and an active member of the CFA Society of Chicago and the CFA Institute since 2006. He has appeared in various financial publications such as Barron’s and the Wall Street Journal and makes regular appearances on Canada’s Business News Network (BNN) and Wharton Business Radio.

Tracking your financial health in Retirement

Sailing in Boracay, Philipplnes

By Billy and Akaisha Kaderli

Special to the Financial Independence Hub

No matter what stage of life you are in, it is important to know your financial health. This is not something you do just around income tax time but throughout the year. It’s good to check in at least monthly or, as we do, daily. The same as any successful business must know their income and liabilities, so should you.

Today there are plenty of free online tools that can help you, but we are old school and prefer to be able to check and edit our data anywhere in the world and at any time regardless of an internet connection. We have done this since we retired in 1991. Back then we used a paper notebook and pen, but today we created a spreadsheet using an Excel program that is on most computers sold today.

How it works

Throughout the day as we spend money we keep a mental note of the cost. Then, usually in the evening while winding down, we enter the data into our spreadsheet. We created categories such as housing, food, dining, transportation, donations, healthcare, and so on. Each of those entries then gets automatically added giving us a total for the day. That number is added to all of the previous entries and then divided by the day number in the year, 1 through 365, giving us a daily average.

Utilizing this system we can adjust the entries using local currencies, therefore knowing what we are spending in Mexican Pesos, Thai Baht, Vietnamese Dong, Guatemalan Quetzales or the money of any place where we are traveling. While this figure can easily be converted to dollars if we want, we prefer to think of our costs in the currency of our host country. This keeps our spending at the perspective of the natives instead of distorting it by thinking in Dollars.

This information is important

Once you know how much you are spending per day you can utilize this information to adjust spending accordingly if necessary. You are in control of your outflow at this point, and you can make changes in real time.

Net worth: What is it?

Another important tool for understanding your financial health is calculating your net worth. This number is derived by adding up all of your assets minus your liabilities. Do you own a house or rentals? Figure out what they are worth, then subtract out what you owe and this equates to the equity you have. It is important to use realistic numbers knowing that if you sold today, there would be fees and expenses involved as well as taxes to be paid. Do you have cars? Even though they are a depreciating asset, meaning they lose money over time, you still have some value there. How about retirement accounts? IRAs or RRSPs, 401(k)s or Defined Contribution pensions, regular banking and brokerage accounts, credit-card and student loan debt: all need to be factored into the equation.

This information is a powerful retirement tool

Now that you know your net worth and what you are spending per day, you can take further control of your future by figuring out what percentage of your net worth you are spending. Continue Reading…