Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

Forget the Trade War, already: China is cutting Taxes

By Jeff Weniger, WisdomTree Investments

Special to the Financial Independence Hub

The market’s obsession with trade wars may finally be exhausted and priced in. Move on to the next market mover: massive Chinese tax cuts, which should aid the WisdomTree ICBCCS S&P China 500 Index ETF (CHNA.B), our tracker exchange-traded fund for the country.

Sure, China exported US$457 billion (C$597 billion) of goods and services to the U.S. in the year through June, and some fraction of those exports is at risk from a deterioration in Sino-U.S. relations. But engage a drastic scenario: lop off US$200 billion or US$300 billion from that figure. Even if that happened, most of that sum wouldn’t even disappear; it would be sold elsewhere, maybe inside China, at concessionary prices. But even suspending logic and having it all vanish, is it really doomsday for China’s US$14.1 trillion economy (US$25.2 trillion at purchasing power parity)? We don’t want to minimize the importance of trade conflicts, but the airtime given this topic is hysterical.

When Obama was in office, many conservatives and free market acolytes convinced themselves he would destroy the U.S. economy, so they ignored massive fiscal and monetary stimulus — the data — and missed the equity bull market. Emotions ruled; logic lost.

Now it’s happening with Trump. Among some investors, emotions are defeating data. The recent Bank of America Merrill Lynch fund manager survey pointed to a trade war as the market’s biggest risk. Some investors so badly wish Trump to fail that, like conservatives during the Obama years, positive news is simply ignored. Forget Japan’s major trade deal with the EU, ink still wet. Forget Trump’s meeting with Jean-Claude Juncker, European Commission president, where they agreed to work toward zero tariffs. The end is near!

Astute investors need a sober, facts-based thesis.

A Thesis without Emotion

A more realistic take on matters is that China finds itself isolated, unable to pair with Moscow in a two-country geostrategic counterbalance to the West. This forces Beijing to backtrack on intellectual property theft, inordinately high tariff levels, state subsidies and dumping because of its weak bargaining hand.

The pain must be offset, so Beijing gives the market that for which it aches: trillions of dollars in tax cuts at the business, product and personal income tax levels. Yes, Trump’s ability to stir the pot is important, but mathematics matters.

Chinese equities are the play here.

Bold actions

We calculate that many Chinese will see their personal income tax liability fall by half or more, effective January 1, 2019. Add to this our estimate of nearly US$500 billion in value-added tax cuts over the next decade, with still-in-the-works business tax relief on top, which would be another US$132 billion to $138 billion if activity grows at a pace of 6% to 7%. For perspective, Beijing’s Lehman-era US$586 billion spending package, hypothesized by some to be the reason the Global Financial Crisis ended, is smaller than 2018’s total announced tax cuts, if we calculate them over several years. This is this year’s big story.

Income Tax Scenarios: Implications for everyday Chinese

The proposed personal income tax code changes are staggering (figure 1). Exemptions and the minimum bounds for the 10%, 20% and 25% brackets are set to gap higher, while tuition, medical and mortgage deductions add to the savings.

Figure 1: China Personal Income Tax Code 
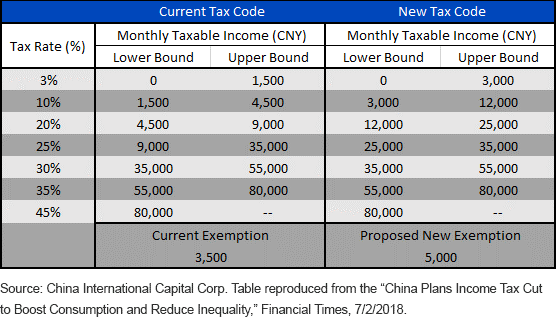
If these become law in October and are implemented in January, someone making CNY15,000 per month (C$2,906), a wage that is common in a city like Shanghai, where 2017 median monthly income is $2,048, would see their monthly taxes cut by CNY1,080 (C$209).1The person making half that amount, or CNY7,500 per month, which is short of the metropolitan median, would save about C$500 per year on an income of C$17,437. This is serious.

Chinese Equity Valuations

With many Chinese equity markets hammered this year, the S&P China 500 Index’s forward P/E multiple has fallen to 11.7, a sharp discount to the S&P/TSX Composite Index of Canadian equities (P/E of 15.8).2  Continue Reading…
What to consider before converting your RRSP to a RRIF

By David Mortimer

(Sponsored Content)

Congratulations, you’ve retired! After many years of working and saving, the time has finally come for you to travel, spend more time with family, or do any number of activities you may not have had time for when working 40+ hours per week.

One of the first decisions you now need to consider is when to convert your RRSP to a RRIF? Technically, you are required to do so by December 31stof your 71styear, but many retirees find themselves wondering if they should do so early. Here are some things to consider before making the conversion from RRSP to RRIF.

Am I retired for good?

It’s important for people to consider whether they’ve retired for good before converting their RRSP to a RRIF. Remember it may not be so easy to turn back  after making the conversion from RRSP to a RRIF so if you are planning to return to work, even part time, you may find yourself with a tax problem if you’re working and taking an income through your RRIF. The taxes you end up paying could easily wipe out any financial gains you would make from working part time, not to mention it would not allow you the option to continue contributing to your RRSP (once converted to a RRIF), which will further reduce your taxes – providing of course you are under the age of 72!

Thinking you might like to keep busy with a part time job? Consider supplementing your finances with your tax-free savings account and non-registered investments before touching your RRSP. If you draw these out first while still working, there will be fewer tax consequences. You may also be better off taking money from your RRSP on a short-term basis rather than officially converting to a RRIF right away.

When it comes down to it, don’t collapse your RRSP into a RRIF until you’re fully retired, and have considered all your potential income streams and their potential tax consequences.

What income streams are available to you?

When making the decision on when to convert your RRSP to a RRIF, it’s important to look at how you will be funding your retirement. Do you have a workplace pension you will be receiving? What about Old Age Security (OAS) or Canada Pension Plan (CPP)? Keep in mind that your OAS has certain claw-back provisions once your income exceeds a certain threshold. Continue Reading…

Court decision on sold data access means more transparency for home buyers and sellers

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

A seven-year legal battle between the Toronto Real Estate Board (TREB) and Canada’s Competition Tribunal has come to an end, ushering in a new era for Toronto real estate data access.

On August 23rd the Supreme Court of Canada stated it would not hear an appeal from TREB to keep past sold real estate data private, following rulings from both the Tribunal and the Federal Court of Appeal that required it be made available online.

This means TREB’s online brokerage members, such as Zoocasa, are now allowed to display the historical data for individual real estate listings to site users with password-protected accounts. This information includes a home’s original listing price and sale price, its 10-year sales history, and whether it has ever had a terminated listing. Previously, clients could only receive this information once they were under contract with a real estate agent, who could provide it to them over the phone, by fax, or in person.

The move is being widely hailed as a victory, both for those who work in the real estate industry and for prospective buyers and sellers’; but how will it change today’s real estate market?

A boon for Buyers

Perhaps the biggest benefit for buyers will be the improved transparency around home prices. While having access to the data is unlikely to prevent bidding wars, it will mean shoppers will have a better idea of what condos and houses for sale are truly worth before they put in an offer.

It will also decrease price lowballing, a strategy in which sellers list their homes for a much lower amount than they expect to receive. This piques the interest of buyers looking for a great deal, often leading to multiple-offer situations and hyper-inflated prices. It’s an especially common tactic in hot markets, such as on the Toronto or Vancouver MLS, and a constant source of frustration for buyers trying to find homes that are actually within their budgets.

Now, buyers will be able to see what comparable homes are selling for in the same neighbourhood, and whether their desired listing has been priced accurately.

Greater strategy for Sellers

This doesn’t mean sellers will receive the short end of the stick: they’ll now have more information than ever to inform their decision to list. Continue Reading…

How investing makes it easier to achieve Financial Independence

By Gary Bordeaux

Special to the Financial Independence Hub

If you are looking for a way to secure your financial future, learning how to invest your money can help accomplish that goal. There are a variety of investment vehicles that can be tailored to fit your needs, timeline, and risk tolerance.

Let’s take a look at some of the specific reasons how investing helps a person obtain financial independence (aka “Findependence”).

Make money both today and tomorrow

If you are interested in generating a steady income from your investment portfolio, you can buy dividend stocks or a REIT (Real Estate Investment Trust). You make money today by receiving a dividend payment every month or quarter. You make money in the future by holding the security as it appreciates in value. When it reaches what you feel is the height of its value, feel free to sell it and lock in a profit. It is also possible to hold stocks in a trust that can benefit children, grandchildren or other beneficiaries after you pass on.

Obtain returns greater than the Rate of Inflation

Thanks to inflation, a dollar that you hold in your hand today will be worth the equivalent of 98 cents a year from now. This is because the price of goods will increase by an average of 2 per cent per year. In some cases, inflation can reach 4 per cent or greater in a given 12-month period.

As a general rule, stocks will appreciate by about 7 per cent per year, and that amount is higher if a stock offers a dividend. What this means is that you are increasing your net worth above what it takes to keep up with cost-of-living increases. Over a period of years or decades, you could accrue tens or hundreds of thousands of dollars that can be used to enhance your lifestyle.

Improve your chances of owning a home

Let’s say that you are looking to buy your first house. You could decide to buy a single-family unit with a monthly mortgage of $1,000 that you are responsible for paying on your own. However, another option is to buy a duplex that you can both live in and derive income from. At the very least, having a tenant living in the other half of your home will decrease the monthly mortgage payment.

The money that you save can then be used to improve the home or make other investments. If you make improvements to a property that is used for rental purposes, it may be possible to write off the amount of those repairs on a state or federal tax return. Continue Reading…

5 financial fitness tips to help becoming #RetireReady

By Jenny Diplock

Special to the Financial Independence Hub

As any personal trainer will tell you, a new fitness routine starts with a personalized plan and a target goal. And to improve performance, you need to train: especially in the off-season. Taking a similar approach to your retirement contribution goals can help you feel confident you’re #RetireReady.

In fact, according to a recent survey from TD, 79 per cent of working Canadians agree that reviewing their retirement contribution goals outside of RSP season is a good idea.

But even with these good intentions, the data shows just 40 per cent of working Canadians contribute regularly to their registered Retirement Savings Plans (RSPs) through pre-authorized contributions, 20 per cent don’t contribute to retirement savings at all, and nearly a third of working Canadians feel stressed out during the February RSP season.

When it comes to saving for retirement, contributing to your RSP once a year is like running a marathon without the right training. Because you’re not in the habit of saving, trying to come up with one large contribution amount just before the annual RSP deadline can be harder than contributing smaller and more manageable amounts throughout the year, potentially putting additional pressure on the rest of your finances.

To help improve your retirement readiness year-round: Continue Reading…