Hub Blogs

Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.

The Ageless Generation

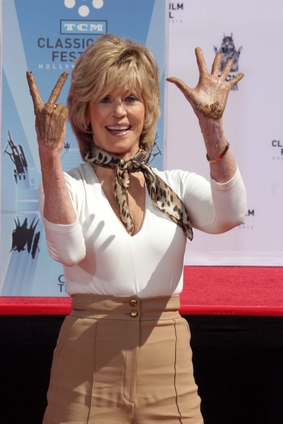
Jane Fonda at the Jane Fonda Hand And Foot Print Ceremony as part of the 2013 TCM Classic Film Festival, TCL Chinese Theater, Hollywood, CA 04-27-13
Jane Fonda in 2013

Are the Baby Boomers part of the Ageless Generation?

Many of us seem to act as if that were the case but there’s little doubt most of us feel younger than we appear. To me, the poster child for this ageless generation is Jane Fonda, whose famous workout videos appear to have held her in good stead in her personal twilight career.

(Technically, since she was born in 1937, Jane Fonda is not a post-war baby boomer but her spirit certainly seems to epitomize the zeitgeist of the generation that came soon after her).

If you get Netflix check out the recently released series Grace & Frankie, where  Fonda plays a 70-year old recent divorcee: even though she herself is actually 77! Equally vibrant are her aging costars: Lilly Tomlin, Martin Sheen and Sam Waterston (best known as the prosecutor on Law & Order). Tomlin is 75 and the two male co-stars are 74.

Medical advances will transform the global economy
41X0rgzpqKL._SY344_BO1,204,203,200_
Amazon.com

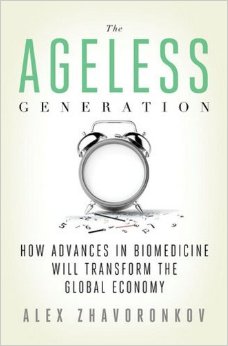
The Ageless Generation also happens to be the title of a recent (2013) book by Dr. Alex Zhavornonkov, director of the Biogerontology Research Foundation and founder of the International Aging Research Portfolio. It’s one of about a dozen books I read in recent months in preparation for a talk on Longevity that I gave on Monday to the National Elder Planning Issues Conference in Niagara Falls.

The book’s subtitle summarizes the gist of it: How advances in biomedicine will transform the global economy. Since the focus is on the United States, it will come as no surprise that  Zhavornonkov believes breakthroughs in extending Longevity can only make a shaky Social Security and Medicare system that much more fragile in the United States, and by extension their equivalent programs in other advanced nations.

Pressure on Social Security & Medicare

Continue Reading…

What’s on the Menu? Engineering a better outcome for investors

Depositphotos_50578301_xsBy Robb Engen, Boomer & Echo

Special to the Financial Independence Hub

When I worked in the hospitality industry our hotel group placed a large emphasis on the profitability of its restaurants and catering departments. Considerable effort was made to drive overall food costs down while at the same time creating a sales culture that pushed the highest margin items in order to boost revenue.

One of the most effective ways to do this was through a process called menu engineering. Before hitting it big by turning around struggling nightclubs in the reality show Bar Rescue, Jon Taffer was a highly sought-after speaker and consultant in the hospitality industry. At the top of Taffer’s legendary revenue growth plan for restaurants and bars is the concept of menu engineering. Here’s how it works:

Restaurant owners divide their menu items into four main categories:

  • Stars – Stars are extremely popular and have a high contribution margin. Ideally Stars should be your flagship or signature menu items.
  • Plow horses – Plow horses are high in popularity but low in contribution margin. Plow horse menu items sell well, but don’t significantly increase profit.
  • Puzzles – Puzzles are generally low in popularity and high in contribution margin. Puzzle dishes are difficult to sell but have a high profit margin.
  • Dogs – Dogs are low in popularity and low in contribution margin. They are difficult to sell and produce little profit when they do sell.

Continue Reading…

Is Investing an Art or a Science?

bradley_steiman
Bradley Steiman, DFA (ifa.com)

Here’s my latest MoneySense column, titled Is Investing an Art or a Science? It may serve as a primer about DFA index mutual funds, which was last addressed at the Hub in March by financial planner Paul Philip in this interview with Peter Grandich.

For convenience and one-stop shopping purposes, you can also find the piece below, with a photo and subheads added: Continue Reading…

Eternal Truth #3: Get out of Debt

Depositphotos_35796001_xs
Eternal Truth #3

The third of the seven-part series on the Eternal Truths of Personal Finance is in the Wednesday Financial Post today, as well as online under the headline The No. 3 eternal truth of personal finance: Pay off Your Debt First.

Part 1 ran last Wednesday and Part 2 on Saturday. You can find links both in the Hub’s weekly wrap on Saturday.

As I noted this morning on Twitter, it’s ironic that Christie Blatchford’s piece on Mike Duffy today revealed that the beleaguered former broadcaster was unable to live within his means, despite drawing a not-inconsiderable salary of $120,000 a year: Audit shows Mike Duffy was unable to live within his means.

Not for nothing did we kick off the Eternal Truths series with Live within your means!

A Mother’s View on Increased TFSA Limits

By Michael Drak,

Special to the Financial Independence Hub

“I want you to get up right now. Sit up – Go to your windows – Open them and stick your head out and yell – I’M AS MAD AS HELL AND I’M NOT GOING TO TAKE THIS ANYMORE!

Then we’ll figure out what to do about the depression and the inflation and the oil crisis. But first, get up out of your chairs, open the window, stick your head out, and yell, and say it I’M AS MAD AS HELL, AND I’M NOT GOING TO TAKE THIS ANYMORE!”

The above scene is from the 1976 film, Network, and my mother thought it might be an appropriate response to Jonathan [Chevreau]’s recent article on TFSAs:  “Memo to Liberals: lots of older middle-class Canadians have $10,000 TFSA capital “lying around.”

Here is her story.

‘I don’t have to tell you things are bad. Everyone knows things are bad.”

My mother currently resides in a retirement home and is able to afford the hefty monthly rental payments via a combination of CPP/OAS and unregistered savings. Continue Reading…