Hub Blogs contains fresh contributions written by Financial Independence Hub staff or contributors that have not appeared elsewhere first, or have been modified or customized for the Hub by the original blogger. In contrast, Top Blogs shows links to the best external financial blogs around the world.
My latest MoneySense Retired Money column looks at the imminent retirement of The Wealthy Barber himself: David Chilton. You can find the full column here: The Wealthy Barber retires.
My Retired Money column has focused on individual retirements now of Rob Carrick and blogger Mark Seed. Like Chilton, these people are younger than myself: I describe myself as only semi-retired, which is how I view Carrick and Seed. On his two-year-old The Wealthy Barber podcast, Chilton has now twice interviewed Carrick about his Retirement and also about his views on the high costs of housing.
As my MoneySense interview with him clarifies, Chilton views his transition as being closer to the traditional “Full Retirement” than the more gradual semi-retirement that Carrick and I are practicing. My view of Traditional Retirement is leaving a full-time salaried employee relationship and all that entails: commuting to a central place, bosses and meetings, taxes withheld at source, etc. Of course, Chilton has seldom if ever been an employee: he’s been a self-employed author and public speaker almost from the get-go. But as he reveals, his successful speaking career meant doing a lot of business travel and committing his time in advance: something he now wishes to reduce in order to have more personal freedom.
When and if he does pack it in in December, it will end an intense few years where he “aggressively” participated again in the Canadian personal finance content space that he helped pioneer in the first place.
Apart from public speaking, which he will cut back on in 2027, Chilton launched a successful biweekly podcast on YouTube that soon became weekly, promoted through video shorts on Facebook and TikTok. I can see how weekly podcasts could constitute almost a full-time job in itself so it should be no surprise that he will wind that up at the end of the year, despite the fact many around him would like to see it continue in some form.
Rewritten Canadian edition of The Wealthy Barber took longer to do than the original
The other big push he made was a massive two-year extensively rewritten 2025 Canadian edition of the book that made his career when he published it at age 27 in 1989. Chilton says it took him longer to revise (rewrite) the new edition than to write the original! His focus is on Canadians 45 years old or younger, many of whom are struggling to get a toehold in the housing market (which includes my own daughter). Continue Reading…
Not every high-paying job accelerates your journey to Financial Independence (FI). The real difference lies in spotting a company with a modern, FI-friendly career path that combines strong compensation with flexibility, autonomy and genuine growth opportunities. These organizations pay well while creating conditions that allow you to build wealth faster and on your terms.
What a FIRE-Friendly Career Path really means
A Financial Independence, Retire Early (FIRE) career path demands more than raw earning power. In addition to high compensation, you need a strong work-life balance that leaves room for side income and a culture that values autonomy over micromanagement. A balanced lifestyle supports job satisfaction and engagement, keeping work sustainable and fulfilling.
The most FI-friendly companies offer predictable schedules, remote flexibility and trust-based management. These conditions allow you to maintain side projects, develop new skills and preserve the mental energy that strategic financial planning requires. Companies with healthy work hours allow daily recovery time that supports individual well-being and job performance.
Look for Cultures that prioritize Results and Flexibility
The clearest signal of a positive company culture is a focus on results and deliverables. Organisations that measure success by output rather than desk time create environments in which high performers work efficiently and reclaim hours for wealth-building activities.
Look for flexible scheduling policies, outcome-based performance metrics and leadership that respects boundaries. Presenteeism cultures do the opposite, rewarding visible activity over actual productivity and forcing you to trade time for appearance. The cost is measurable in hours you could allocate to wealth-building.
Decode a company’s commitment to Real Growth
How a company approaches development reveals whether it will support or stifle your trajectory. Surveys show that 60 to 70% of HR professionals express dissatisfaction with performance management systems. This signals a majority of rigid, outdated cultures that hinder both growth and flexibility.
Modern employers invest in career development programs that include mentorship, skill-building opportunities and clear advancement paths. These green flags indicate an organization that prioritizes meaningful employee development. During your research, examine whether the employer offers structured learning, cross-functional projects and visible promotion patterns that reward performance.
Seek Radical Transparency in Pay and Promotions
You can’t map a route without coordinates, and compensation transparency provides them. Companies that publish pay bands and promotion criteria let you project your earning potential with precision, which is critical when you’re calculating your FI timeline. Continue Reading…
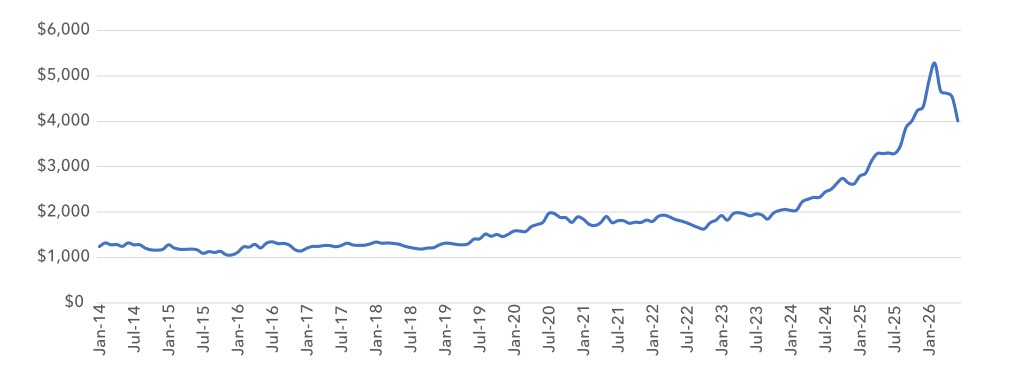
Gold has ascended to record highs since the start of 2025, proving to be one of the defining stories in the market at the midway point of the decade. Indeed, the yellow metal has rewarded patience as much as conviction with its run-up in 2025 and 2026. The spot price of gold bullion was priced just over US$2,500 per ounce starting 2025 and finished up the year nearly 60%. That momentum carried into the new year in 2026, with gold surging to an all-time high of over $5,500 an ounce in late January.
The gold rally hit turbulence due to the escalating US-Iran military conflict, pushing oil and inflation expectations higher. This prompted markets to price out U.S. Federal Reserve rate cuts, spurring the yellow metal to lose more than 10% in the month of March alone; its worst monthly decline since 2013.
Gold Price in USD/oz Since 2014
Source: Bloomberg, June 30, 2026.
Gold has held onto the bulk of its gains heading into the summer of 2026. That has left investors, particularly those in or approaching retirement, to weigh how the world’s oldest store of value fits alongside the steady income their portfolios need to provide.
The different ways to own gold
Investors have often leaned on gold in two distinct ways: bullion and equities.
Gold bullion, which is represented in physical bars, coins, and the ETFs that track the spot price directly, has served its traditional role as a store of value and a hedge against currency debasement, fiscal uncertainty, and geopolitical shocks. Bullion has no counterpart risk, does not default, and does not dilute. This is why long-term allocators, and central banks, favour it as a ballast. This is the kind of protection retirees may prioritize or seek when preserving capital matters as much as growing it.
Rising sovereign debt and eroding confidence in fiat monetary systems have driven both physical bar purchases and large institutional buying. Meanwhile, global gold ETF inflows reached a record US$89 billion in 2025.
Gold equities, which are represented by gold miners and the ETFs built around them, offer a different exposure entirely. Miners carry operating leverage to the gold price. Their earnings, and respective share prices, tend to amplify moves in the underlying metal, for better and worse.https://www.etf.com/sections/data-dive/gdx-stock-vs-gold-price-miner-etf
HPYG | Gold bullion & gold equities with monthly income
The Harvest Premium Yield Gold ETF (TSX: HPYG) launched on Tuesday, July 7, 2026, and stands as an option for investors who want exposure to both sides of the equation; gold bullion and leading gold equities, without having to choose between preservation and growth. That combined approach pairs the ballast of physical gold with the torque of producer stocks in a single vehicle. Continue Reading…
Getting a mortgage renewal letter seems pretty straightforward. Your lender gives you a new rate and payment, you sign it, and you’re done.
At least that’s how it looks.
What I started wondering was: how does the average homeowner actually know if the offer they’re getting is any good?
I’m not a mortgage broker or financial adviser. I’m just someone who started digging into this and realized it’s surprisingly difficult to get a simple answer. You can search mortgage rates online in about 30 seconds. The problem is that the rate you find isn’t necessarily comparable to the renewal offer sitting in front of you.
There can be different conditions, different mortgage types, different equity requirements and all sorts of other details attached to an advertised rate. So if your bank offers you 4.89% and you find 4.24% online, that doesn’t automatically mean your bank is ripping you off.
But I’d certainly want to know why there’s a difference.
The rate is a starting point
Obviously the interest rate matters.
A difference that looks fairly small on paper can make a noticeable difference to your payment, especially with a large mortgage balance.
But there are other things worth looking at too.
What are the prepayment privileges? What happens if you need to break the mortgage early? Is it portable? Are there fees or restrictions? And if another lender has a lower rate, what would it actually cost and involve to move the mortgage?
Those details aren’t nearly as exciting as finding a lower rate, but they can matter.
There’s nothing wrong with staying with your bank
I think this part sometimes gets lost.
Switching lenders isn’t automatically the smart move. Continue Reading…
By Stephen Dover, CFA, Franklin Templeton Institute
(Sponsor Blog)
Any consideration of emerging markets must begin with the case for global investment strategy. The decision to allocate capital internationally is not just about geographic diversification. Rather, it is increasingly driven by fundamental shifts in absolute and relative returns that drive global capital flows, by the discovery of new investment opportunities, and by the need to identify and manage concentration risk.
This section establishes the reasons why active international allocation strengthens institutional portfolios that also reinforces the rationale for emerging market allocations.
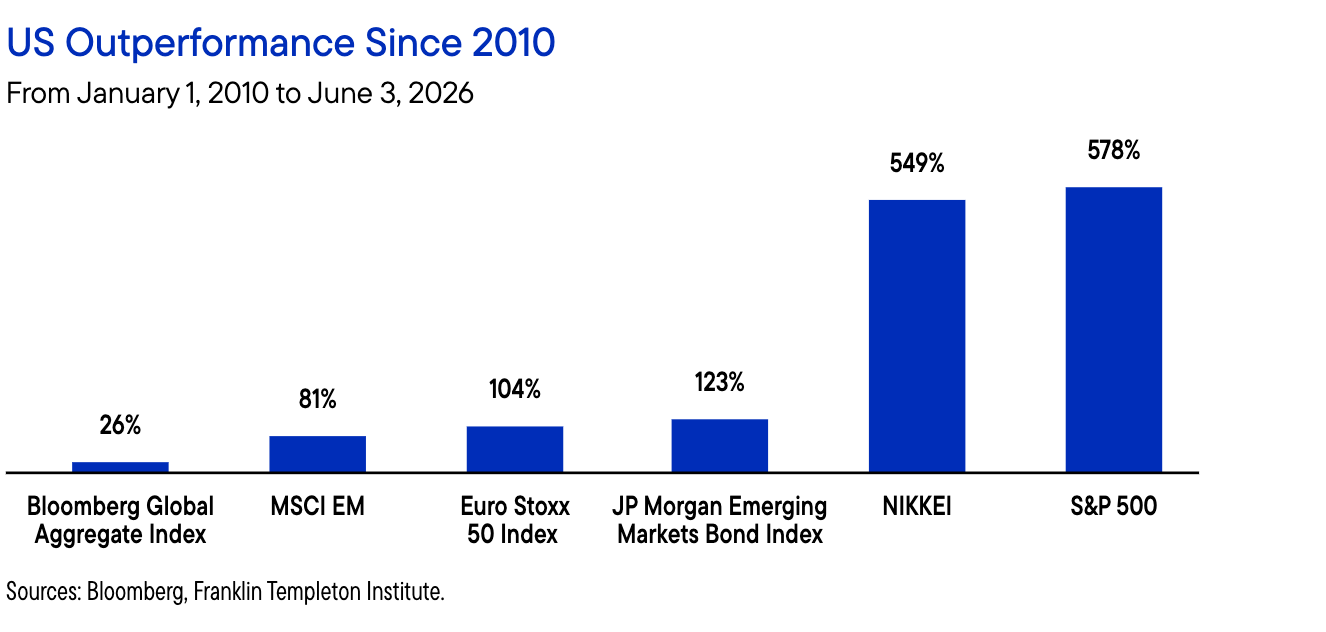
In an extended period of “US exceptionalism”—roughly spanning the 15 years from the global financial crisis to the middle of the current decade — investors increasingly gravitated to US equity and credit markets. That was understandable, given the superior returns — in absolute and risk-adjusted terms — delivered by US financial assets.
Importantly, superior returns on US assets were driven by superior fundamentals, including growth, institutional solidity, vast market liquidity, innovation and historic levels of profitability.
At the same time, however, US-based equity returns became more concentrated, as mega-
capitalization stocks accounted for a growing share of widely followed market-capitalization indexes.
Partly driven by concerns about concentration risk and partly because of improving returns in other
markets, investors have more recently begun to look for opportunities in other markets.
Over the past year, European, Japanese and emerging equities, and particularly emerging debt, have episodically produced superior returns to those found in US equity and fixed income markets. Those outcomes have begun to raise awareness of global opportunities, among them in emerging markets.
Renewed interest in global investing stems from other factors as well. Economic and monetary policy
divergence is becoming more significant. Prior to the US-Iran War, the Federal Reserve (Fed) was
biased to cut rates, the European Central Bank (ECB) had paused its easing cycle, the Bank of Japan
(BoJ) had already cautiously begun to hike rates, and various emerging central banks were prepared
to cut rates amid falling inflation. Those divergences in policies had contributed to a weakening of
the US dollar since early 2025, which in turn boosted investor interest in non-US markets, including
in emerging markets.
With the outbreak of the war and the impairment of shipping via the Strait of Hormuz, policy
perceptions have again shifted. The Fed and emerging central banks are now (mostly) on hold, the
ECB and the BoJ are inclined to tighten their monetary policies. Unsurprisingly, volatility, correlation
and returns have shifted markedly.
But the underlying point remains: Divergence in the conduct of monetary policy creates opportunity for tactical re-allocation. And it isn’t just about monetary policy. In many respects, fiscal policy divergence is even more notable.
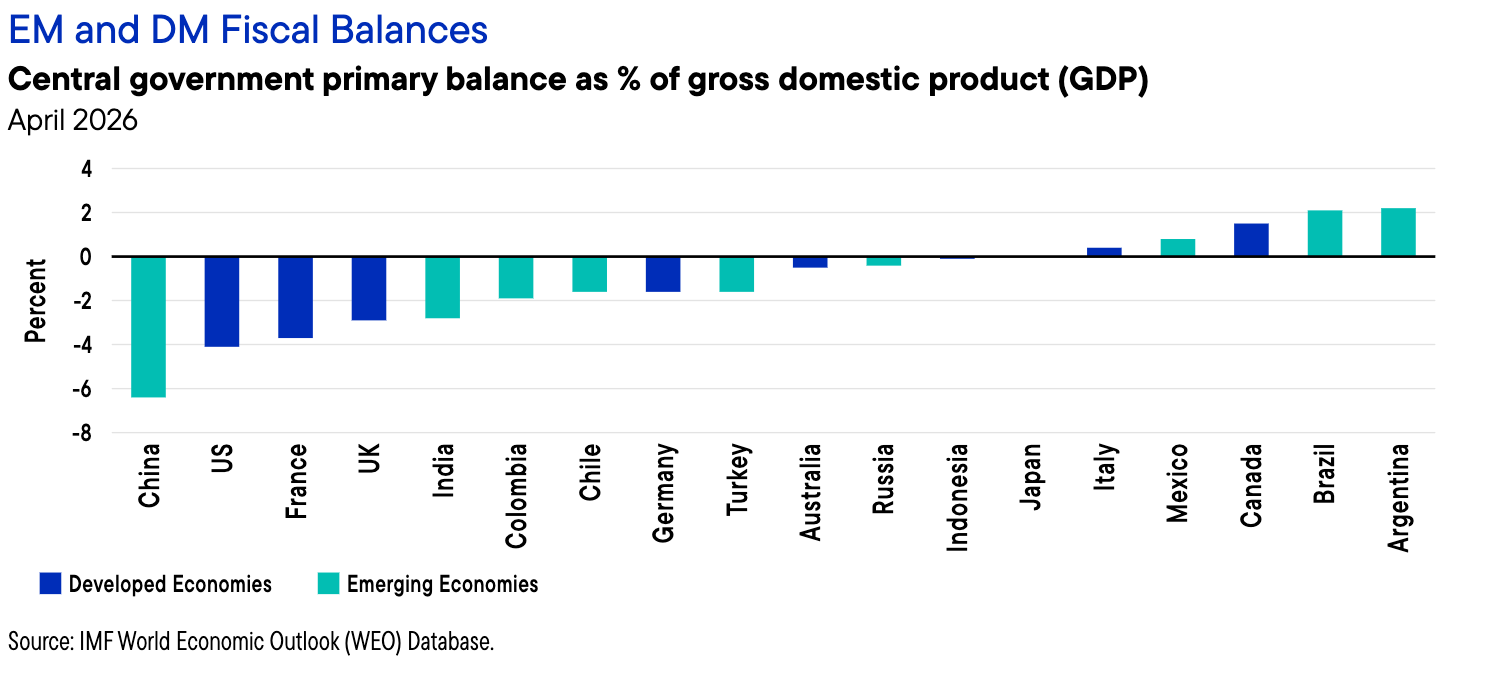
In the United States, large structural budget deficits are forecasted over the next decade.
Meanwhile, Japan’s new government is promising more fiscal stimulus as well. So, too, are Germany and the European Union.
In contrast, over the past decade many emerging countries have been pursuing more disciplined,
orthodox fiscal policies, with the upshot that their sovereign credit fundamentals are improving in
absolute and relative terms. That trend lends support to secular declines in risk premia and should
manifest in even lower nominal and real interest rates, as well as stronger emerging currencies.
Directly, that boosts emerging debt returns, but it also lends greater resilience to many parts of the
emerging complex.
As noted, global markets — including emerging markets — have recently exhibited episodes of
outperformance relative to US equity and fixed income returns. That is important, because for most of
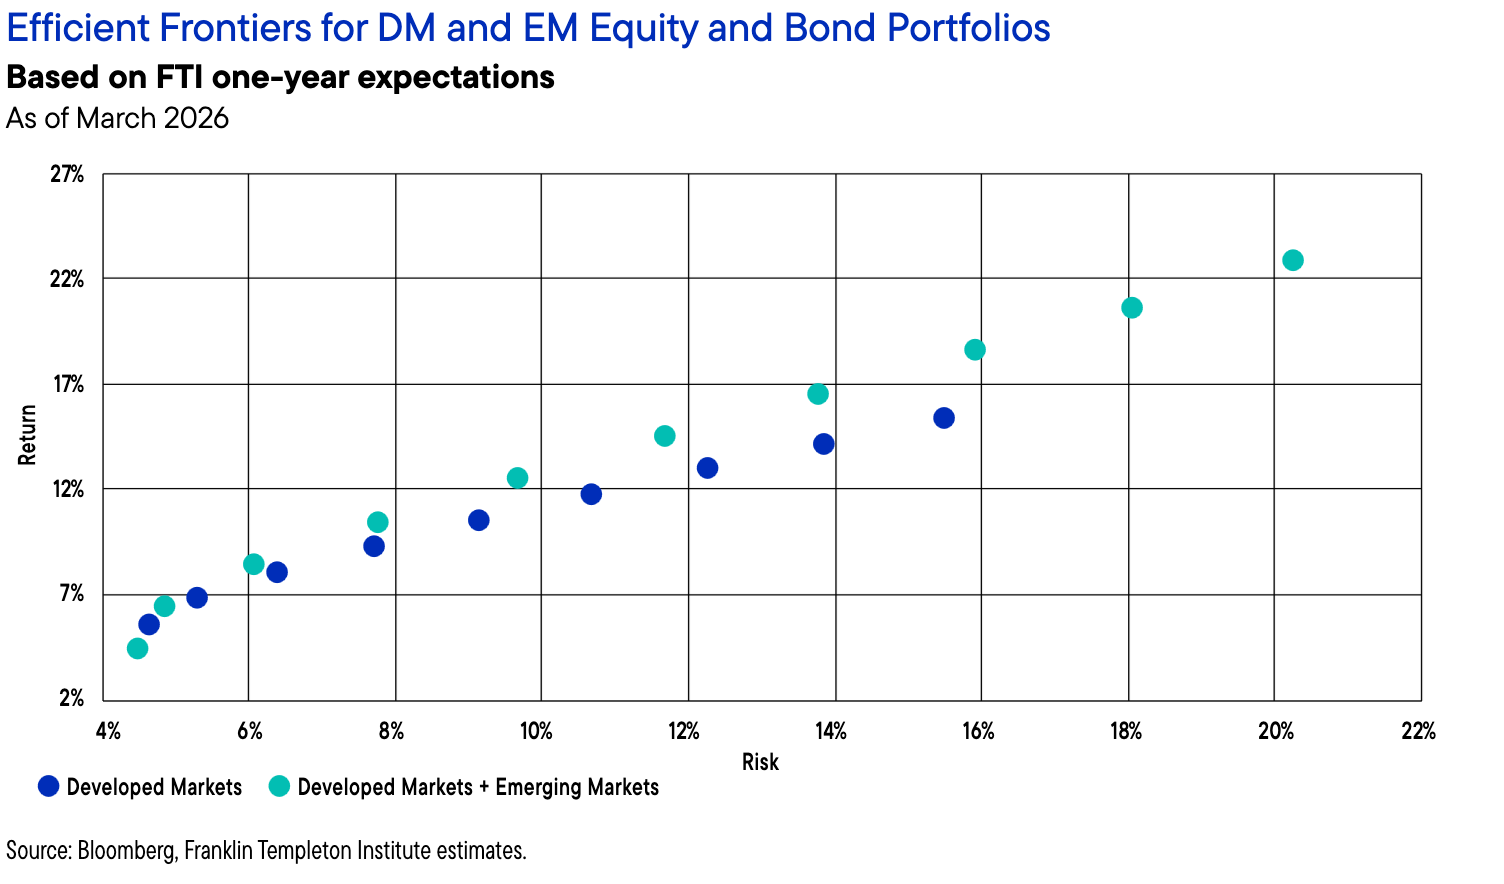
the past 15 years US exceptionalism has been dominant. So much so, indeed, that if one compares the
efficient frontiers of investing with and without emerging markets since 2010, it is clear emerging
market allocations had almost no positive impact on portfolio returns, adjusted for risk, over the past 15
years.
But we believe those historic results are not likely to persist. Owing to improving emerging market
fundamentals, which we describe in detail in the next section of this paper, absolute and relative
expected returns are shifting in their favor. Using our estimated year-ahead returns across all
markets — developed and emerging, public equity and debt — a clear upward and leftward shift in the
efficient frontier is apparent when comparing a developed market only to a blended emerging and
developed portfolio. We believe emerging markets (alongside other non-US developed markets) are
therefore poised to contribute to improved portfolio performance in the year ahead: and most
probably for longer.
EMs are undergoing a profound transformation, one that is not cyclical in nature but structural, durable and increasingly self-reinforcing. The traditional narrative of emerging markets as externally dependent, volatility-prone economies is being reshaped by a new set of underlying forces that are redefining their role in the global economy.
EMs have generally shown significant resilience this decade, facing down a series of shocks arising from the COVID-19 pandemic, the inflationary outcome of the Russia-Ukraine war and the US Fed’s sharp interest-rate hikes during 2022-2023, and last year’s substantial tariff volatility. Not only did EMs survive this period, but many have thrived.
As world trade reconfigures and global actors realign geopolitically, EMs have found themselves generally well-placed to benefit from these global shifts: including some that are likely to benefit under the new tariff regime. This compares to earlier years when EMs would often face crises (whether debt, balance of payments and/or in banking systems) from global shocks.
The fact that EMs are in a favorable position now is largely a result of policy choices that have situated them handsomely to face a rapidly changing world economy. In this regard, we note three significant global regime changes that we believe EMs are now well-placed to benefit from: structural improvements in EMs, global trade econfiguration, and a shift in the US dollar’s ability to attract global capital inflows.
Regime change: EMs are structurally sounder
Policy responses with respect to both monetary and fiscal policy have improved significantly across EMs over the past couple of decades. Adoption of sound, credible policies and nurturing of institutions (such as inflation targets, fiscal rules and independent central banks) have helped policy formulation and improved the market’s perception of the credibility of EM policymakers. Continue Reading…


 Posted By
 My latest MoneySense Retired Money column looks at the imminent retirement of The Wealthy Barber himself: David Chilton. You can find the full column here: The Wealthy Barber retires.
 Posted By