Reviews

We review books that deal with everything from financial independence topics to politics, and anything in between. We may sometimes stray into films and music if there is a “Findependence” angle.

3 books I just read that Retirees DIYing their pensions need to read

Amazon.ca

My latest MoneySense Retired Money column looks at a must-read new book on Retirement as well as two related books on DIY stock-investing. You can read the full column by clicking on the highlighted headline: Who you gonna trust: Barry Ritholtz or Jim Cramer?

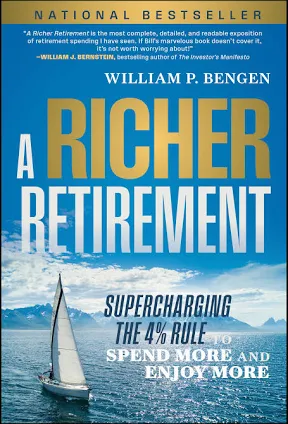
The must read and main focus of the MoneySense column is William Bengen’s A Richer Retirement: Supercharging the 4% Rule to Spend More and Enjoy More. If that sounds familiar it should: Bengen’s original book on the 4% Rule is considered the bible of retirement, with his famous “SAFEMAX” guideline of 4% a year being an annual amount of withdrawals that should be “safe” for retirees to continue for a full 30 years, even after inflation. The original book,  titled Conserving Client Portfolios During Retirement, was first published in 2006.

Never mind that even Bengen considers 4.7% be a more universal SAFEMAX. The original book was aimed at financial advisors and professionals while the new one ostensibly is aimed at retail investors and retirees. I say ostensibly because I was a little disappointed with it and found the plethora of complicated charts and tables a bit much for lay investors. Still, there’s a lot of common sense there: Inflation is big long-term threat to retirees as are bear markets. Withdrawing too much from portfolios can be disastrous if you are unfortunate enough to retire just as a bear market hits and/or inflation starts to bite.

On the other hand, sticking with the old 4% rule or even the smaller amounts of 3% or even 2% advocated by some cautious souls, could result in you withdrawing less than you really need to enjoy retirement, although the tax department and any heirs might commend your caution and frugality.

How to make money in any market
Amazon.ca

While it’s rare for me to buy new hardcover books because I receive so many “free” review copies of financial books, I actually did buy A Richer Retirement as soon as it was available on Amazon. Plus, unusually, I also bought two other brand new books on the related topic of investing and stock-picking.

One was Jim Cramer’s How to make money in any market, by the sometimes revered but often maligned host of  CNBC shows Mad Money and Squawk on the Street. It’s fashionable for some financial journalists who believe in efficient markets and indexing to diss Cramer but I am not in that crowd. In fact, Cramer recommends that newcomers to investing put the first US$10,000 into an S&P500 index fund or ETF.

However, for seasoned investors and even retirees, Cramer suggests putting half a portfolio in index funds and the other half in individual stocks. Where we part company is his recommendation that the bucket of stocks be restricted to just five names, which would mean 10% in each. For my money, that’s way too concentrated and risky, even though he often brags about how he is often accosted by Nvidia Millionaires who tell him they bought that stock as soon as he announced on air that he had renamed his dog Nvidia.

How NOT to invest
Amazon.ca

Finally, regulars to this site may already have read Michael Wiener’s review of Barry Ritholtz’s How NOT to invest, which appeared here in this blog a few weeks after appearing on his Michael James on Money blog.

To be sure, those who are fond of disparaging Jim Cramer might quip that should have been the title of his own book, seeing as there are actually ETFs out there that try to profit by shorting Cramer’s picks. As of this writing, my copy has arrived but I have not yet finished reading it, as it’s a bit longer than the other two.

But based on the book blurbs and Michael’s review, I have no doubt it will be worth reading, whether for younger investors or seasoned ones and/or retirees.

Finally, while I only just received my review copy, I note that David Chilton is publishing a new edition of his classic financial novel, The Wealthy Barber, which any young person just starting to invest should acquire.  I look forward to revisiting it.



How NOT to invest (Book Review)

Amazon.ca

Special to Financial Independence Hub


Before reading Barry Ritholtz’s book How Not to Invest, I wondered if the “Not” in the title was a sign it would be filled with gimmicky ways of giving investment advice.

It isn’t.  Investing well is simple enough, but the world tries to push us towards many types of poor choices that lose us money.  The best advice is a list of the many things to avoid when investing.  This book gives readers the benefit of Ritholtz’s extensive experience with staying on the simple path to investing success.

The book is organized into four parts: Bad Ideas, Bad Numbers, Bad Behavior, and Good Advice.

Bad Ideas

Part of what makes it so easy to push investors toward bad ideas is that we believe secret ways to create wealth exist when, in fact, they don’t exist.  “We don’t like to admit it, but nobody knows anything about the future — not just you and me, but the so-called experts too.”

I’ve had the experience of getting people to agree that the future is unknown, and then they immediately ask what I think will happen with interest rates.  It’s hard to get people to really believe the future is unknown.  Ritholtz does an excellent job of going through some high-profile examples of the futility of forecasters.  Instead of searching for the right seer, he suggests having a “financial plan that is not dependent upon correctly guessing what will happen in the future.”  “Don’t predict what will happen, but rather, assess the range of possible outcomes — what could happen.”

So much of the information we see about investing is just noise.  Ian Cassel said “The maturation of every investor starts with absorbing almost everything and ends with filtering almost everything.”

It is freeing to admit we don’t know what will happen and to plan for a range of possible outcomes.  What too many people do is “Make predictions, then marry those forecasts.”  If they’re wrong, “This usually leads to catastrophic results.”

Bad Numbers

This part of the book starts with a good section on economic innumeracy that discusses denominator blindness, survivorship bias, mathematical models, and the fact that we respond better to anecdotes than data.

Part of what makes this book a pleasure to read is Ritholtz’s optimism.  Paul Volker once said “The only useful thing banks have invented in 20 years is the ATM,” but the author lists 20 useful financial innovations, including index funds, ETFs, low costs, fast trade clearing, and cash-sending apps.  The challenge for investors is to benefit from these innovations rather than lose money with them.

The author sees bull and bear markets as secular periods characterized by either high price-to-earnings (P/E) ratios or low P/E ratios.  I’m not sure how he thinks investors should use this information.  In my case, I use P/E levels to make modest formulaic adjustments to both my asset allocation and my expectations for future stock returns.

Sometimes people overestimate how much the news of the day will affect markets.  Some industries were devastated by Covid-19.  However, it turns out that these industries represent a small fraction of overall markets.  If in “mid-2020, the 30 most economically damaged industry categories were delisted, it would have shaved off just a few percentage points from the S&P 500.”

There is a winner-take-all tendency in many areas, including stocks.  “Just 1.3% of the public companies listed in the United States account for all the market gains during the last three decades.”  We can “find the best-performing stocks by buying them all” in an index fund.

“Simplicity beats complexity every time.  A portfolio of passive low-cost indexes should make up the core of your holdings.  If you want to do something more complicated, you need a compelling reason.”

Bad Behavior

“Bad behavior leads to bad investing outcomes.”  Ritholtz categorizes bad behaviour into ten areas, and he illustrates some of them in an amazing story about a billionaire family called the Belfers.  They lost money with Enron, Madoff, and then FTX!  “Has there ever been a greater, more unholy trifecta than this?”  Even billionaires make some terrible choices.

“If only we made better decisions, we would all be so much better off.”  If we could eliminate all investing mistakes for everyone, we might be better off on average, but there is a zero-sum aspect to investing mistakes.  Your loss is someone else’s gain.  The main overall benefit of eliminating all investing mistakes is that those employed exploiting such mistakes would move on to do something useful for society. Continue Reading…

Your Money Struggles have nothing to do with Money

Photo courtesy Jessica Moorhouse

By Jessica Moorhouse, CFC™  

Special to Financial Independence Hub

What most people don’t know is that when I first pitched my book idea to my publisher, its original title was More Than Money.

I thought it expressed everything I wanted to say about how most people’s financial struggles went well beyond a lack of money or financial literacy. After more than a decade of discussing money with people from all walks of life as a content creator and helping individuals and couples with their finances as a Certified Financial Counsellor, I saw firsthand how money was rarely the root cause of their financial troubles. Unfortunately, I wasn’t the only person who thought it was a good title. On my last count, there are already five books on Amazon using that same name.

It’s about Everything but Money

It wasn’t until two months after I handed in my manuscript that I finally landed on the right title for my book: Everything but Money. I think it took me that long because I needed to go on a well-overdue journey of self-discovery while writing my book and come to the realization that my own struggles with money have always been about everything but money. Through countless hours of research, interviews, and therapy, I had to face the fact that as a money expert whose job it is to educate people about their finances, my relationship with money was downright toxic.

My Toxic Relationship with Money

At first, I was ashamed. I’m supposed to be the expert here, which should mean I’m a role model and have my stuff together. Although it may look that way on a balance sheet, on the inside, I was an anxious mess who never felt good enough, no matter how much I earned or had in the bank. The real reason I dove head-first into the personal finance space as a young blogger in 2011 was that subconsciously, I thought money would be the solution to all of my unhealed emotional wounds. The unhealthy friendships that damaged my spirit growing up. The middle child syndrome that made me feel invisible. The intense pressure I put on myself to be seen and heard through external validation.

Don’t confuse Money for Happiness (but it can help)

But as I discovered while writing the book, money isn’t some magical cure-all. There’s a reason there are so many miserable millionaires and billionaires out there. Although research shows that money can increase your happiness (to a limit), research also shows it cannot fix your unhappiness. I mean, have you seen Succession? Continue Reading…

Summer Reads 2025: Booking Up on Ageing & Longevity

By Mark Venning, ChangeRangers.com

Special to Financial Independence Hub

For this my 8th year of suggested titles for “booking up” in the subject area of ageing and longevity there’s only one book in a stack of others on unrelated subjects.

As I observed last year, with countless new books in this subject area arriving each year, sometimes I find a scarcity of new books that help to move the societal conversation, for I tend to lean towards those which focus that way, and those that offer an age inclusive global perspective where possible.

First up then, published in Australia, is The Age-friendly Lens (2023) a ‎ Routledge collection of essays/case studies edited by Christie M. Gardiner &Eileen O’Brien Webb, compiled in 2 parts; Age-friendly Systems and Age-friendly Housing & Accommodation. The chapters feature insights from around the world: Canada, Netherlands, Poland and Australia for example. In part as the introduction says, this book is “recommended reading for policy makers, politicians, think tanks and lobbyists who are all-age-inclusiveness.”

For a taste, Chapter 13 is available in Open Access on Taylor Francis Publishing:  International standardisation of products and services for ageing societies: Promoting the global application of an age- friendly lens. I promote this as it is written by a team of members on the ISO TC314 Ageing Societies Standards Committee, of which I am a relatively new contributing member represented in Canada on the Standards Council of Canada.

As somewhat of a connection off centre from this age-friendly lens, as it relates to age-friendly cities, I mention this next book on my summer reading list, new this summer: Messy Cities: Why We Can’t Plan Everything (2025) a collection of over 40 short essays edited by Dylan Reid, Zahra Ebrahim, Leslie Woo & John Lorinc – asking myself to wonder, how does messy work when we consider the design of an age-friendly or age inclusive city?

Urbanist admired Toronto

In Dylan Reid’s “sneak peek” of this book about messy urbanism, on his Desire Lines Substack, the story is told about how urbanist James Rojas came to Toronto in 2007 and admired it for the “sort of less than manicured quality to the whole thing … and coupled with a huge diversity of people, the city ends up feeling gloriously messy, in a functional and walkable way.”

Well Toronto, my original home city, is still messy, a 2025 version one can observe. And not to be disturbed, while I wait for this book to arrive this week, I have directed myself to inspect Reid’s 2010 essay Bless This Mess,  which will tone me up in the meantime. Continue Reading…

Retired Money: An online Canadian Retirement Club

My latest MoneySense Retired Money column looks at a recently launched Retirement Club devoted to Canadians in or near the cusp of Retirement.

Primarily online, Retirement Club was launched by occasional MoneySense contributor Dale Roberts and a partner, Brent Schmidt. You can find the full MoneySense column by clicking on the highlighted headline:  Retirement planning advice for people who don’t use an advisor.

Roberts, who once was an advisor for Tangerine, is known for his Cutthecrapinvesting blog and in the U.S. for his contributions to Seeking Alpha. While I have no financial or business interest in the club I did become a member. There are regular Zoom calls where (mostly) recent retirees exchange views on topics like the 4% Rule, RRSP-to-RRIF conversions, ETFs, Asset Allocation in the age of Trump 2.0 and many of the topics this Retired Money column often attempts to tackle.

            You can find Roberts’ own announcement of the club – which charges an annual fee of $250 – on my own site earlier in mid-April. (+HST, but it may qualify as an Investment Counsel fee deductible on your personal tax returns). As always check with your accountant, advisor or tax professional).

            My initial impression is that the club seems to involve a lot of work for someone who describes himself as semi-retired. But that seems to be par for the course for financial writers approaching retirement. I’m in a similar boat, as is the American blogger Fritz Gilbert, who recently announced the similarly ironic fact that he was retiring from Full-time Blogging about Retirement. (also in April).

Aimed at self-directed investors

            In his introduction, Roberts wrote that many of his audience are self-directed investors. That jibes with his site’s campaign against high-fee investment funds, in favor of low-cost index funds or ETFs purchased at discount brokerages. While some, like myself, may also use the services of a fee-for-service advisor, many DIY retirees are in effect running their own pension plans. In theory, one of those much-written-about All-in-one Asset Allocation ETFs can do much of the heavy lifting for such investors, but in practice, there’s a fair bit of anxiety about markets, the Canadian government’s rules about TFSAs, RRIFs etc., Asset Allocation, the ongoing Trump Trade War and much more. So it makes sense to gather in one place and exchange views with others going through a similar process.

          In a regular email update to Club members, Roberts explains that “the key concern of Retirement Clubbers is financial security and how to use their portfolio assets in the most efficient and cost-effective manner. That’s why we have a master list of retirement calculators (free and pay-for-service) to test.”

Delaying Government Pensions

         As you’d expect, the Club regularly addresses the major chestnuts of Personal Finance as it relates to those within hailing distance of Retirement. The most common ‘Retirement Hack’ espoused by the Club is to delay receipt of the Canada Pension Plan [CPP] and Old Age Security [OAS] past the traditional retirement age of 65 to allow for more generous payouts at age 70. Most club members lean to taking these benefits as late as possible but of course personal circumstances may dictate earlier start dates.

        To bridge the income gap (from age 60 to 70 for example) RRSP/RRIF accounts will be harvested (spent) in quick fashion: often termed an RRSP meltdown. TFSA and Taxable accounts can also be tapped to provide necessary funding as retirees delay receipt of those CPP and OAS benefits. Continue Reading…