Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Retirement planning programs revisited

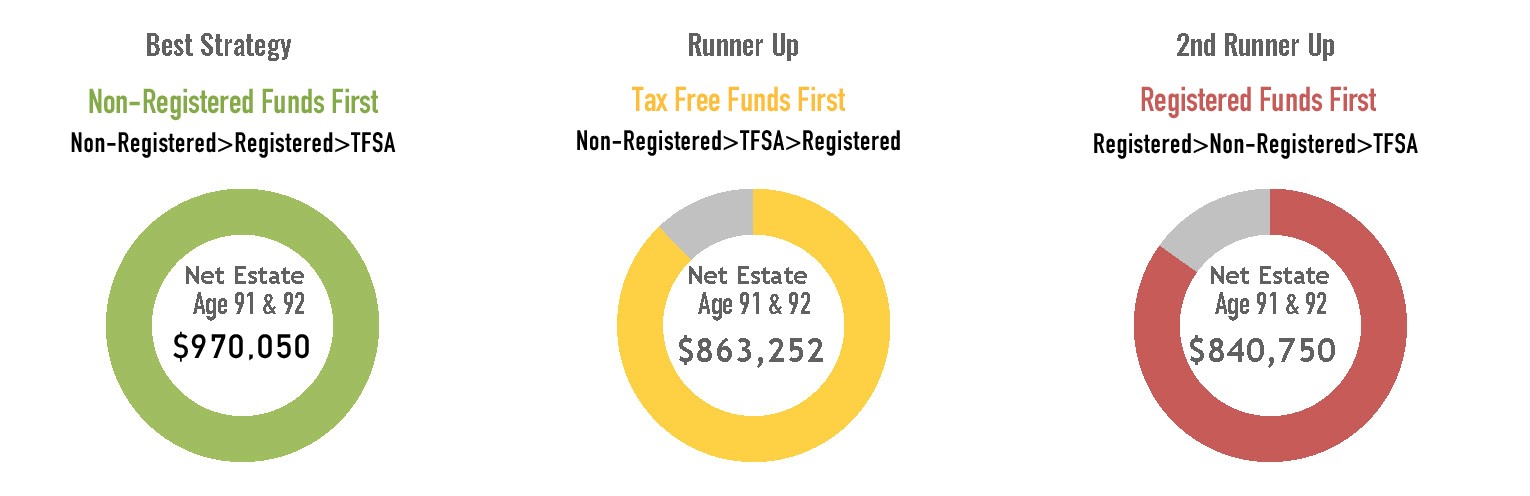
More than a year ago I wrote a column for the Financial Post about a handful of Canadian retirement income planning software packages that help would-be retirees and semi-retirees plan how to start drawing down from various income sources: Click on the highlighted text to retrieve the full article: How you draw down your retirement savings could save you thousands: this program proves it.

The focus of the FP piece is Cascades but you can also find a MoneySense piece I wrote from late 2018 that looked at Viviplan, and one I wrote for the Globe & Mail last November that described Cascades, Viviplan and Doug Dahmer’s Retirement Navigator and BetterMoneyChoices.com.

Dahmer has been writing guest blogs on decumulation here at the Hub almost since this site’s founding in 2014. See for example his most recent one, or the similar articles flagged at the bottom: Top 10 Rules for Successful Retirement Income Planning. Dahmer says he’s pleased that others are waking up to the need for tax planning in the drawdown years: “Cascades provides a very good, easy-to-use introduction to these concepts.”

There may be as many as 26 distinct sources of income a retired couple may encounter, estimates Ian Moyer, a 40-year veteran of the financial industry and creator of the Cascades program described in the articles.

When he started to plan for his own decumulation adventure, six years ago, he felt there was very little planning software out there that was both comprehensive and easy to use. So, he hired a computer programmer and created his own package, now called Cascades.

Continue Reading…

Retirement not what many were expecting, and not in a good way: Sun Life survey

My latest Financial Post column, which is on page FP 3 of Tuesday’s paper, looks at a Sun Life retirement survey released this morning. You can find it online by clicking on the highlighted headline: Canadians finding retirement is not all it’s cracked up to be.

So if you think Retirement is about eternal sea cruises and African safaris, you may be abashed by the Sun Life finding that almost one in four (23%) describe their lifestyle as a frugal one that involves “following a strict budget and refraining from spending money on non-essential items.”

Furthermore, many can expect to still be working full-time at age 66, which just happens to be my own age. And as you can see from this blog, I’m still working, if only on a self-employed semi-retirement basis.

In fact, among the 2150 employed Canadians polled by the 2019 Sun Life Barometer poll conducted by Ipsos, almost half (44 per cent) expect they’ll still be employed full-time at age 66. Among the “frugal” retirees still working after the traditional retirement age, 65 per cent say it’s because they need to work for the money rather than because they enjoy it.

In an interview, Sun Life Canada president Jacques Goulet mentioned most of the main reasons, few of which will come as a surprise to this blog’s readers. Mostly there is a failure to plan for Retirement early enough to save the kind of sums involved. Another familiar culprit is the ongoing decline of employer-sponsored Defined Benefit pension plans, which are becoming more and more rare in the private sector. Most of us can only envy the tax-payer backed guaranteed inflation-indexed DB pensions enjoyed by most government workers, politicians and some members of labor unions: a bulletproof source of income that you can’t outlive.

47% at risk of outliving their money

The alternative for many are employer-sponsored Defined Contribution pensions (DC plans), group RRSPs or personal RRSPs and TFSAs, which means taking on market risk and longevity risk. Both are challenges in the current climate of seemingly perpetual low interest rates and ever volatile stock markets, not to mention rising life expectancy. Even then, Goulet told me Canadians with DC pensions are leaving a lot of money on the table: $3 or $4 billion a year in “free money” that is obtainable if you enrol in a DC pension where the employer “matches” the employee contributions: typically 50 cents for every $1 contributed.

Finally, there is a large group that have no employer pension of any kind, or indeed any steady job with benefits, and these people are unlikely to have saved much in RRSPs or even TFSAs, which they should if they can find the means. This group may account for a whopping 47% of working Canadians, Sun Life finds, and about the only thing they’ll be able to count on in Retirement is the Canada Pension Plan (CPP) as early as age 60, Old Age Security at 65 and probably the Guaranteed Income Supplement (GIS) to the OAS. These people would be better off continuing to work till 70 in order to get higher government benefits, a time during which they can build up their Tax-Free Savings Accounts (TFSA)s. TFSA income does not impact CPP/OAS/GIS, which is not the case for RRSPs and RRIFs.

Finally, a word about continuing to work into one’s 60s and even 70s. I know many who do, and not always for the money. I’m in the latter category myself, even though personally my wife and I could be considered the poster children for maximizing retirement savings, living frugally and investing wisely. There are worse things in life than going to a pleasant job that provides mental stimulation, structure and most of all purpose. Many of these ideas are explored in the book I jointly co-authored with Mike Drak: Victory Lap Retirement.


Do Spousal RRSPs still have a place in Retirement Planning?

By Matthew Ardrey

Special to the Financial Independence Hub

One of the more frequent questions I get from clients regarding their retirement planning is, with the pension income splitting legislation, are spousal RRSPs worthwhile anymore? The answer is yes, in several situations.

Before I outline the planning situations that are useful for spousal RRSPs, first a little primer on what they are and how pension income splitting changed the view of them.

Spousal RRSPs

A spousal RRSP is an RRSP account in which one spouse makes contributions based on his/her room to a RRSP in the other spouse’s name. This is a way to income split in retirement, as future withdrawals, subject to restrictions noted below, would be in the recipient spouse’s name and presumably in a lower tax bracket than the contributor spouse.

The restriction is on the withdrawal timing. If the recipient spouse withdraws any amount from the spousal RRSP in the year of a contribution or the two years following, the amount withdrawn attributes back to the contributing spouse. The only exception to that is a minimum RRIF payment.

In summary the contributing spouse receives the RRSP deduction at his/her current marginal tax rate and the future income is withdrawn at the recipient spouse’s lower tax rate in retirement, maximizing the RRSP tax deferral advantage.

Pension Income Splitting

The pension income splitting legislation introduced in 2007 allowed not only defined benefit pension income to be split between spouses, but also RRIF payments after the age of 65. No matter who owned the RRIF, both spouses could share equally in the income for tax purposes. As the RRIF payment could be divided 50/50 between spouses, the income splitting advantage of the spousal RRSP diminished.

The Case for Spousal RRSPs: Tax Efficient Decumulation

After years of saving, much of today’s tax planning is around decumulating assets. My clients not only want to drawdown their registered accounts but do so in the most tax efficient manner possible. For many, this opportunity often lies in time period between retirement and the receipt of CPP and OAS.

This is one of the most advantageous times to employ an RRSP meltdown strategy. With no further employment income, before receiving government pension income and with presumably little to no other income, RRSP withdrawals can be made with minimal tax consequences. Continue Reading…

How to use your retirement plan to fund your dream business

By Eric Goldschein

Special to the Financial Independence Hub

If you’ve decided to take the leap and start your own business, you probably have one pressing question on your mind: Where will you get the money to fund it? 

Startup costs can drain personal bank accounts, and few business owners are in a position to qualify for affordable small business financing right away. Lenders tend to prefer long-established businesses. 

If you’ve been a diligent financial planner and have been saving up for retirement, you may have access to a low-cost source of business funding: your own retirement plans. Here are three ways to use your retirement to fund your dream, whether that’s an e-commerce business or a restaurant: 

1.) Use a 401(k) business loan

Some 401(k)s and other eligible retirement plans in the U.S. — 403(b), and 457(b) plans and profit-sharing plans — allow you to loan yourself either US$50,000 or up to half of your vested balance (whichever is less). 

If you are testing out your business as a side hustle and will remain employed and contributing to your retirement plan, this is an excellent option. A 401(k) loan gives you access to low-cost funding (interest rates are usually the prime rate plus 1%) that you can use to see if your idea is worth investing in further. 

You also won’t pay any additional fees or penalties for taking out this money, unless you default on your payments: in which case the IRS will treat it as a regular withdrawal, incurring penalties. 

If you need $50,000 or less to improve your new business, contact your plan administrator to get the ball rolling.  

2.) Use a “rollovers as business startups” plan

Do you need more than US$50,000 in business funding, and are you ready to work on your business full time? If so, you can use a rollover as business startups (ROBS) to access funds from a 401(k), IRA, or other eligible retirement account without penalty. 

There are a few qualifications you need to meet to use a ROBS plan:

  • Your business must be a C-corporation (if it isn’t, you must restructure it). 
  • Your retirement account needs at least $50,000 in it, and it cannot be a Roth IRA. 
  • You must be an employee of the business and receive a salary. 

The next steps are a bit complicated, but the basics are as follows: Set up a new retirement plan under your C-corp. Roll over your funds from your existing retirement plan to your new one. Then, your C-corp sells stock to the retirement plan, and you use the proceeds from that sale to fund your business—buying new inventory, renovating your space, or any other general business needs. An accountant, lawyer, or financial service can help you do this. 

This isn’t a loan, but a constructive use of your retirement funds. The biggest risk here is losing your retirement funds in pursuit of small business success. If you think that’s a risk worth taking, this is a good bet.    Continue Reading…

5 years of Findependence: The Hub celebrates its fifth anniversary

How time flies! Five years ago this Sunday — Nov. 3, 2014 — the Financial Independence Hub [aka “The Hub”] was launched. From the start the idea was to publish a blog every business day, 52 weeks a year. Thanks to a wide variety of guest bloggers and other contributors, that has been achieved: as of this writing, the Hub had published almost 1,700 blogs.

For those curious, this link will take you to the very first Hub blog, which outlined the planned direction. From the get-go we tried to make a distinction between traditional full-stop Retirement and Findependence, which of course is the contraction for Financial Independence. The related book is Findependence Day (available in both Canadian and US editions).

Findependence is different from Retirement

Even some of the republished blogs the past week indicate how much the term Financial Independence has caught on, although sadly, the term Findependence less so. Just a few days ago, regular Hub contributor Mark Seed published a blog on Strive for Financial Independence not Early Retirement.  (We’re working on getting him to use the term Findependence but Rome wasn’t built in a day!)

I wrote much the same thing soon after the Hub was launched in 2014: Why Financial Independence is a better term than Retirement.

I may as well take this opportunity to clarify a few things about how the Hub operates. First though, we’d like to thank our advertisers, some of which (like Vanguard) have been with us since almost the beginning. It’s that kind of support that means the Hub remains free to users, who by now realize that most Hub blogs publish around 9:10 am, with a daily digest going out around 10 am.

Where the Hub’s content comes from

Why daily content? I guess it goes back to my days as a newspaper reporter and columnist, when my personal motto was “A story a day keeps the editor away.” Of course, it wouldn’t be much of a Semi-Retirement if I had to write a blog for the Hub every day all by myself so from the get-go we were open to guest blogs. An early supporter was Robb (and Marie) Engen of Boomer & Echo: skip over to the Hub’s search function and you’ll find dozens of stories by them. And by the way, that search tool can be very useful in accessing any of the 1700 blogs or so that the Hub has published: they’re still there; you just have to retrieve them with the tool.

Also early in giving us permission to republish blogs were Patrick McKeough of The Successful Investor, Adrian Mastracci of KCM Wealth Management, Mike Drak, my co-author on Victory Lap Retirement, Billy and Akaisha Kaderli of RetireEarlyLifestyle.com and many more. Just this year we’ve added a few more excellent bloggers: Mark Seed of MyOwn Advisor, Michael Wiener of Michael James on Money, Dale Roberts of Cut the Crap Investing, Fritz Gilbert, the Plutus award winning blogger behind Retirement Manifesto and a few more I hope I’ve not forgotten.

I can hear critics questioning the rationale of this republishing approach: all I can say is that you can consider it sort of the Greatest Hits of Financial Independence, given that our goal has always been to be — as you can see in our slogan elsewhere on this site — North America’s Portal to Financial Independence. We are chiefly an aggregator, although there is also original content.

Yes, I try to write a blog most weeks, though as regular readers may realize, they tend to be “throws” — summaries of paid columns or blogs I’ve written elsewhere, including MoneySense.ca, the Financial Post, Motley Fool Canada, the Globe & Mail on occasion, and Money.ca. Think of it as a sort of one-stop-shopping for what I personally write, even as I retrench a bit as my Semi-Retirement unfolds. (I’ll be 67 in April). In a way, the outside revenue I get from writing for the mass media helps defray the Hub’s modest costs, and of course helps to promote the site to new readers.

Apart from republished blogs, the Hub also regularly tries to publish at least two pieces a week of fresh content written by a variety of other contributors: financial advisors and other investment professionals, occasionally marketers or  firms representing a cross-section of the financial services industry.

The Hub’s 6 categories for the Human Financial Life Cycle

We try to publish a wide selection of topics corresponding to the human financial life cycle: if you’ve not noticed, take a look at the blue menu near the top of the site and you’ll see that our blogs are categorized in six sections. We start with young people (Millennials) who are just getting started in their financial lives. So we start with Debt and Frugality, followed by Family Formation and Housing: they will be interested in topics like real estate and buying their first home, mortgages, interest rates, credit cards etc. From almost the Hub’s inception, Zoocasa.com’s Penelope Graham has contributed excellent articles monthly on the real estate industry. Continue Reading…