Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

10 keys to picking the best Canadian income trusts and REITs

Canadian income trusts have always involved far more risk than most investors realize. This is why we’ve recommended so few of them in the past.

Income trusts are a type of investment trust that holds income-producing assets. Their units trade on stock exchanges, but they flow much of their income through to unit holders as “distributions.”

On January 1, 2011, Ottawa imposed a tax on distributions of income trusts. The new tax put income trusts on an equal tax footing with regular corporations.

Virtually all Canadian income trusts then converted into conventional corporations. But some are still out there: mostly real estate investment trusts (REITs).

Investing in trusts — and in particular oil and gas trusts — was risky, as the businesses that underpinned them needed steady cash flow. But that could stagnate during economic downturns. At the same time, we believed that investors should have looked for trusts with low capital expenditures and mature businesses.

More about Canadian Income Trust taxes

Canada offers special tax treatment for Canadian income trusts. When they flow their income through to their unitholders, they don’t pay much if any corporate tax. Investors pay tax on most of the distributions as ordinary income (although some distributions qualify as a tax-free return of capital).

Ottawa feels the income-trust business structure is appropriate for real estate investment trusts, or REITs, so it has exempted REITs from the income-trust tax.

Real estate investment trusts resemble Canadian income trusts, but with a key difference: REITs invest in income-producing real estate, such as office buildings, shopping centres and hotels. (We cover a number of carefully selected income trusts and real estate investment trusts in our Canadian Wealth Advisor newsletter.)

Regardless of whether or not they have converted, the basic tests we use to ferret out good investments and reject bad ones still apply, not only to Canadian income trusts, but to other types of investments, as well.

Keep “Investment Inputs” in mind when judging income trusts, or any investment

In evaluating investments, many investors focus on what we’d call “investment outputs,” such as earnings, dividends, cash flow, return on equity, sales growth and so on. These are all important, of course, but you shouldn’t focus on them to the exclusion of what you might call “investment inputs.”

Investment inputs are harder to work with than investment outputs, since it takes a judgment call to determine their risk or value. To give you a better idea of what we mean, here are 10 keys to picking the best Canadian income trusts and real estate investment trusts. We look each before recommending any income trust: Continue Reading…

How Baby Boomers can be frugal, yet still live it up

By Gloria Martinez

Special to the Financial Independence Hub

Baby Boomers have reached the point in life where they have either retired or are quickly approaching it, and that last paycheck is causing many to become more frugal. Being financially responsible is never a bad thing, but it shouldn’t take over your life. According to Forbes, being excessively frugal can “be a bigger problem for [a Baby Boomer’s] social life, family, and friends, not to mention physical health.” It is important that you find the right balance between saving and preparing for the future while also living in the moment.

Fulfill important responsibilities first

Before you can focus on having fun, take care of your health and well-being first so that it doesn’t become a constant worry. Some of the problems Baby Boomers face include declining rates of health due to obesity, diabetes, and various other health issues. Healthcare costs are continuing to rise as well, feeding into that constant need to save.

Your health is what will carry you through your Golden Years, but it comes at a cost. Now is the time to start exploring your healthcare options, including signing up for Medicare. Research Medicare Advantage plans, such as those offered by Humana, as they offer important health benefits and coverage, including dental, vision, and hearing, along with original Medicare benefits. While on the topic of your health and well-being, go ahead and make sure you have your end-of-life documents in order, including a living will, power of attorney, life insurance, etc. This might also including pre-paying funeral expenses or looking into long-term care insurance.

Explore ways to have frugal fun

Catch the Travel bug with a Road Trip

Traveling is a common activity for retirees, but when you add up airfare, travel insurance, and the cost of luxury destinations and cruises, travel becomes a huge expense. To save and make getting to your destination part of the fun, opt for a road trip. A road trip gives you the flexibility to travel anywhere, any time, with a personalized travel plan for a day trip, weekend getaway, week-long excursion, or a cross-country trek. Go at your own pace, and pack in the sights and experiences youwant to see.

Give that Hobby a try

Careers, families, and various other obligations don’t leave you with much free time, but retirement does. Maybe now you can finally find a hobby that you enjoy. Some of the most common Boomer hobbies are cooking, DIY projects, sports, and volunteering, but the possibilities truly are endless. You might even find a hobby that you can use to make a little extra cash. For example, you can sell produce from your garden at the farmers market, sell handmade furniture with your knack for woodworking, or make jewelry to sell at local boutiques and fairs. Continue Reading…

Maximizing your CPP benefits: 65 isn’t always the answer

Special to the Financial Independence Hub


As I prepared to write this month’s blog post, I came across an interesting U.S. study exploring how the structure of a company’s self-directed retirement plan might impact its participants’ investment selections.  When investment choices were listed alphabetically, the study found employees were apparently favouring the first few funds on the list. 

Arbitrary?  You bet.  But before we laugh too hard, I’ve noticed similar behaviours closer to home, especially when it comes to making best use of the Canada Pension Plan (CPP).

Assuming you’ve contributed to the CPP during your career, when should you start drawing your benefits?

If you guessed age 65, that’s understandable.  Unless you decide to receive a reduced benefit at a younger age (as early as 60), it’s when Service Canada automatically mails you your CPP application form, as if it’s a given you should fill it out right away.  65 is also the age many younger folks talk about when they dream of the day they’ll stop working.  It’s a number that’s become almost synonymous with “retirement.”  

That said, it’s an entirely arbitrary number when it comes to your own best financial plans. I can cite any number of reasons 65 might or might not be the right number for you.

There’s the prospect of receiving more benefit by waiting until age 70 to get started: currently 42% more than if you start taking it at age 65.  On the flip side, it may make more sense to start drawing a smaller benefit sooner if you are single and in poor health. 

As Financial Post columnist Jason Heath suggests, it’s worth treating your CPP like an RRSP for planning purposes.  To put this in perspective, Heath calculated that a lifetime CPP benefit starting at age 65 and assuming an age 90 life expectancy would be the same as having a $277,000 RRSP, earning 4% per year.  As Heath explains, “Whether you withdraw from other sources, or start your CPP, you are reducing the future income that you can earn from that source.”

So, when is it best to take these significant benefits compared to others that may be available to you?  Instead of simply signing up at age 65 as a given, why not give it some thought (or hire a planner to help you)? Continue Reading…

8 things you need to know about termination and severance pay

Photo by Pau Casals on Unsplash

By Kevin Press

Special to the Financial Independence Hub

Earlier this year I shared what I hope was a good-humoured look back at my being shown the exit after 14 years with one of the country’s major insurance companies. Because the news did not come as a surprise, I went into my “touchpoint” that Tuesday morning with a pretty good idea of what to look for in the package they put in front of me.

Like anything else, the more you know about what you’re owed and what you can reasonably negotiate, the better. In Ontario, for example, provincial employment law requires either written notice of termination, termination pay or a combination of the two, assuming you didn’t quit, you’ve been employed a minimum three consecutive months and you’re not guilty of misconduct. (There are additional exceptions; consult a lawyer.) Termination pay runs one to eight weeks in the province, depending on how long you were employed.

Severance pay is a separate matter for those forced to leave an employer. Your age, what kind of profession you’re in, how senior you are, what shape the job market is in and other factors will all be taken into consideration if you end up in court. Chances are though – with the help of a lawyer – you and your former employer can negotiate a satisfactory settlement.

It is a learning experience, to say the least. Eight big lessons:

  • What’s put in front of you is a starting point for discussion, not unlike a job offer. Do not sign off on a severance offer the day you’re fired. Hire a lawyer. Sleep on it. Discuss what you need with your partner or spouse. Think carefully about what you want and negotiate through your representative.
  • You’ve probably been told to expect one month of severance for every year of service. There is no guarantee you’ll land there. You may be offered less. Don’t be discouraged. If you’re offered more, don’t let that dissuade you from negotiating a better deal. Continue Reading…

Enable, don’t label … but whatever you do don’t call them ‘seniors’!

By Yvonne Ziomecki, HomeEquity Bank

Special to the Financial Independence Hub

When you are a marketer you tend to look at advertising through a different lens than everyone else – sometimes you are critical, sometimes curious, and sometimes you just admire the genius.  But it’s hard to assess your own advertising through the same lens, especially when you are in your mid forties and the product you market is for people who are retired.  That’s when you call for help!

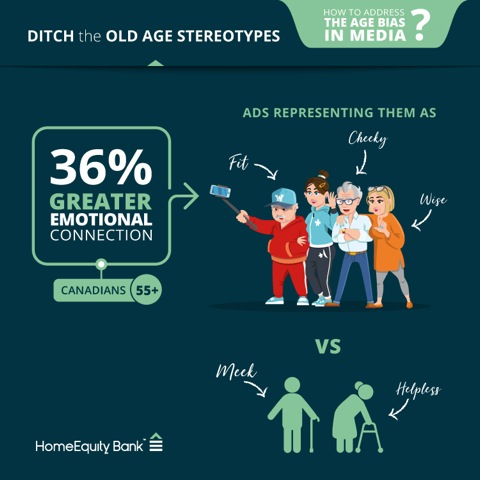
Last summer our company HomeEquity Bank, provider of CHIP Reverse Mortgages, launched new advertising campaign through a series of humorous ads developed and based on research insights, addressing the fact that older Canadians see themselves as active and able and completely in control of financial decisions related to their home.

Specifically: staying in the home they love.  Our research showed that 93%+ of older Canadians want to age in place.  We also learned that 80% of older Canadians don’t want to be called ‘Seniors’ and most prefer no labels to describe them or their peer group.

In order to better understand if our ads were hitting the mark we engaged the neuroscience research firm Brainsights to study the unconscious brain activity of 300 Canadian Boomers. Research participants were presented with approximately 1 hour of advertisements including our ads, other ads, movie trailers, promotional videos, etc.  Brainsights analyzed participants’ responses to all the content they saw. The findings revealed not only that many marketers were engaging in unconscious age bias, but also that Boomers were pushing back against offensive labels and aging stereotypes.

Research revealed 4 insights to help marketing resonate with Boomers:

•  Say goodbye to old age stereotypes. Today’s Boomers see themselves as being cheeky, mischievous, adventurous and capable. Old age stereotypes depicting 55+ Canadians as frail and fumbling will miss the mark. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.