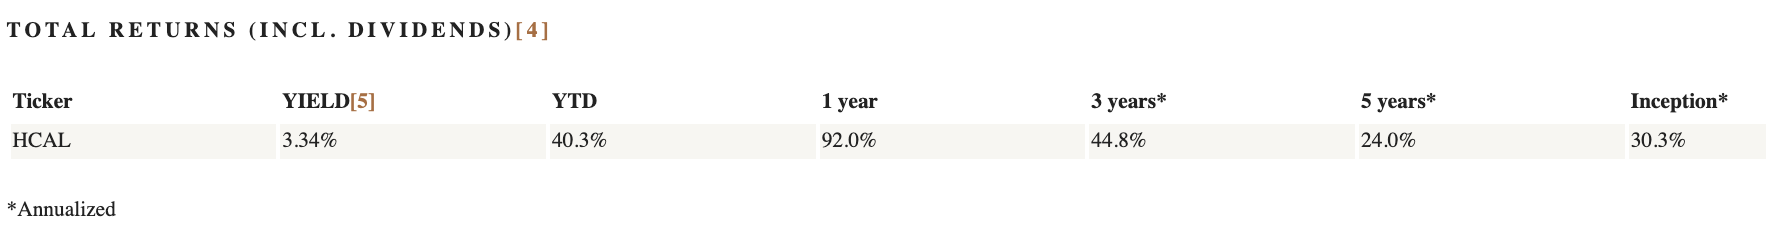Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Before you Decide: How do you Know if you made a Good Financial Decision?

Evidence over emotion. Process over prediction. Better decisions over better guesses.
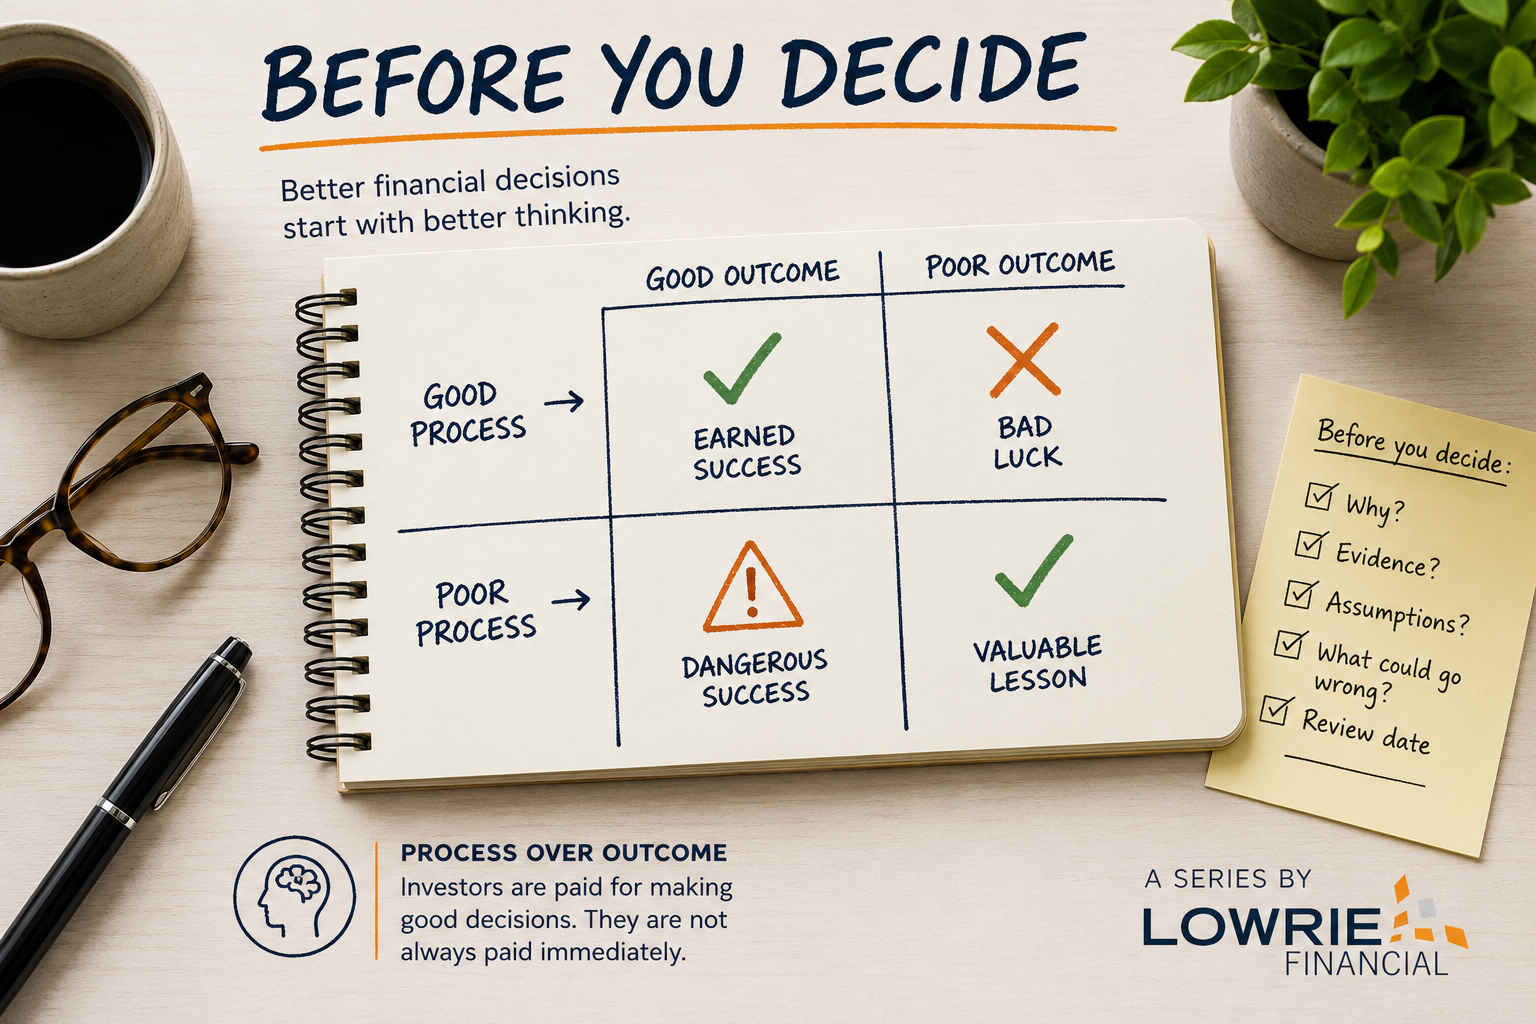
Image created with ChatGPT by Lowrie Financial

By Steve Lowrie, CFA

Special to Financial Independence Hub

Welcome to Before You Decide, a series about the decisions that shape our financial lives. Each article explores a common financial question through the lens of evidence, behavioural finance, and more than three decades of working with Canadian families. The goal is not to predict the future, but to make better financial decisions with the information available today.

A financial decision can be sensible and still produce a disappointing result. It can also be poorly considered and make money. That is what makes investing so difficult.

Most of us naturally judge our decisions by their outcomes. If an investment rises, we assume the decision was good. If it falls, we assume somebody made a mistake. Behavioural economists have a name for this tendency. They call it outcome bias.

Outcome bias is our tendency to judge the quality of a decision by the result it produced rather than by the quality of the reasoning that led to it. The problem is that luck sits between a decision and its outcome, which means a good result does not always prove that the original decision was sound.

Every important financial decision should therefore be judged twice. The first judgment should take place when the decision is made, based on the quality of the reasoning and the information reasonably available at the time. The second should take place much later, after the outcome is known.

Most investors only perform the second evaluation, and that is where many costly mistakes begin.

Every investor eventually faces two different questions: Did my investment work, and was it a good decision? Those questions may sound similar, but they are not the same.

Why is outcome bias especially relevant today?

A relatively small group of technology and artificial intelligence related companies has recently produced outsized returns. Investors who concentrated their portfolios in some of these companies have been rewarded handsomely, while investors holding broadly diversified global portfolios may be wondering whether diversification has become an expensive form of caution.

We have seen this movie before.

During the technology and telecommunications boom of the late 1990s, a relatively small group of companies dominated both market returns and investor attention. The technologies were real, and many of the companies were genuinely innovative. That did not mean every investment made sense or every price was justified.

The same distinction matters today. Artificial Intelligence (AI) may profoundly change the economy without making every AI-related investment a good decision at current prices.

For a Canadian investor, a concentrated position in AI-related stocks may also involve several overlapping risks. It can amount to a concentrated commitment to one sector, one country, one currency, and often a relatively small number of companies. Those risks may continue to be rewarded for years, but they remain risks nonetheless.

The important question is not simply whether the investment works. It is whether the decision itself was well reasoned, whether the risks were understood, and whether the position made sense within the investor’s broader financial plan.

What are the four possible outcomes of a financial decision?

Every financial decision eventually falls into one of four categories:
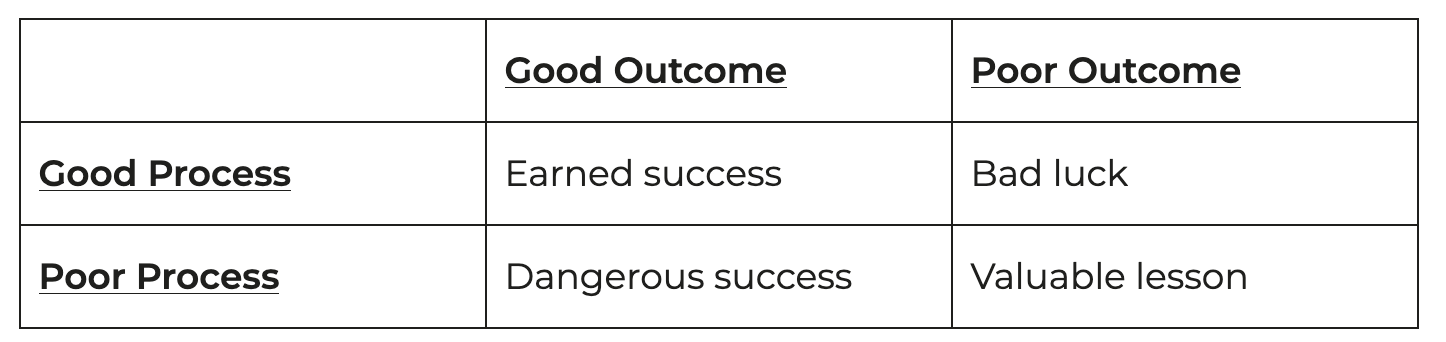
A good process combined with a good outcome is what every investor hopes for. You followed a sensible process, understood the risks, and received a favourable result.

A good process followed by a disappointing outcome is more difficult to accept, but it does not necessarily mean the process failed. Good decisions improve the odds, they do not guarantee a particular result.

A poor process followed by a poor outcome is painful, although at least the mistake is visible. Something in the original reasoning can be examined, understood, and improved.

The most dangerous combination is a poor process followed by a good outcome. In that situation, the result appears to validate the decision, confidence grows, and the same choice may be repeated with more conviction and more money behind it. Nothing in the outcome forces the investor to question the original reasoning.

This is outcome bias at its most expensive. A temporary success becomes a lasting lesson for entirely the wrong reason.

Why do investors judge decisions by their outcomes?

Looking at the result is easy. Examining the decision is much harder.

By the time most people make an important financial choice, they have usually considered taxes, investment products, market forecasts, retirement planning, family needs, and competing advice. Mental fatigue encourages shortcuts, and recent performance becomes one of the easiest shortcuts available.

If the investment made money, it must have been a good decision. That conclusion feels natural, but it is not reliable.

I explored this idea in an earlier article about choice overload and decision fatigue. One of the best-known studies in behavioural economics found that shoppers presented with twenty-four varieties of jam were much less likely to make a purchase than shoppers offered only six. More choice attracted more attention, but it produced fewer decisions.

Investors face far more than twenty-four choices. Individual companies, sectors, countries, currencies, investment styles, economic forecasts, and an endless stream of financial commentary compete for our attention every day. When the menu becomes overwhelming, we naturally look for an easier way to judge our decisions, and recent returns become that shortcut.

There is another problem. We examine our losses far more carefully than our successes. When an investment disappoints, we search for mistakes. When it performs exceptionally well, we rarely ask how much of the result may simply have been good fortune.

Success seldom asks us to defend our thinking, which is one reason poor decisions with good outcomes can survive for so long.

How can you tell the difference between skill and luck?

One useful test is to ask whether a skilled participant can deliberately produce a poor result.

In an activity dominated by skill, that is usually possible. A strong chess player can lose a game on purpose because the relationship between skill and outcome is direct enough to control.

Now think about a concentrated stock portfolio over a single year. Could you reliably make it lose money? Probably not. Unexpected news, changing interest rates, investor enthusiasm, government policy, and countless other factors could move the investment in either direction.

That does not mean skill has no place in investing. Skill appears in building a diversified portfolio, managing risk, controlling costs, minimizing taxes, and staying disciplined when markets become emotional. It also appears in knowing what can be controlled and refusing to pretend that everything else can be predicted.

One year’s return therefore tells us far less about skill than most of us would like to believe.

Why is one investment result not enough to judge a decision?

A single investment outcome contains a great deal of noise, while a pattern across many decisions tells us much more.

Researchers at The Wharton School at the University of Pennsylvania studied what happened when a large employer simplified the investment choices in its workplace retirement plan. Participants generally traded less, paid lower investment costs, and held more appropriate portfolios. The researchers estimated that lower costs alone could leave the average participant approximately US$9,400 better off over twenty years.

The participants did not become better investors because they learned to predict markets. They became better investors because the decision-making environment improved.

That distinction matters because better financial outcomes often come from better decision-making processes rather than better predictions.

What does outcome bias look like in real life?

Several years ago, I had a client who decided, against my advice, to sell a diversified investment portfolio and make a concentrated commitment to residential investment real estate in Toronto.

The decision did not happen in isolation. Another advisor was enthusiastically promoting recent real estate returns and presenting the strategy as an opportunity that should not be missed. Like many investment stories built on recent success, it appealed to a powerful fear of missing out. Continue Reading…
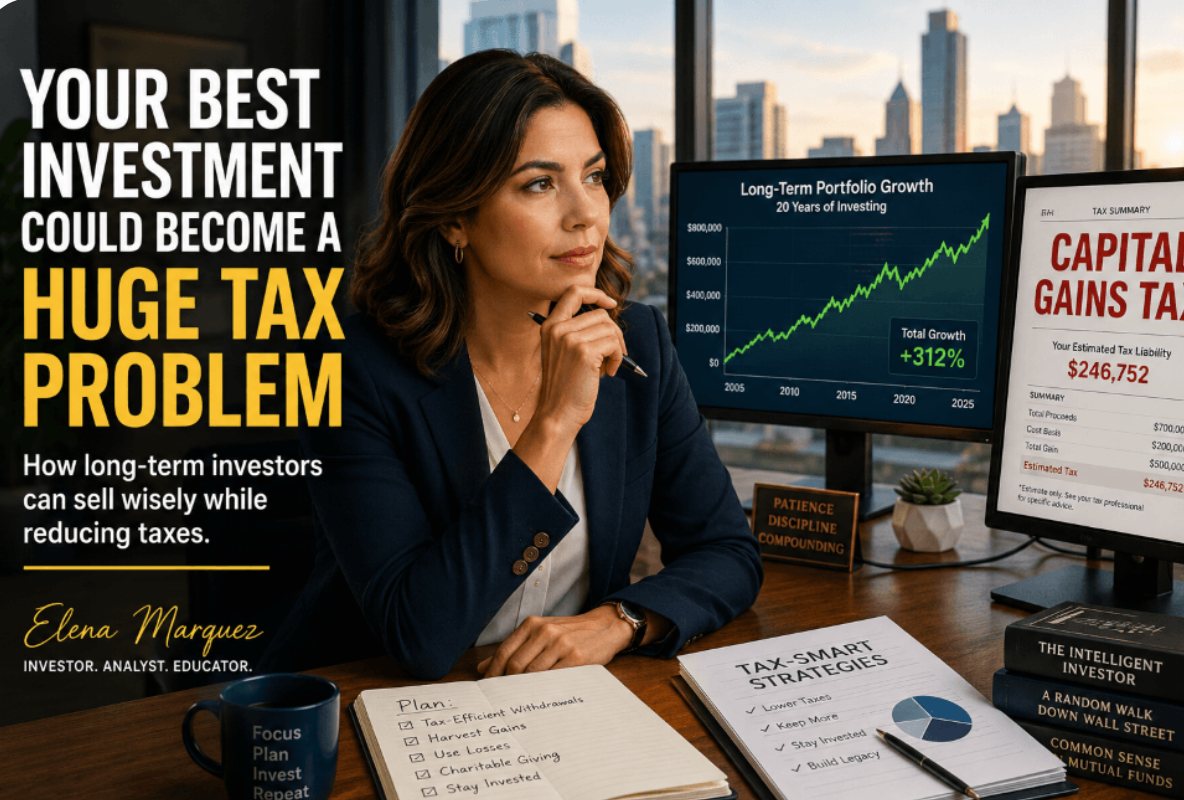
Your Best Investment could become a Huge Tax Problem

How American and Canadian investors can reduce capital gains taxes after decades of buying and holding.

AlainGuilot.com via Grok


By Alain Guillot

Special to Financial Independence Hub

Buying a broad-market ETF and holding it for decades is one of the simplest ways to build wealth.

You buy an ETF like the Vanguard S&P 500 ETF (VOO) for U.S. investors or the iShares S&P/TSX 60 Index ETF (XIU) for Canadian investors. You reinvest the dividends, ignore the daily market noise and continue adding money whenever you can.

Twenty years later, the strategy has worked beautifully.

But now you have a new problem: how do you reduce capital gains tax when selling an ETF that has increased enormously in value?

This is the strange punishment for being a successful long-term investor.

You followed the advice to buy and hold. You resisted panic selling. You avoided speculation and unnecessary trading.

Now your portfolio may contain hundreds of thousands of dollars in unrealized gains.

Selling a large amount in one year could create a substantial tax bill. It could also push your income into a higher tax bracket and affect income-tested benefits.

This is not merely a theoretical question for me. I have accumulated VOO and XIU for many years, and I know that selling a large portion at once could create a painful tax expense.

Fortunately, selling everything in one year is not the only option.

First, Understand the Capital Gains Problem

Suppose you invested $200,000 in VOO over many years.

Your investment is now worth $700,000.

Your unrealized capital gain is approximately:

$700,000 market value − $200,000 cost = $500,000 gain

You do not owe capital gains tax simply because VOO increased in value.

The tax is generally triggered when you sell or otherwise dispose of the investment.

That means you have some control over when the gain is realized.

The central question is not:

How can I avoid paying any tax?

A better question is:

How can I realize this gain gradually and pay the lowest reasonable amount of tax over my lifetime?

That change in perspective is important.

Reduce Capital Gains Tax by Avoiding One Giant Sale

The worst approach may be to sell the entire position without first calculating the consequences.

A large sale could concentrate decades of gains into a single tax year.

In both Canada and the United States, capital gains interact with the investor’s other income. Realizing more gains can bump you up to a higher tax braket and thus you will pay a higher tax rate.

A more efficient strategy is often to sell your ETF gradually.

For example, an investor could sell enough each year to cover:

  • Annual living expenses
  • Planned travel
  • Major purchases
  • Charitable donations
  • Portfolio rebalancing

Instead of realizing a $500,000 gain in one year, the investor might spread the gain over 10, 15 or 20 years.

This does not eliminate the tax.

It gives the investor more control over the rate and timing and hi might be taxed in a lower tax bracket.

Strategy 1: Sell more during Low-income Years

Some years are naturally better than others for realizing capital gains.

Good opportunities may arise:

  • After retirement but before pensions begin
  • Before collecting Social Security or government benefits
  • Before mandatory retirement-account withdrawals
  • During a sabbatical or period of reduced employment
  • In a year with large deductions
  • In a year when business income is unusually low

These lower-income years can create room to realize gains at a more favourable rate.

For American investors

The United States applies special federal tax rates to long-term capital gains.

Depending on taxable income, some long-term capital gains may fall into the 0% federal capital gains bracket. Higher-income investors generally face 15% or 20% federal rates, and some may also owe the 3.8% net investment income tax. State taxes may apply as well.

This creates a powerful planning opportunity.

An American investor with unusually low taxable income may sell some VOO, realize a long-term gain and potentially pay no federal capital gains tax on part of that gain.

The investor can then buy VOO again.

The newly purchased shares receive a higher cost basis, reducing a future taxable gain.

For Canadian investors

Canada does not have a special 0% capital gains bracket comparable to the American system.

Instead, only a portion of a capital gain is included in taxable income. The proposed increase in Canada’s capital gains inclusion rate was cancelled, leaving the one-half inclusion system in place.

If a Canadian investor realizes a $20,000 capital gain, $10,000 is generally included in taxable income under the one-half inclusion rate.

The final tax depends on the investor’s federal and provincial marginal tax rates.

A Canadian investor with little other income may therefore realize gains at a relatively modest tax cost. The investor can repurchase their ETF immediately, increasing the adjusted cost base.

This practice is known as capital gain harvesting.

Strategy 2: Harvest Capital Gains every year

Most investors have heard about tax-loss harvesting.

Capital gain harvesting receives far less attention.

Here is how it works:

  1. Estimate your taxable income for the year.
  2. Calculate how much additional capital gain you can realize without entering an undesirable tax bracket.
  3. Sell enough of your ETF to realize that gain.
  4. Repurchase the same ETF inmediately after selling it.
  5. Record the transaction and update the cost basis.

The investor remains invested while gradually increasing the tax cost of the portfolio.

Over many years, this can reduce the unrealized gain that remains in the account. I use this strategy every year. I sell a portion of my investments, realize some capital gains, and buy the same investment inmediately after selling it.

Can you buy the same ETF back immediately?

Yes, when you sold it for a gain.

The American wash-sale rule and the Canadian superficial-loss rule are designed to restrict the recognition of losses when substantially identical securities are quickly repurchased.

They do not generally prevent an investor from repurchasing an investment immediately after realizing a gain.

Capital gain harvesting can therefore be completed without remaining out of the market for 30 days.

The disadvantage is that you are paying some tax earlier than necessary. As a citizen of this wonderful country, I don’t mind paying some taxes on my gains, as long as those taxes are not exessive and feel as a punishment for my success.

Money paid in tax today can no longer remain invested and compound.

The strategy is most attractive when the current tax rate is lower than the rate you reasonably expect to face later.

Strategy 3: Use Capital Losses to Offset your ETF Gains

A diversified portfolio may contain investments that have declined in value.

Selling one of those investments creates a capital loss that may offset part of the gain realized from selling your ETF. This strategy is called Tax-loss harvesting.

For example:

  • Gain from selling VOO: $30,000
  • Loss from selling another investment: $12,000
  • Net capital gain: $18,000

This allows the investor to reduce the VOO position while limiting the immediate tax bill.

United States

American investors can use capital losses against capital gains.

When losses exceed gains, a limited amount may generally be deducted against other income, with unused losses carried forward to later years.

The wash-sale rule must be considered before repurchasing the losing investment.

Canada

Canadian net capital losses can generally be used against taxable capital gains.

Unused net capital losses may normally be carried back as far as three years or carried forward to future years.

Canada’s superficial-loss rule may deny an immediate loss when the investor—or an affiliated person—buys the same or identical property during the restricted period and still owns it 30 days after the sale.

Again, this rule matters for losses, not gains.

Strategy 4: Donate your ETF instead of Cash

Investors who regularly support charities should consider donating appreciated ETF shares directly.

This can be much more tax-efficient than selling your ETF and donating cash.

For American investors

An American investor who donates qualifying appreciated securities held for more than one year may generally avoid recognizing the embedded capital gain.

The investor may also qualify for a charitable deduction, subject to deduction limits, documentation requirements and whether the investor itemizes deductions.

The charity receives the shares and can sell them without creating a capital gains tax bill for the donor.

Instead of donating $10,000 in cash, the investor could transfer $10,000 of his long held ETF containing a large unrealized gain.

The investor keeps the cash and removes some of the portfolio’s oldest, lowest-cost shares.

For Canadian investors

Canada also offers favourable treatment for direct donations of publicly traded securities to registered charities.

Qualifying donations can receive a zero capital-gains inclusion rate, while the donor may also receive a charitable donation tax credit.

The important word is directly.

Selling your ETF first and donating the cash may trigger the capital gain. Transferring the ETF shares directly to the charity may avoid it.

This is one of the few strategies that can genuinely eliminate the tax on part of an appreciated ETF position.

Of course, it only makes financial sense for money that the investor already intends to give to charity.

Strategy 5: Choose which Shares to Sell

This is one area where the American and Canadian systems differ significantly.

American investors may identify specific shares

An American investor may have purchased his favorite ETF at many different prices.

Some shares may have a cost basis of $150, while newer shares may have a basis of $500.

When selling, the investor may be able to instruct the broker to sell specific shares.

Selling the highest-cost shares first produces a smaller taxable gain.

For example:

  • Sale price: $600
  • Old share cost: $150
  • Gain: $450

Compared with:

  • Sale price: $600
  • Newer share cost: $500
  • Gain: $100

Specific-share identification can help American investors control which gains are realized. Proper instructions and records are essential. IRS guidance requires investors to maintain records supporting the basis of their investments.

Canadian investors use an average adjusted cost base

Canadian investors generally cannot select the highest-cost ETF shares and pretend those were the only units sold.

Identical securities are pooled together.

The investor must calculate the average adjusted cost base of all identical ETF units held in non-registered accounts. The gain on a sale is based on that average cost.

This makes accurate recordkeeping especially important.

Broker records may not always correctly combine ETF held across multiple Canadian taxable accounts.

Honestly I prefer the Canadian systeme of average adjusted cost much better. I have been making many different purchases during more than 10 years. It’s a headache to keep record of that small purchase I did of the XIU ETF 10 years ago.

Strategy 6: Keep Accurate Records

Before worrying about how to reduce capital gains tax, make sure the gain has been calculated correctly.

An incorrect cost basis can produce an unnecessarily large tax bill.

The records should include:

  • Every purchase
  • Reinvested distributions
  • Brokerage commissions
  • Stock splits
  • Transfers between brokers
  • Return-of-capital distributions
  • Previous sales
  • Currency conversions, when applicable

Special issue for Canadians holding U.S ETFs in U.S. dollars

U.S. ETF trades in U.S. dollars, but Canadian taxes must generally be calculated in Canadian dollars.

The purchase cost must be translated into Canadian dollars using the appropriate exchange rate at the time of purchase. The sale proceeds must also be translated using the relevant exchange rate at the time of sale.

A gain that appears to be modest in U.S. dollars may be larger in Canadian dollars if the Canadian dollar weakened during the holding period.

The CRA calculates gains by subtracting the adjusted cost base and selling expenses from the proceeds of disposition.

Investors who accumulated a U.S. ETF over 20 years may need to reconstruct many transactions.

That effort can be worthwhile.

Finding forgotten purchases, commissions or reinvested distributions may increase the adjusted cost base and reduce the taxable gain.

Strategy 7: Stop Reinvesting Dividends

An investor who is approaching retirement may not need to continue reinvesting every dividend from their ETF.

Instead, the cash distributions can be used for living expenses.

Continue Reading…

How to play the AI game

By Mark Seed, myownadvisor

Special to Financial Independence Hub

Hi Passionate DIY Investors!

Welcome to a new Weekend Reading edition on the curious subject of how to play the AI game in your portfolio.

How to play the AI game 

Image by Pexels

Onto the theme for this week, this article by Jon Chevreau caught my eye: AI for conservative investors

Within the article, there are a few ETFs I’ve considered to adjust our portfolio for AI success long-term:

  • Fund: Global X Artificial Intelligence & Technology ETF (NASDAQ: AIQ)” that ETF provides balanced diversification across the entire AI ecosystem, including hardware, software platforms, and foreign AI leaders. Top holdings frequently include giants like Nvidia, Broadcom, and Apple. 
  • Beyond that article you can also consider Fund: TD Global Technology Leaders Index ETF (TSX: TEC) – with a lower MER and TEC is also heavily-traded in Canadian-dollars so this is a low-cost option for global tech. 
  • Finally, you can stick with what I * used to own QQQ or a Canadian-listed ETF that clones it – those ETFs invest in the top-100 companies on the NASDAQ-100 index so it’s a very passive way to own tech and AI-related tech.

* I used to own QQQ but I sold all of it about a year ago now in favour of 1. portfolio simplicity and 2. Canadian-listed ETF investing. I’m better for it – since my two-fund Canadian-listed ETF solution is up about 12% combined YTD for almost 50% of my portfolio and we don’t need to worry about AI run-ups or bubbles anymore in doing so. We ride diversified returns…

(Link here if above did not work.)

Other than some non-registered transfers/contributions to our TFSAs in early 2027, I’m not sure I’m going to be changing much in our portfolio for the rest of the year. I’ll update this post too to chronicle my process in retirement.

Like Jon from the article, although in my early 50s vs. 70s, from where I sit I’m planted firmly in the retirement risk zone whereby the early retirement years need to be monitored carefully: which also implies to me no major portfolio overhauls either. Just some adjustments from time to time.

HCAL and Hamilton ETFs: A Growth Story


Hamilton ETFs

By Hamilton ETFs

(Sponsor Blog)

In May 2020, during the early days of the pandemic and while bank stocks were depressed, we presented a webcast entitled “Credit Cycle is Coming – What to Expect.”

During that webcast, we (correctly) predicted that during the expected downturn, the new loan loss accounting would deepen the credit cycle for the Canadian banks and importantly shorten its duration to 2-3 quarters (versus the historical duration of a credit cycle of 4-6 quarters).

Two quarters later, in October, we followed up with a presentation/webcast entitled “Canadian Banks: Cycle is (Basically) Over,” explaining why we believed the cycle was ending, and that the upside from earnings normalization was material.

Demonstrating our conviction, we launched HCAL: the Hamilton Enhanced Canadian Bank ETF, Canada’s first modestly levered ETF on October 14, 2020. We argued that its higher yield and growth potential relative to the Canadian banks created an excellent opportunity for long-term investors to take advantage of the looming recovery. We also noted that notwithstanding its modest leverage of 25%, its volatility profile was not meaningfully different than owning an individual Canadian bank stock[1].

In the year that followed, Canada’s Big Six bank stocks recovered much faster than the market anticipated, due to an improving macro environment and rapid normalization of earnings supported by large reserve releases. In 2021, HCAL rose more than 51%, outperforming the Solactive Equal Weight Canada Banks Index by over 20%[2].

HCAL’s success marked an important milestone in our growth and helped pioneer a new category in Canada, demonstrating that modest leverage, when applied thoughtfully to high-quality stocks and trusted sectors, could enhance long-term returns.

Since inception, HCAL has generated an annualized return to investors of 30.3%, with a higher yield and similar volatility profile to the Big Six Canadian banks (more below).

As a result, HCAL now has over $1 billion in assets under management (AUM), making it the seventh member of the Hamilton $1 billion-and-over club.

In Canada, Banking is King

Known for their consistent dividends and wide ownership, Canada’s Big Six banks are considered among the most reliable blue-chip companies in the country and the backbone of the economy and stock market.

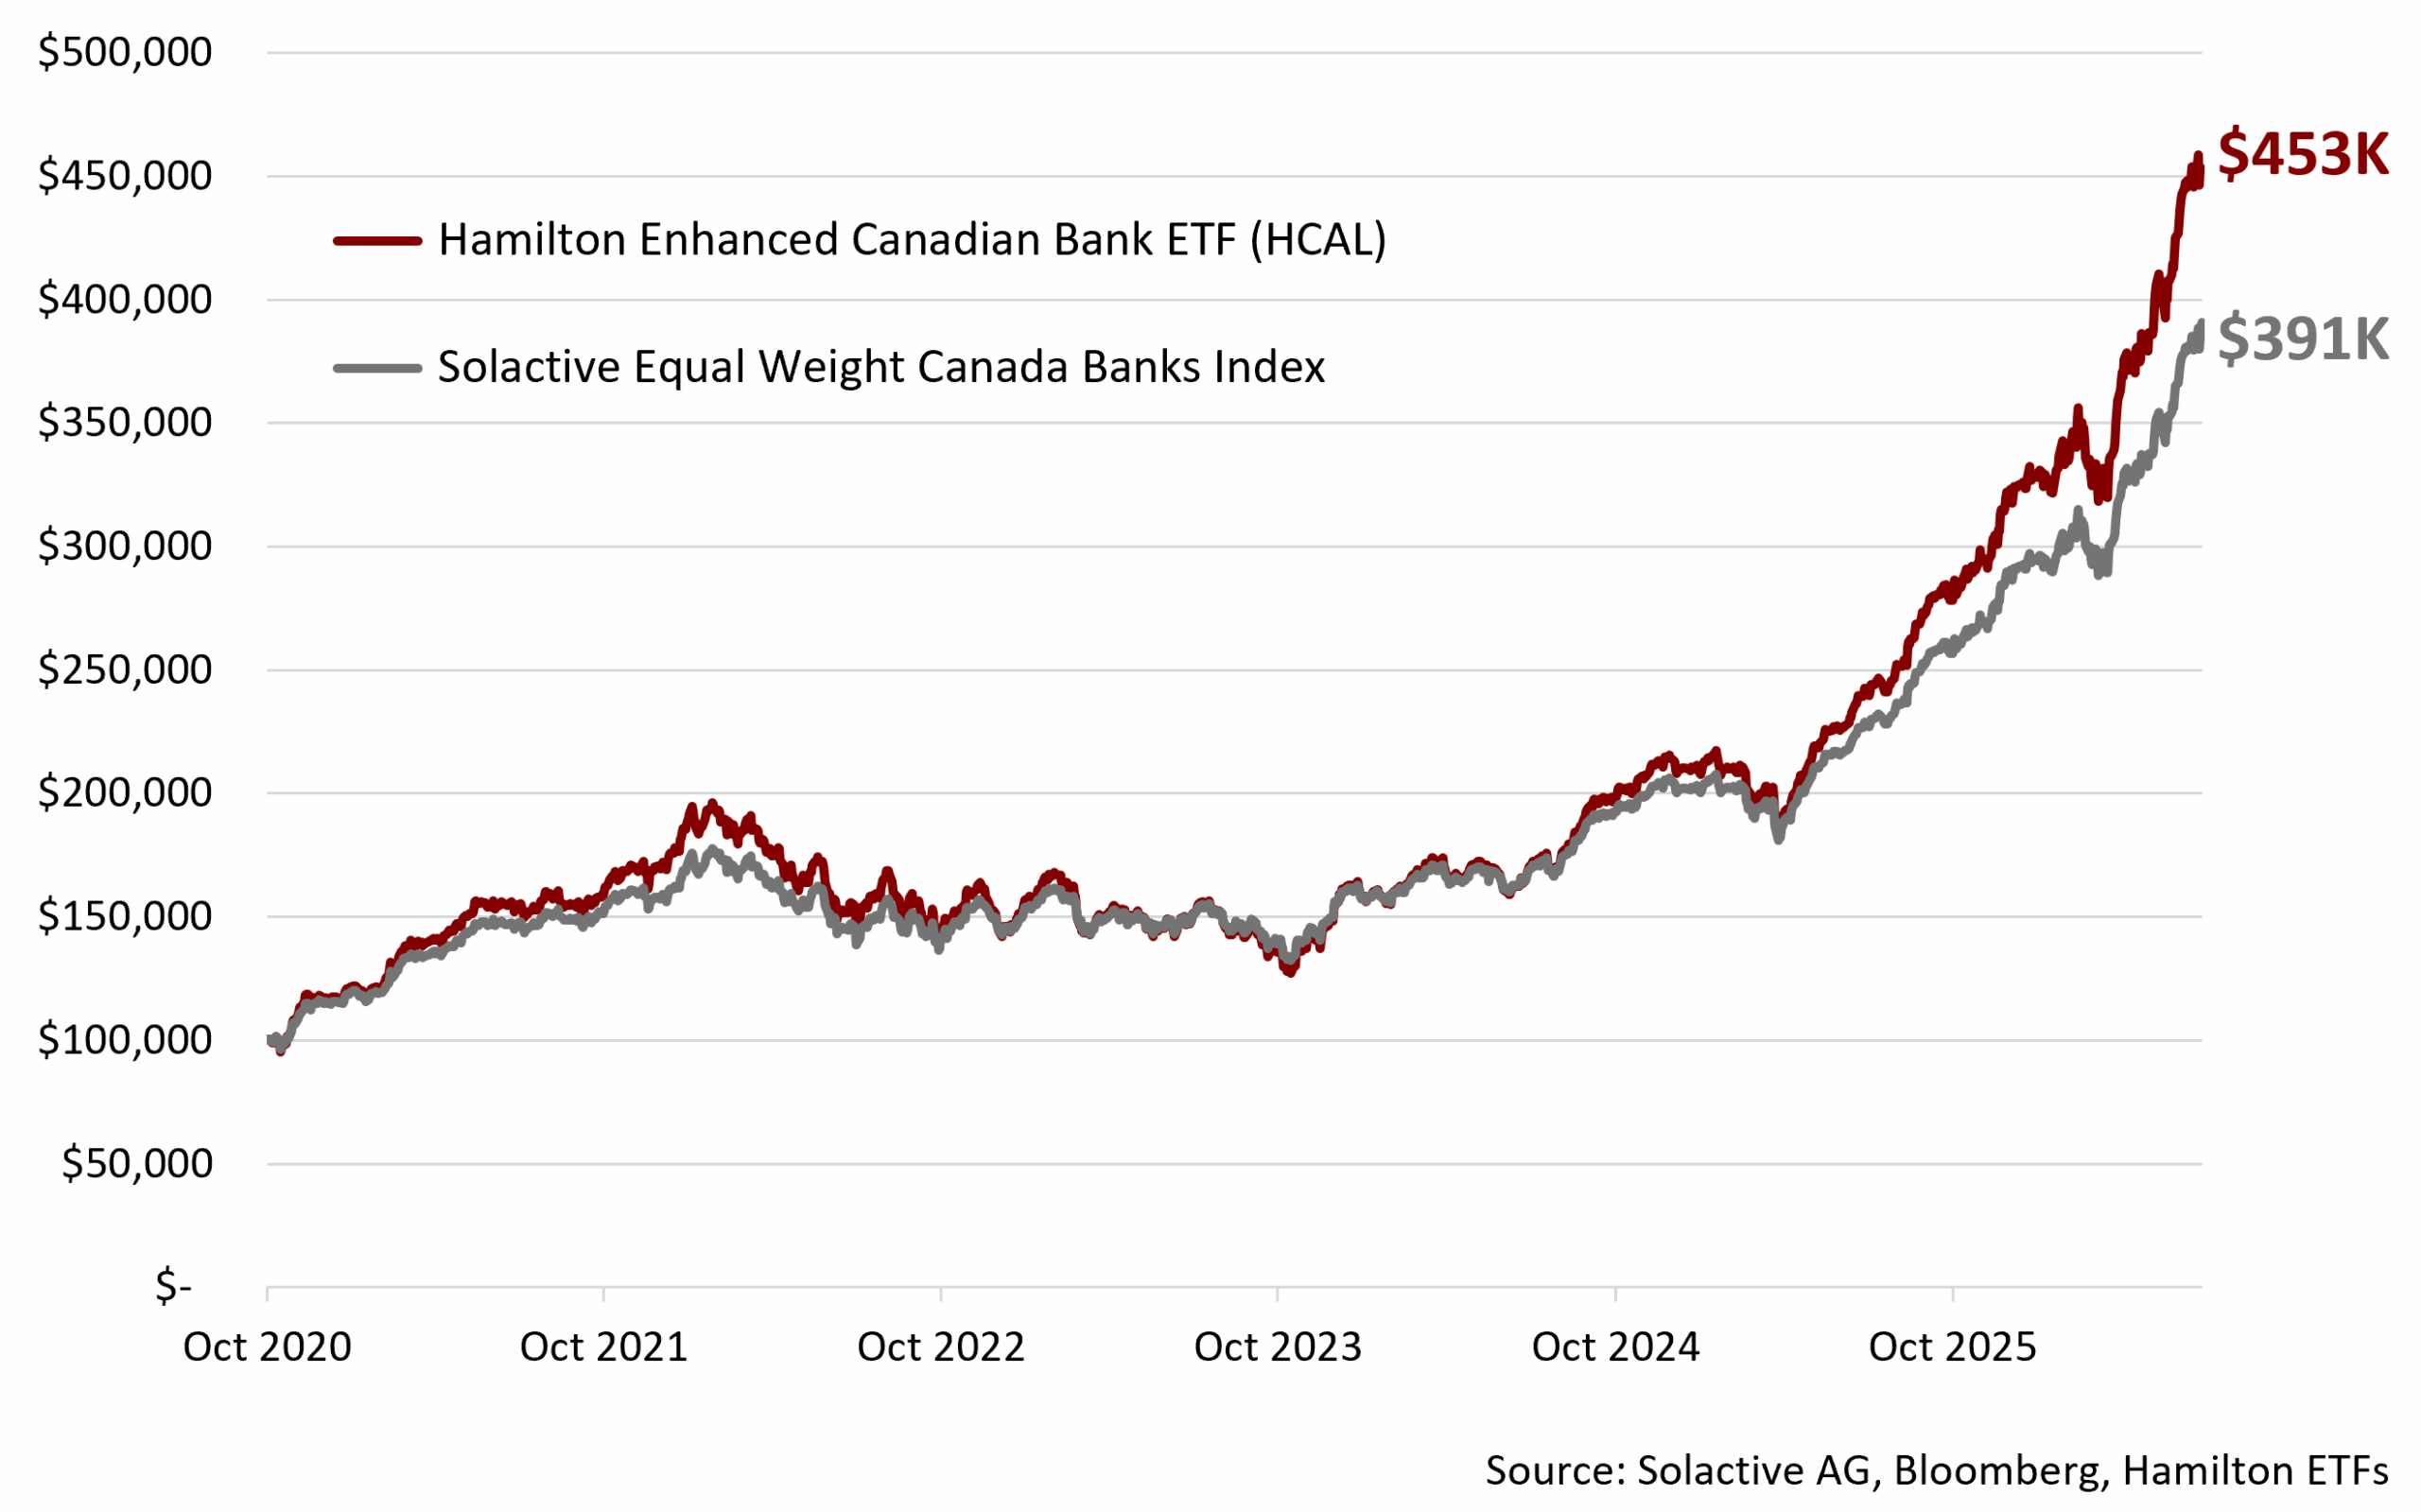
Put simply, for every $100 you invest, you get approximately $125 exposure (net of financing costs), and this approach has delivered higher monthly income and higher long-term returns since HCAL’s inception when compared to the Canadian bank index, specifically the Solactive Equal Weight Canada Banks Index (“Canadian Bank Index”.)

HCAL vs. Canadian Bank Index — Growth of $100K[3]

A Symbol of Hamilton Innovation and Rigour

Born out of inventive thinking during a time of uncertainty for the banking sector, HCAL has grown to more than $1 billion in assets under management and become an important part of Hamilton ETFs’ growth and story. Its success reflects our focus on developing thoughtful, differentiated investment solutions, which is key to the Hamilton ETFs ethos.

“As an ETF provider, you want to offer products that make your clients money, it can’t just be about inflows to you. We always ask: is this a good product? Does it add value and choice to investors?” said Executive Chairman and Co-Founder Robert Wessel.

Some of the factors that have made HCAL stand out:

  1. Owning blue-chip Canadian banks: HCAL provides exposure to the Canadian banks, one of Canada’s most trusted sectors with an uncommonly long record of dividend sustainability.
  2. Modest leverage/enhanced structure: HCAL borrows 25% at institutional borrowing rates and invests approximately 125% in the HAMILTON CHAMPIONS™ Canadian Bank Equal-Weight Index (HEB), which owns the Big Six banks.
  3. Similar volatility to an individual Canadian bank stock: Since inception, the increase in volatility from the enhanced structure roughly offsets the decline in volatility from diversification. As a result, HCAL has had a volatility profile roughly equal to owning any single Canadian bank stock (see chart below).

The outcome?

HCAL has provided investors with strong returns over its 5-year track record. Since inception, it has provided investors with both a higher long-term return than the Big Six banks, at 30.3% annualized return (see table below) and higher yield with similar volatility to the Big Six Canadian banks.

Hamilton ETFs: Pioneers of Enhanced ETFs

Launched in October 2020, HCAL was Canada’s first “enhanced” ETF followed by the second, the Hamilton Enhanced Canadian Covered Call ETF (HDIV), which launched in July 2021. When creating HCAL, we chose 1.25x exposure, which we believe is a “Goldilocks” level of leverage, because our analysis and back-testing of the strategy suggested higher long-term return potential while maintaining a volatility profile similar to that of an individual Canadian bank stock[6]. Continue Reading…

Dogs of the TSX Dividend Stock Picks

By Kyle Prevost, MillionDollar Journey

Special to Financial Independence Hub

I want to make it clear that the Dogs of the TSX is not something that I created. In fact, it’s actually an American idea. Michael B. O’Higgins wrote a book called the Dogs of the Dow back in 1991, and the idea was later adapted to the Canadian market. I first came across the “Dogs” method of stock picking when MoneySaver magazine started a column titled BTTSX – short for Beating the TSX – dividend stock strategy. (Click here to skip directly to my 2026 picks).

The theory behind the Dogs of the TSX strategy is to look for solid cash-flow-positive stocks that have fallen out of favour for one reason or another. In other words, you’re looking to take advantage of short-term market inefficiency when it comes to the pricing of blue-chip Canadian stocks. A low price and a high dividend results in a high dividend yield.

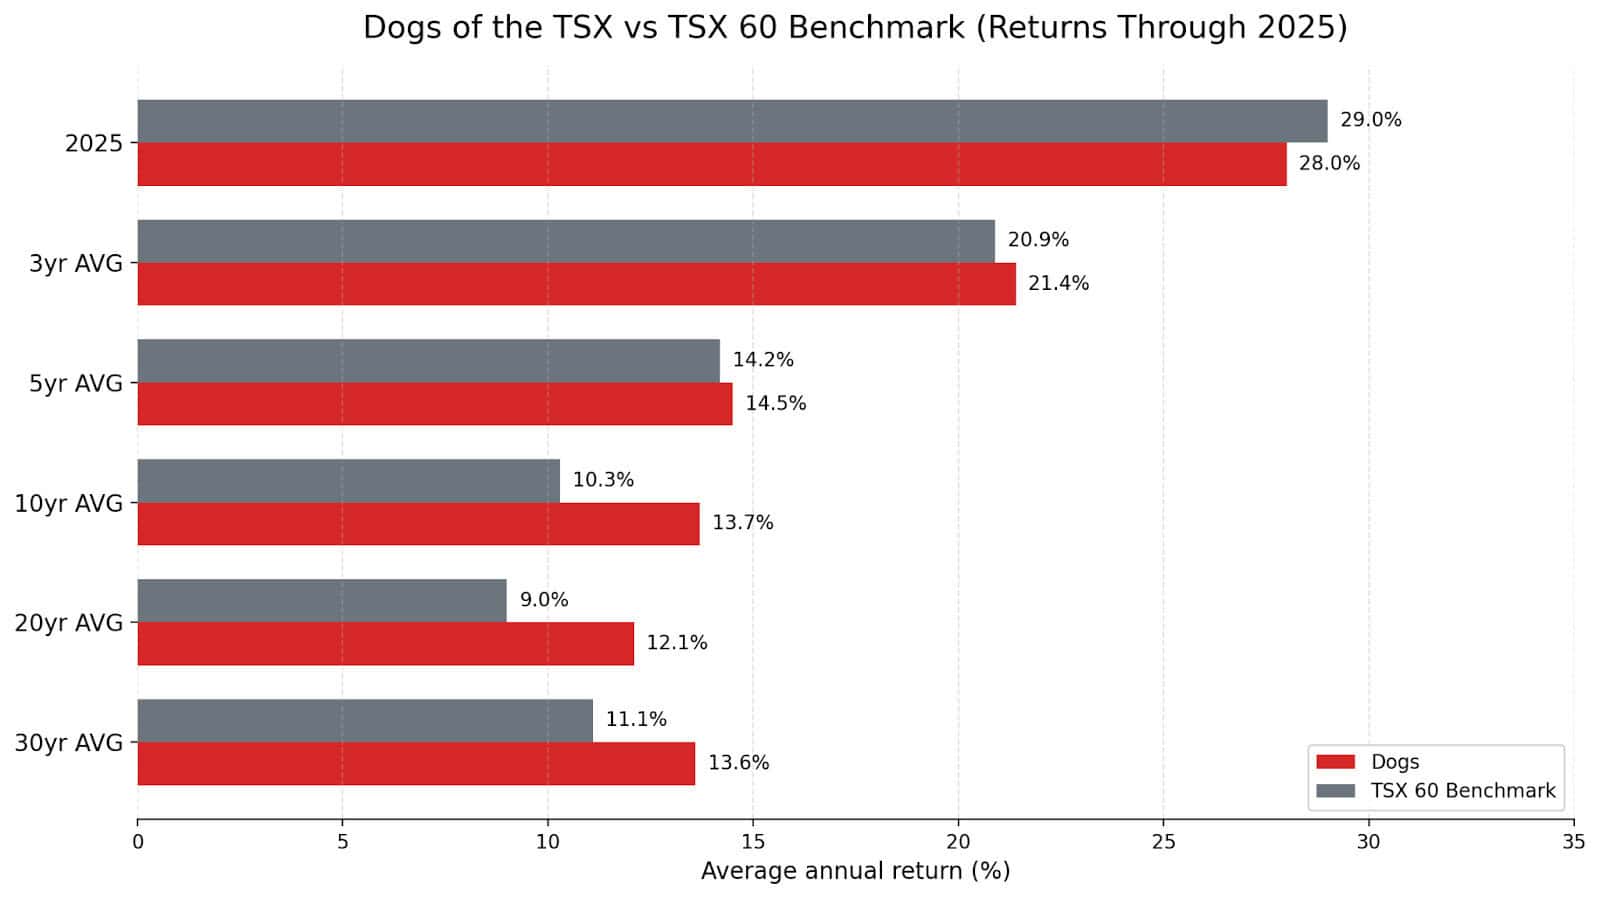
The chart below illustrates the total return (dividends plus price capital gains) versus the TSX 60 benchmark over the years. Looking at 2025, our Dogs of the TSX portfolio of 10 stocks was very similar to the overall TSX 60 index. In fact, the average return lead that the BTTSX strategy has over 3- and 5-year periods is fairly minor. That said, when we look out over the longer terms, we see consistent outperformance in the range of 2-3% per year.

dogs of tsx vs benchmark2025

If you had $100,000 invested 30 years ago, the constant difference in compounding would have left you about $2 million richer today had you followed the Dogs of the TSX BTTSX strategy.

When we look back over the last year, the banks had a great year, and the telecommunications companies continued to get beat up. Consequently, we’re going to lose TD off of the list this year (its share price has finally caught up to its dividend payout).

In its pure original form, the Dogs the TSX strategy simply involved ranking the companies in the Toronto Stock Exchange 60 index (aka: TSX 60) by their dividend yield. The highest yield gets the top spot. Then you simply invest equal amounts in all top ten dividend yield stocks.

The idea is that investing in companies that have relatively high free cash flow – but relatively low share prices – is an excellent way to systemically outperform the broader market. No need to pick stock winners with any sort of fancy algorithm – just choose dividend stocks that are out of favour and consequently have high yields.

The average yield for the stocks making the 2026 Dogs of the TSX is about 5.26%. That’s down about 1% from last year – showing that valuations on these companies have raced ahead of their free cash flow and dividend payouts. (In theory, it could also be the case that these companies cut their dividends, but since only BCE did that, we can eliminate that theory.)

In my own implementation of the BTTSX strategy I often eliminate Real Estate Investment Trusts (REITs), and any stocks that have cut dividends OR have insanely high payout ratios (foreshadowing a future dividend cut). Those rules helped me avoid the Algonquin disaster in years past. I didn’t trim much of my BCE holdings before the cut, and I have to admit that I’m getting nervous about Telus: but haven’t pulled the trigger yet.

You’ll notice that my Dividend Dogs of the TSX list has a lot in common with my Best Canadian Dividend Stocks list that I update monthly. There’s obviously a lot of overlap in selecting value-driven, stable, Canadian company stocks.

Top Canadian Dogs of the TSX Pick for 2026: Emera (EMA)

My 2024 and 2025 Dogs of the TSX picks were identical to one another: Power Corp (POW).

While I looked pretty average in January last year, I look pretty darn smart today! That’s because Power Corp saw a total return of over 75% last year!!

In fact, the share price has done so well, that it has outpaced the dividend, and dropped POW right off the BTTSX list for 2026. The biggest driver was Great-West Life’s robust earnings. On top of that, IGM has quietly stabilized its asset base, and Wealthsimple continues to expand its footprint, with more rumours swirling about that Schedule 1 bank licence approval. Investors are finally pricing in the fact that Power Corp isn’t just a stodgy old financial holding company. It’s a well-run, diversified business with growth levers in both traditional finance and the fintech space.

The other stock I highlighted as a Dogs of the TSX stock to watch was TD Bank: and again, TD did so well (total return of about 70%!) that it’s not on the list this year!

It is nearly impossible to duplicate those results going forward. Those two picks both hit the perfect tailwind, and while I believed they were significantly undervalued 12 months ago, I would have told you that you were crazy if you said they’d have total returns of more than 50%, nevermind 70%!

Now, I’m not nearly as bullish on the overall market going into 2026 as I was in 2025. I don’t see any screaming “buy now” deals out there. That’s why my 2026 Dogs of the TSX pick is Emera.

It’s definitely not a stock that’s going to light up Reddit boards. What it is, is a regulated utility with a high starting yield, visible growth, and a US-expanding business mix that I think the market is still undervaluing.

At its core, Emera is a regulated electric and gas utility operator. More than 90% of its earnings come from regulated sources, and roughly 96% of its assets sit inside rate-regulated frameworks. That price stability is exactly what you want when you’re building a dividend-focused portfolio in a market that feels a bit stretched.

Emera operates across Canada, the U.S., and parts of the Caribbean, but the business is much simpler than the geographic footprint suggests.

The short version is this: Florida’s data center growth is the story. Canada is secondary. Everything else is noise.

Emera’s crown jewel is Tampa Electric, which sits under its TECO Energy subsidiary in Florida. That operation benefits from population growth, constructive regulation, and a steady stream of capital investment tied to grid hardening, electrification, and storm resilience. If you believe Florida continues to grow and data centers continue to put pressure on electrical grids (and all signs point that way), Emera has positioned itself very well.

One of the reasons Emera stands out to me right now is management’s five-year, $20 billion capital plan, announced late in 2025. This isn’t vague guidance. It’s a detailed roadmap that extends 7–8% consolidated rate base growth through 2030, with nearly 80% of that capital earmarked for Florida.

That’s meaningful growth for a regulated utility. And importantly, it’s growth that regulators expect and allow utilities to earn returns on.

Canadian assets (which are mostly through Nova Scotia Power) do introduce some political and regulatory friction. But when I look at where Emera is allocating capital, it’s clear management understands where the best risk-adjusted returns are coming from. The payout ratio is pretty darn high, and the balance sheet carries too much debt for my liking. That said, with interest rates coming down in the US, and regulations coming off the books, I like the short- and medium-term prospects.

In a market where many stocks feel priced for perfection, Emera feels priced for caution. That’s what I’m looking for in 2026.

June 2026 Update: So far so good, Emera. It’s up about 7% on the year, which means that it is slightly outpacing the overall TSX 60 index. When you consider that its dividend is higher than that of a TSX 60 ETF, the gap opens up a bit more. American assets and earnings continue to perform well (as I figured they would). So while it’s not performing as well as my Toromount Industries Dividend King pick, or as well as Power Corp (which just continues to power on after last year’s incredible run, up 13% so far in 2026), Emera continues to add steady dividends and capital gains to my portfolio.

One thing to note in regards to Power Corp (which still holds a prominent place in my TSX Dogs Portfolio after its big move last year) is that its Wealthsimple subsidiary continues to post explosive growth. While I don’t at all like the direction the company is going from a user perspective, it is undeniably finding new ways to monetize its young customer base. The company recently made waves by saying it was going to be one of the first Canadian companies to bring predictive markets (think online betting like Kalshi or Polymarket down in the States) to Canada. If casinos are a license to print money, online casinos are a license to print money right across an entire country!

Visit DSR & Get Our Exclusive Discount

Dogs of the TSX Dividend Stock Strategy Implementation

Here is the step by step procedure of how this strategy is implemented: Continue Reading…