Victory Lap

Once you achieve Financial Independence, you may choose to leave salaried employment but with decades of vibrant life ahead, it’s too soon to do nothing. The new stage of life between traditional employment and Full Retirement we call Victory Lap, or Victory Lap Retirement (also the title of a new book to be published in August 2016. You can pre-order now at VictoryLapRetirement.com). You may choose to start a business, go back to school or launch an Encore Act or Legacy Career. Perhaps you become a free agent, consultant, freelance writer or to change careers and re-enter the corporate world or government.

Wrapping our Heads around Income

Image: Franklin Templeton/iStock

By Franklin Templeton

(Sponsor Content)

For those who depend on investments to provide a portion of their yearly income, 2022 has been a tough slog, to say the least; but take heart: it’s almost over.

Of course, no one can say with certainty that 2023 will be better. Persistently high inflation, ongoing central bank monetary tightening and the increasing likelihood of a recession have made for volatile markets, and this uncertainty could continue well into next year.

Under the circumstances, it’s not surprising that weary investors have poured money into GICs (guaranteed investment certificates) and other cash equivalents. Even with today’s higher interest rates, however, returns remain well below the inflation rate, and unless held in registered accounts, they are fully taxable. Liquidity can also be problematic as most GICs require a locked-in period, with penalties for redeeming before maturity. If you need flexibility, you’ll pay for it with lower returns.

Reliable income requires diversification

Without doubt, GICs have their place: but the proverbial advice about placing all your eggs in one basket still applies. Diversification is as important for income portfolios as it is for equities, and the sources of income should be as uncorrelated to each other as possible. One way to easily bump up the level of income diversification is through a managed program (sometimes referred to as a wrap account) which bundles together different investment vehicles, strategies, styles and portfolio managers in one or more “umbrella” portfolios directed by a governing team of portfolio managers.

20 years of income generation

One of the earliest programs managed in Canada was Franklin Templeton’s Quotential program; in fact, this year marks the program’s 20th anniversary. Of its five globally diversified, actively managed portfolios, the aptly named Quotential Diversified Income Portfolio (QDIP) is designed to generate high, consistent income from multiple uncorrelated sources. Canadian and international fixed income assets form the core of the portfolio, but for added flexibility and performance enhancement, about one-quarter of the portfolio is invested in blue-chip Canadian and international equities selected for their income-generating  dividend yields and long-term growth potential.

“T” is for Tax Efficient

Reliability solves much of the income puzzle, but an important missing piece is the tax burden. Taxes can eat away at the income generated from investments, especially if you are still earning a salary or receiving significant income from other sources. All Quotential portfolios are available in Series T, which offers a predictable stream of cash flow through monthly return of capital (ROC) distributions. From a tax perspective, ROC is treated more favourably than interest or dividend income. The tax efficiency also extends to the tax deferral of capital gains that can help you better plan for when you pay tax. For snowbirds and others who spend extended periods south of the border, distributions from Series T are available in U.S. dollars for a number of funds, including Quotential Diversified Income.
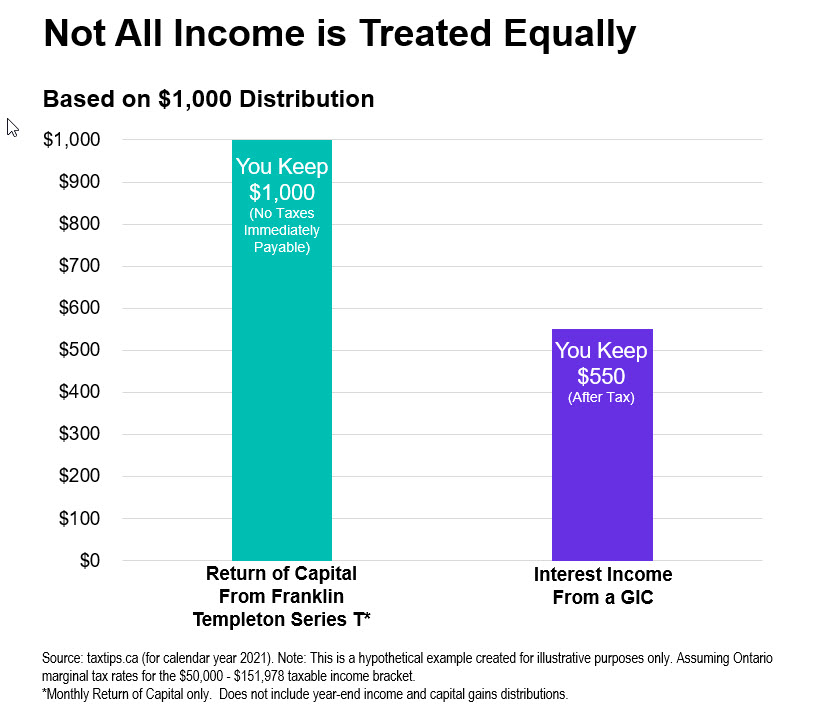
It’s important to stress that with Series T, capital gains taxes are deferred, not eliminated. Continue Reading…
Why a focus on ‘leaders’ works in Call Option ETFs

By Paul MacDonald, CFA

(Sponsor Content)

Harvest ETFs Chief Investment Officer explains why the independent ETF firm focuses on 20-30 ‘leaders’ in its call option ETFs.

Harvest’s call options ETFs are built through a structured process. Portfolio managers begin by identifying an industry, sector or theme with long-term growth prospects such as healthcare, technology, or utilities. They then identify and select between 20 and 30 leaders: large-cap companies with significant financial reserves and market share. The portfolio managers then apply Harvest ETFs’ active & flexible call option strategy to the ETF holdings to generate consistent monthly income for unitholders.

But why do they only select between 20 and 30 companies for their call option ETFs? Diversity is a key to any investment strategy, so shouldn’t Harvest ETFs focus on the widest variety of holdings as possible?

In our experience, the focused approach taken in many Harvest ETFs is tied directly to the execution of Harvest’s active and flexible Covered Call Option strategy.

20-30 stocks is not a random number. When we select the stocks we want an ETF to hold, our goal is to create concentrated portfolios, but with large enough capitalization and a wide enough diversity of business styles and operations that we can give investors broadly diversified exposure to a single sector or industry.

We like diversity, and in a one-stop solution for market exposure, having a huge array of companies can make a lot of sense. But for a targeted strategy like a call option ETF, focusing on the leaders of a particular industry or sector means the managers making decisions have a deep familiarity with the companies they hold.

Why familiarity matters in Call Option ETFs?

Call Option trading in an actively managed ETF requires constant engagement with options premiums available on specific stocks. One of the key value adds of an active call option strategy is the flexibility portfolio managers can have, both to generate their consistent monthly distribution and capture higher options premiums when available to expose more of the portfolio to potential market upside.

Continue Reading…

The seven money myths that stand in the way of a good financial plan

Financial Literacy Month is natural moment for a reality check-up

By Jennifer Cook, EPD, PFA, PFA™, QAFP™

For the Financial Independence Hub

On the path to financial security, there are natural peaks and valleys that can be navigated via the help of a good advisor.  It’s the map in the form of a personal plan that can help guide an individual toward their goals, whether it is saving for a house, planning for retirement or protecting against unforeseen events.  But more than any other hazard along the journey, is when road signs are misread or misunderstood.

Financial literacy is key to unlocking an individual’s ability to realize their dreams, and that is why Financial Literacy Month in November is so important to us at Co-operators.  It’s a moment for all of us to fill in some of the gaps in our knowledge about planning.

Many of us have developed habits or rely on inherited ideas about finances, so I look at financial literacy as an opportunity to put to rest some of the myths that can affect good financial planning.

As Canadians face year-end decisions on investments, taxes, and RRSPs, we at Co-operators have identified common gaps in financial preparedness stemming from the spread of money myths. There are many myths that can derail planning, but I’d like to talk about the top seven and offer a remedy in the form of a reality.

Myth 1: Saving is safe. Investing is risky.

Reality: As Canadians feel the impact of raising interest rates and inflation, it’s tempting to embrace the idea of “safe” or “lower-risk” investment options. But this strategy comes with a risk of considerable lost earning power. Investing in a diversified portfolio that matches individual needs with the help of a Financial Advisor can build long-term returns, while managing risk.

Myth 2: Single, young people don’t need insurance.

Reality: No one is free from the risk of loss or liability. When budgets are tight, tenant or renters’ insurance can provide critical coverage for unforeseen events like theft, fire, or water damage. Young people can also take advantage of lower insurance rates that provide continuing benefits as their lives develop and their needs grow.

Myth 3: RRSP season starts in mid-February.

Reality: Though the typical RRSP frenzy may suggest otherwise, there is no rule that says lump sum payments must be made to RRSPs before the annual March 1 deadline. Canadians can contribute to their RRSPs (up to individual contribution maximums) at any time of the year. The March 1 date is used to determine how tax benefits will apply to the previous year’s income. Depending on a person’s situation, a Financial Advisor may recommend contributing smaller amounts to an RRSP on a weekly, bi-weekly, or monthly basis.

Myth 4: Those who invest in mutual funds have sufficiently diversified portfolios.

Reality: Today’s spectrum of mutual funds is widespread. It’s not easy to gauge whether an individual investor is appropriately diversified. And that can leave some people vulnerable to losses from sectors. Leveraging the expertise of a Financial Advisor can help investors make nuanced adjustments to ensure their portfolio has the right balance of diversification aligned with their risk tolerance. Continue Reading…

Retirement Reflections during our 32nd year of Financial Independence

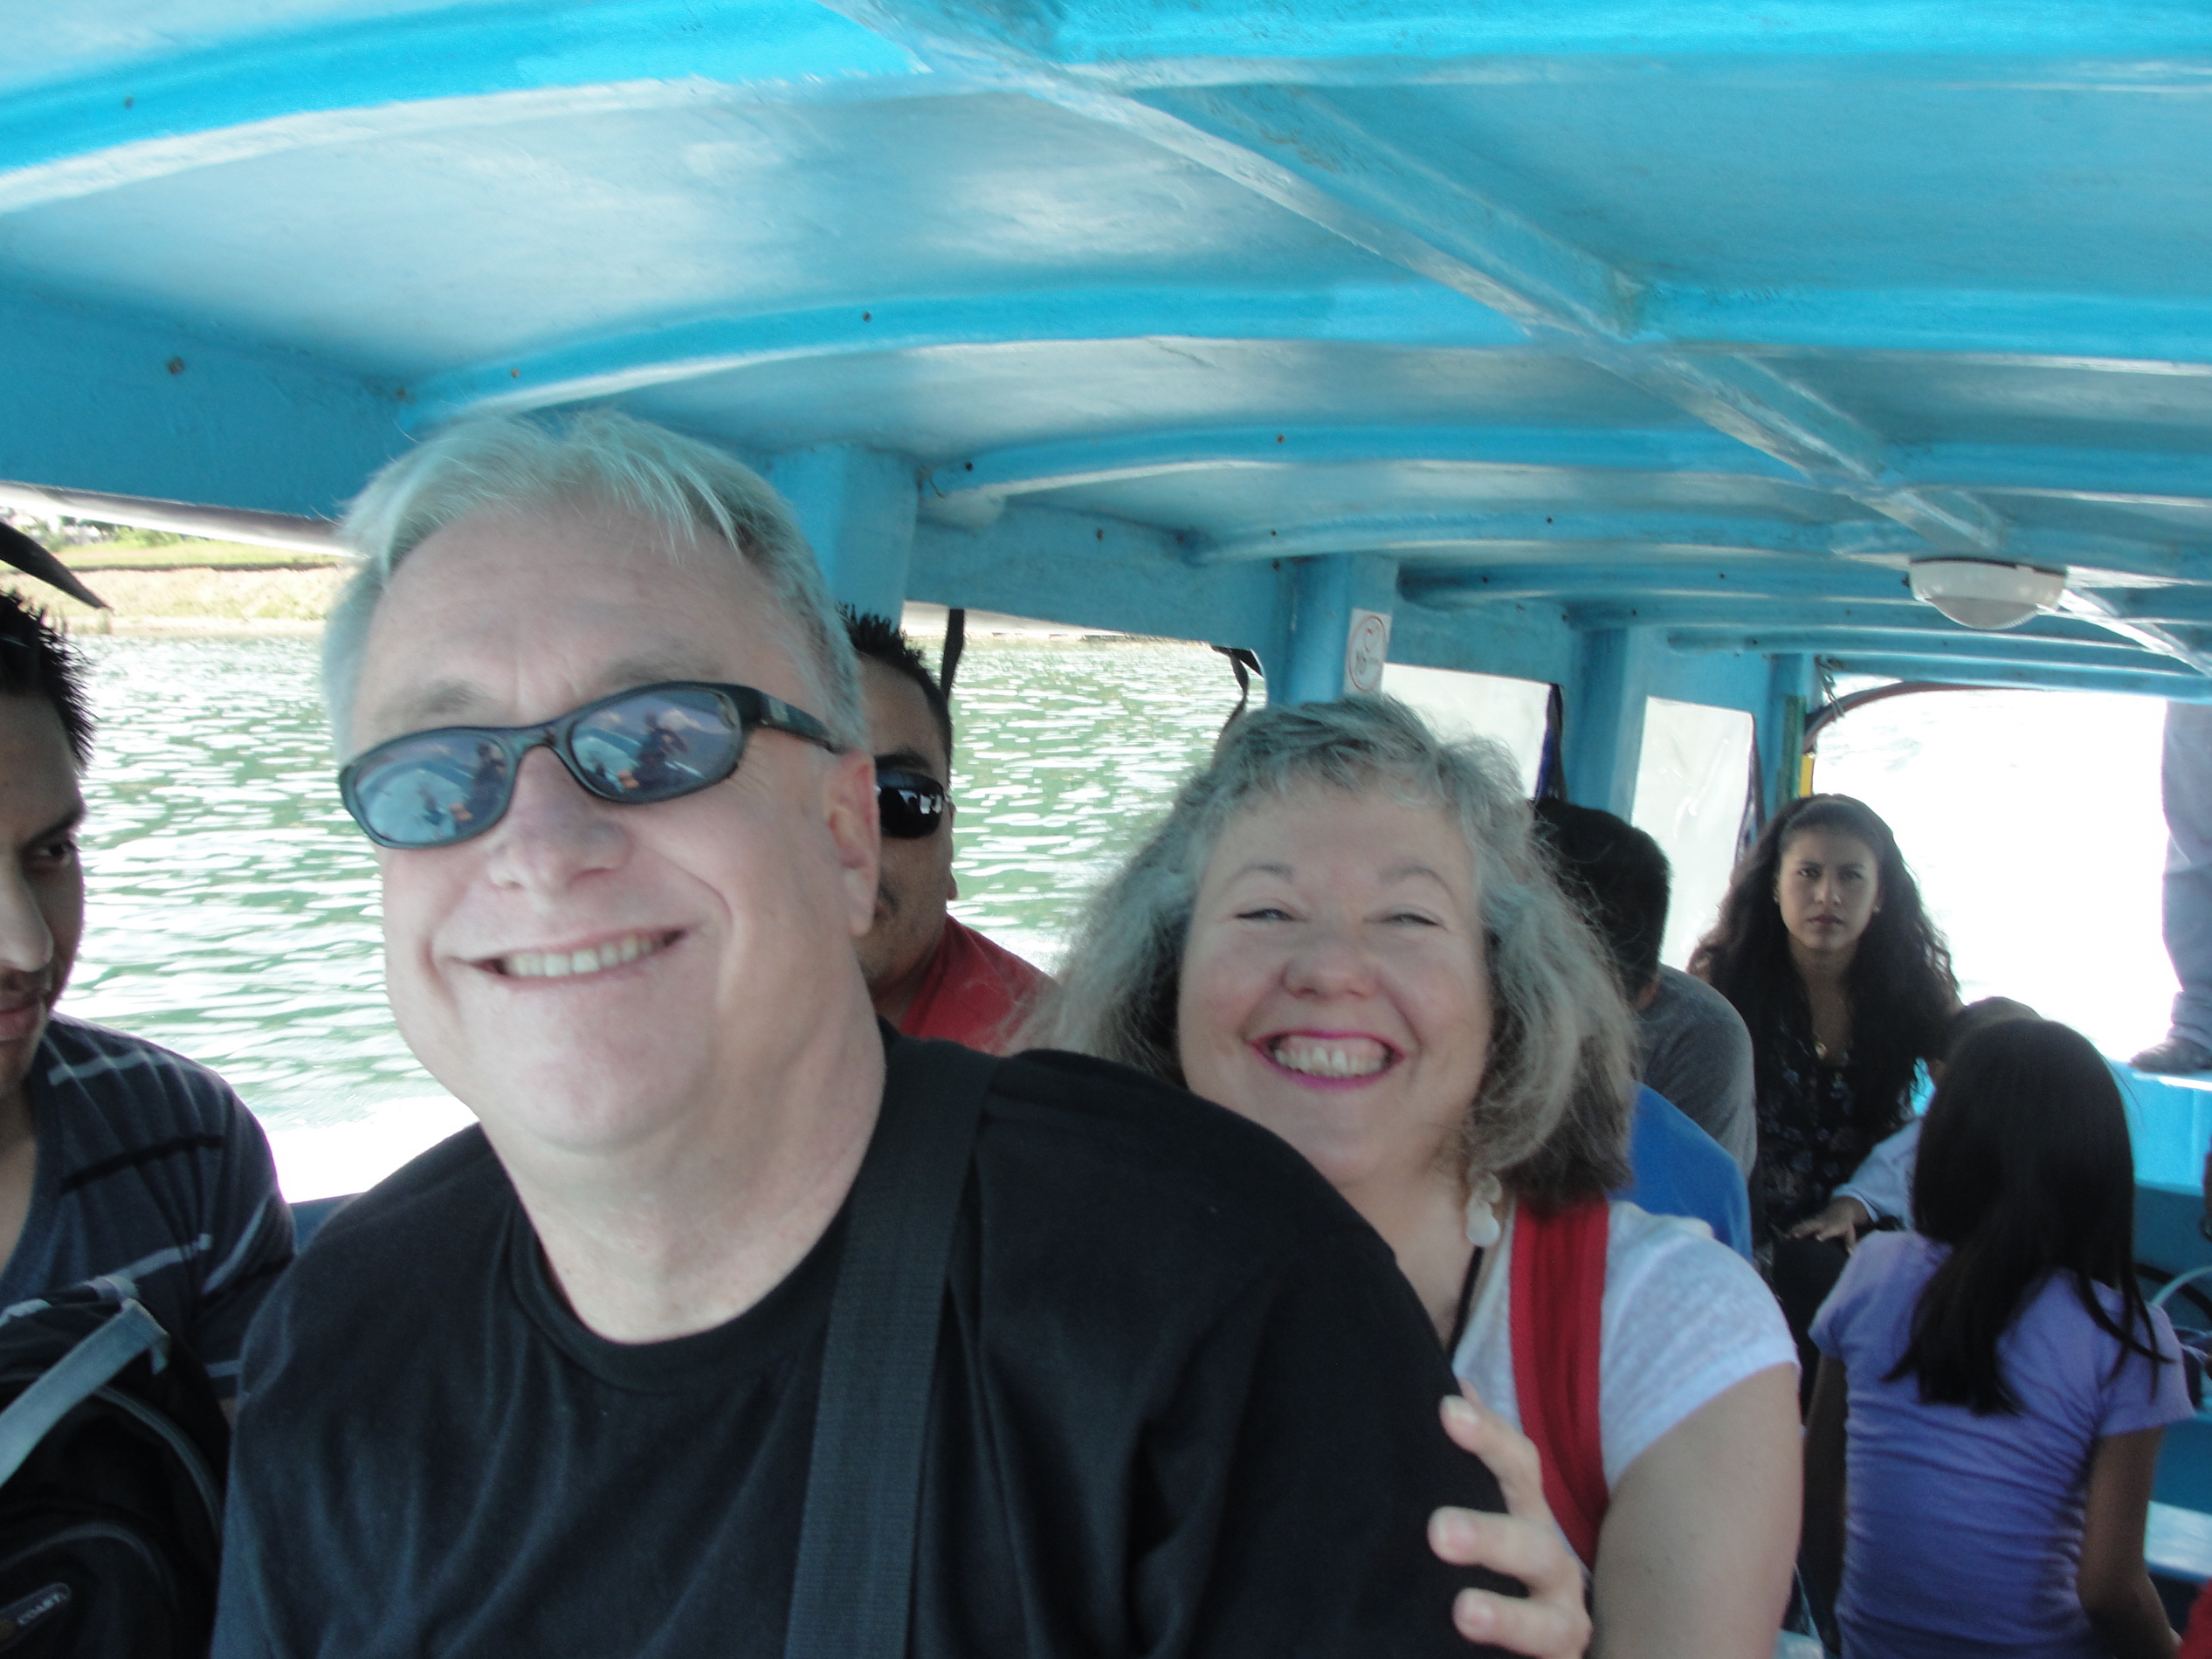
Billy and Akaisha Kaderli on Lake Atitlan, Guatemala

By Billy and Akaisha Kaderli, Retireearlylifestyle.com

Special to the Financial Independence Hub

In January, 2022 we began our 32nd year of Financial Independence. Few people can say they have 30 years of self-funded retirement by the age of 68 and have a higher net worth after spending and inflation than when they started. This is something of which we are quite proud.

As we have aged, one thing we have learned is that long term is getting shorter every day. Life is to be enjoyed now, not someday:  the older we get the more we appreciate that view. Life is continuously full of opportunities and we want to take them.

Opportunities abound

For example, a couple of years ago we were approached by a startup company which sponsored us for several months in Saigon, Vietnam in exchange for sharing our past experience in the restaurant and service industry and for exposure to our readers through our popular website and blog. That was a fabulous trip, and it got us back over to Asia again.

Then we were approached for a partnership, offering tours to Europe and South America. Can you imagine? There are always opportunities!

These are just two examples of why we say that life is full of chances to grow and learn something new if you want to take them. And neither of these recent options could have been presented to us if we were still working.

Portfolio getting stronger

Since the 2008 financial meltdown the markets certainly have performed well, thereby increasing our portfolio. And for a longer term view the S&P 500 closed at 312.49 when we retired in 1991, producing a better than 8% annual ride plus dividends. So, our advice is to get invested now and in a couple of decades looking back you will have wished you had invested more. Probably a lot more.

We suggest people track their spending now, then multiply that number by 25 to get a rough estimate of the portfolio amount they need to retire. Once you know that amount, in simple terms, assuming the same 8% growth in the future and you withdraw 4% for living expenses, this leaves you 4% to cover inflation and growth so you are all set.

The 4% rule is a guide not set in stone and ours bounces around depending on the markets and our expenses, but on average we have been able to maintain it easily below 4%. Our data over 30 years gives us security knowing that if one year it is higher we can make adjustments the following year to correct it. Then again, the markets could move higher helping us out as well, which is usually the case. Plus, we now are receiving Social Security, so payments and dividends cover our expenses. You can read our reasoning behind this decision here.

Practical considerations

Another note is that because we have a good percentage of assets in retirement accounts, when we turned 56 years old we used IRS rule 72T to withdrawal an annual amount close to our estimated Social Security payments, thus creating a bridge until we actually qualified. Now that we are receiving benefits we have turned off that spigot and are letting the IRAs grow once again.

The age of 72 is now coming into our sight and RMD, required minimum distributions, are the next issue to deal with, but we still have time and no one knows what the tax laws will be then.

With that stated, we still maintain a core holding of buy and hold (DVY, SPY, VTI) which sends us a steady stream of dividends in our taxable accounts as well as tracking the market. But in our IRAs, where we have no tax issues regarding trading, we have been more active using market seasonality with the idea of side-stepping larger declines. Some years have been better than others but we have been taking about half of the market risk than being all in all the time and that is comforting.

Where to retire, cost of living and healthcare

We are not alone anymore, with Boomers retiring at 10,000 a day, we see more retirees everywhere! But in terms of the foreign locations that we visit, the retirement community of Chapala, Mexico is growing at a fast pace. The Colonial town of Antigua, Guatemala has also attracted its share of Expats, and there is a solid and active retirement community in Chiang Mai, Thailand and Panama.

We would recommend Mexico, Panama and Guatemala for their proximity to the US and Canada as well as being on similar time zones as family and financial markets in the States. We would say that Thailand is attractive for its excellent medical care, warmer weather and uniqueness. All of these locations offer excellent lifestyle for cost of living. Continue Reading…

Retirement Options for Small Business Owners

By John Shrewsbury, RICP

Special to Financial Independence Hub

As a small business owner who is emotionally, physically, mentally, and financially engaged in a growing startup, you may feel consumed in the now. So many small business owners put everything back into their company without setting aside their profits in a tax-efficient way. If you run your business without an eye to the future, you will never reach the point where work becomes optional. Your business is your vehicle to financial independence, but it won’t happen without years of careful preparation.  

The independence and freedom of your entrepreneurial path comes with an array of responsibilities. As the business owner, the weight of preparing for your retirement and the retirement of your employees falls entirely on your shoulders. After all, if you don’t plan for your retirement, who will? Start building retirement savings into your company budget and making it a part of your compensation for running the company.

Business owners in the U.S. have retirement options for many situations

As a small business owner, you have a retirement option for almost every situation. When choosing a plan, your most significant consideration is the cost of contributing. If you can only afford to set aside a small amount of money each year, an individual retirement account (IRA) will serve you well. 

A Simplified Employee Pension plan (SEP) is the equivalent of a jumbo IRA. This plan works best for self-employed entrepreneurs with few or no employees. You can contribute up to 25% of your compensation to a SEP, with a maximum of $61,000 per year allowable in 2022. Keep in mind that if you have eligible employees, an SEP requires you to contribute an equal percentage of their salaries to the percentage you contribute from your own revenue. For example, a business owner with an employee making $100,000 per year would have to contribute 25% of the employee’s salary if they want to maximize their own contribution at 25%. If you have a number of employees, a SEP will most likely be your most expensive option.  Continue Reading…