Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Housing Bubble? Why it’s Crazy to buy in Vancouver or Toronto

Beautiful view of Vancouver, British Columbia, Canada
Vancouver, B.C.

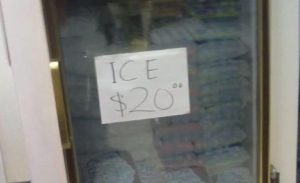
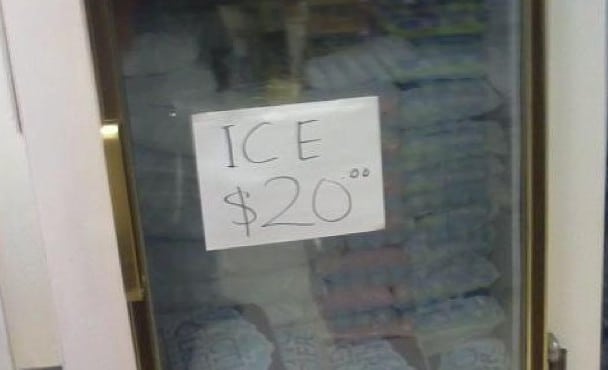
When central and southern Alberta experienced catastrophic flooding in June 2013 there were 32 states of emergency declared and over 100,000 people displaced throughout the region. Reports of price gouging at various retailers surfaced on social media; one story in particular claimed that an unscrupulous Calgary retailer was selling individual bags of ice for $20.

Given the urgency of the situation, and depending on your level of preparedness, what options do you have?

  1. Move on to the next retailer and hope to find an honest owner
  2. Go home with no ice and wait for the situation to return to normalCalgary-price-gouging
  3. Suck it up and buy the ice, grumbling the entire way home about how you got ripped off
  4. Hope for some kind of government intervention to protect you and other consumers from price gouging
  5. Borrow ice from a friend or neighbour who has plenty to spare
Continue Reading…

Millennial Wrap: Wedding Bell Blues, good debt and other illusions

a04a25d7-0da5-4af5-96b7-1e10d3b96580By Helen Chevreau, Hub Staff

Wedding Bell Blues

After reading this new post from Broke Millennial, I feel lucky to have been spared the first few years of the “wedding apocalypse.” At 24, I have yet to have any of my close friends or relatives tie the knot, and now I know that in addition to being thankful for this budgetary hall-pass, I should really be taking this extra time to start saving for “other peoples’ weddings.”  I know I’ve got at least another few years before I will need to start paddling the wedding wave, but knowing it’s something I will eventually need to factor in is important.

Millennial Illusions

The pressure to have our lives together has, I would assume, always been a very real and stressful issue for millennials. Since the onslaught of social media “dream lives” we see on sites like Pinterest, Etsy, Apartment Therapy etc., it’s extremely easy to fall into a pit of expectations that no normal 20-something should be expected to live up to. This is a huge issue I’ve found with becoming a grownup. We see snippets of peoples’ lives and we want our lives to look just like that, but we forget what it’s taken for them to get there. Continue Reading…

The 2-letter 4-letter Word

Gignac - Headshot - 2013By Robert M. Gignac

Special to the Financial Independence Hub

One of the things I love about my job is that I get to have interesting and passionate conversations with North Americans regarding money, personal finance and fiscal responsibility. We all have a relationship with money – sometimes it is a good relationship – sometimes not.

I spoke at an event in Victoria, B.C. recently and during the Q&A portion a guest asked the following question: “What is the one biggest thing I can do to improve my financial situation?”

Now, I’m a firm believer that there is no single thing we do that makes us financially successful – it’s the repetition of a variety of little things, done over and over and over that make us successful. I could tell from the way the question was phrased and the rather emphatic index finger in the air as they asked the question – they were looking for “one thing.”

Looking for one big answer

While the silence seemed to hang in the air, an audience of 250+ waited for the answer. I took a sip of water from the glass on the table and hoped they were going to be happy with what I had to say: “There is no one “biggest” thing you can do – but – if you’ll humor me for moment – I’ll share with you what I think the one biggest word is? How’s that?” Continue Reading…

Millennial Blog Wrap: Cheap vs Frugal and Chronic Money Stress

Beautiful young woman listening to music and having takeaway coffee outdoorsby Helen Chevreau, Hub Staff

This short and to-the-point post from Budget Bloggess is here to quell all our concerns about the millennial generation being frugal. Sure, the word ‘frugal’ may get some flack for its apparent likeness to ‘cheap’, but oh how different the two really are. If you were ever unsure as to whether cutting up your old t-shirts to use as dishrags qualified you as cheap, you can stop worrying. Thanks to Toronto-based Budget Bloggess for putting my mind at ease:  I’m not cheap, I’m frugal.

Have Your Latte

 We’ve probably all been told at this point in our financial journeys about the magical ‘latte factor.’ You know the one:  if we just save the $5 a day we would normally spend on our Starbucks, we’ll be rich before we know it. Of course there’s nothing wrong with this tactic. However, this new post from My Money Counts will definitely help us put that $5 in perspective when compared with the “4 expenses that will steal your savings.” Those being expensive car payments, having too much house, insane student loan debt, and of course, credit-card debt. It is a well-informed look at some of the most common and burdensome factors that contribute to young peoples’ savings struggles. And, if nothing else, it’ll make you feel a little less guilty about that double mocha frappucino!

 Chronic Money Stresses?  Continue Reading…

How realistic is it to live only on cash?

Repak-Headshot
Steve Repak

By Steve Repak, CFP

Special to the Financial Independence Hub

If you are in debt, you have probably heard over and over again that you should quit using credit cards and stick to using cash exclusively for purchases (aka “cash-only” purchases.)

In a previous article I explained that for some people it actually hurts to break a large bill like a $20, so only using cash may help you get your spending under control. I wanted to share some of the risks and benefits of a cash-only lifestyle and also show that you can still get out of debt if you want to use credit cards.

If getting out of debt is your goal, there are three things you must do in order to succeed regardless of whether you use cash or credit:

  1. Spend less money than you take home each week
  2. Build an emergency savings
  3. Develop and follow a get-out-of-debt plan

Cons of using cash

Continue Reading…