Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Exploring the ExPat Lifestyle in Mexico’s San Miguel de Allende

FullSizeRender(1)
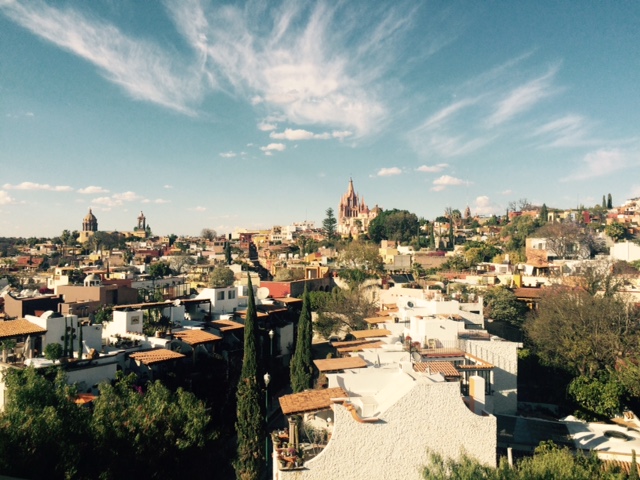
View of San Miguel from top of the Rosewood Hotel (Photo J. Chevreau)

Last week, my wife Ruth and I enjoyed a week’s vacation in San Miguel de Allende, which is located in central (and landlocked) Mexico. We’d been to Mexico several times over the years but never this particular community, which is not handy to a major airport.

It was also our first trip to Latin America in about five years, since we had been taking our February breaks in Florida in more recent years.

Ironically, San Miguel was prominently featured in the old magazine I published around the year 2000: The Wealthy Boomer. At the time, I remember being impressed by the fact the cost of living for semi-retired American and Canadian baby boomers was roughly half what it was in our home countries. This theme was also applied to various Asia locations in a Hub blog last year featuring the book Planet Boomer. See also my post, titled 5 Asian locations where retirement is more affordable than North America.

Trading high taxes for crime?

Back during the days of the tax-and-spend Jean Chretien Liberals, I found the Mexican expatriate fantasy quite compelling, so much so that I listened to Spanish instructional tapes on my long commutes to the National Post’s bunker then located in Don Mills. But the fantasy of becoming a tax exile/early retiree faded once the Conservative Party achieved power and seemed to offer at least the hope of more reasonable levels of taxation (the Tax-free Savings Account being a major positive example.)

Meanwhile, the unremitting press over drug-cartel-related crime in Mexico reached a crescendo in the last few years so we stopped visiting for a spell.  Continue Reading…

The Real Cost Of Personal Debt

MarieEngen
Marie Engen, Boomer & Echo

By Marie Engen, Boomer & Echo

Special to the Financial Independence Hub

We are constantly reminded about the rising level of outstanding personal debt carried by Canadians. Every few months we hear about the perils of rising interest rates that may leave many in financial difficulty.

The reality is – debt is not all bad. Most of us wouldn’t have been able to purchase our homes without a mortgage, or buy a car, or pursue secondary education. Even credit cards are not evil in and of themselves no matter how they are often portrayed.

To never (ever) borrow money is to live in the land of the already rich, or to always be a renter. At the other extreme, using other people’s money to fully finance your lifestyle is ridiculous and precarious.

Most of us don’t fall into these extreme circumstances. We hold a reasonable amount of debt, make our payments on time and have good, to very good, credit ratings. That being said, most people fail to optimize their overall debt management strategies to pay the least amount of interest.

Consolidating debts

We no longer hear about the “all-in-one” mortgages offered by financial institutions such as the Manulife ONE and National Bank All-in-One. These accounts combine chequing, savings, and borrowing into one account. If used properly, consumers could simplify their debt and lower their overall interest paid.

These won’t work for most people because they like to keep all their accounts separate. They have multiple liabilities at different interest rates:

  • Home mortgage
  • Car loan
  • Line of Credit
  • Student loan
  • Credit card to use for discounts at your favourite store
  • Credit card for other rewards.

When I worked in banking, I gave out many consolidation loans. I confiscated and cut up credit cards, cancelled overdraft protection, and closed out other loans and lines of credit. Invariably, within a couple of months, more than half of these clients would reapply for their credit cards, reinstate ODP, and sneak off to a different branch to get another line of credit.

More personal debt mismanagement

Here are some other ways people don’t think clearly about managing their personal debt.

  • Mike and Molly are determined to pay off their mortgage (2.7%) in less than 10 years. They put every available dollar towards the principal. They also have two car loans at 4.5% and 8% and purchased a “don’t-pay-for-six-months” entertainment system. It makes more sense to address these debts first.
  • When their mortgage came up for renewal, Fred and Ethel rolled the balance into a new Home Equity Line of Credit. However, they continue to finance their lavish life style with their credit cards. They pay off the cards each month from the HELOC on which they make the required minimum payment of accrued interest. After all, they have a huge balance still available to them. They think they are managing their debt well by paying off “bad” credit card debt and having “good” mortgage debt.
  • Jess went to her favourite home décor store to purchase some sheets. There was a store promotion that gave 20% off purchases when opening a new store credit card. Excited by the discount, Jess picked out a whole bedding set from duvet to accent cushions. The balance is too high to pay when the bill arrives so she makes minimum monthly payments while incurring interest charges of 29.9%. Meanwhile, she has enough money in her low-interest savings account to pay the entire bill, but chooses not to.
  • Leonard works on commission and his paycheque amounts vary. He makes up the difference in lean months with his overdraft protection at 24%. Until he learns how to budget for his irregular income, he should use his credit card for purchases, even if he carries a balance for a month or two.
  • Ross receives a credit card offer with a “teaser” 0% interest on balance transfers. He transfers the balance from his high interest rate card and cancels it. He uses his new card for future purchases, not realizing that the 0% only applies to the amount of the transfer. His payments go to the new purchases he made which carry a much higher rate. He would have been better off to continue using his old card for his occasional new purchases, pay the monthly balance in full, and avoid using the new card at all.
  • Barney and Betty have a systematic plan to pay off all their debt. They are using the “snowball” method popularized by author Dave Ramsey, which states that it is psychologically satisfying to first rid yourself of the smallest debts first, regardless of interest rates. The reasoning is they would be better prepared – and more enthusiastic – to stick with the strategy. But, once the small debts were done they took their foot off the gas and paid random amounts on the higher debts whenever the inclination hit them.  

Final thoughts

Instead of speculating about the direction of future interest rates, we should be examining our own habits.

Take a look at how you think about – and manage – your personal debt and see if you can minimize your borrowing costs.

Also read:

Marie Engen is the “Boomer” half of Boomer & Echo. In addition to being co-author of the website, Marie is a fee-only financial planner based in Kelowna, B.C. This article originally ran at the Boomer & Echo site on Feb. 9, 2016 and is republished here with permission.


Renewing your Mortgage this year?

By Robb Engen, Boomer & Echo

Special to the Financial Independence Hub

Our mortgage is up for renewal later this year. That’s a shame because I’m enjoying the ultra-low 1.90 per cent interest rate on our five-year variable mortgage (prime minus 0.80 pe rcent). It’s a near certainty that I’ll have to renew at a higher rate this summer.

My bank is offering five-year variable rates at prime minus 0.10 per cent, which means a mortgage rate of 2.60 per cent. That’s not much of a discount off of the five-year fixed rate they’re advertising, which comes in at 2.94 per cent.

Five years ago, when the deeply discounted variable rate was 1.50 per cent lower than the five-year fixed, it was a no-brainer to go variable. Now it’s not so cut-and-dried.

What is clear is that we’re living in the golden age of low mortgage rates. Remember three years ago when BMO introduced its controversial 2.99 per cent ‘no frills’ mortgage?

Now it’s rare to see mortgage rates ABOVE 3 per cent – and most come with all the bells and whistles; from 120-day rate holds and pre-approval, to double-up monthly payments and lump sum payment privileges.

For nearly a decade we heard how interest rates couldn’t possibly get any lower and that the smart thing for homeowners to do was lock in their mortgage with a five or even a 10-year fixed rate.

It turns out the best advice was to do what has almost always saved Canadians the most money over the last 50 or 60 years. Go variable.

Renewing your mortgage

Continue Reading…

Our values about money are changing and millennials are leading the evolution

headshot_sm
Jay Acharya

By Jay Acharya,  Capital One Canada

Special to the Financial Independence Hub

When my wife and I bought our house, it felt like a massive achievement for us as we had diligently saved our money for the down payment.  When we told people about it, they were full of questions about the neighbourhood, the kitchen and how many bedrooms there were.

We were so proud of ourselves for accomplishing this milestone that we eagerly shared pictures and every detail about our new home.  The funny thing is, no one asks you to tell them the story about how you saved up to buy the house in the first place.  That is where the real drama and the value of the conversation is – then again, you can’t take pictures of the restaurant meal you skipped or the stay-at-home vacation you took and post them on social media.

New car, new house, new clothes – the idea that owning bigger, more expensive things has traditionally been valued by our society as a symbol of status and accomplishment.  Now enter the millennials: the demographic that is challenging the status quo in many areas, including what we value.

Capital One Canada recently hosted the C1NDX, a consumer index roundtable and study that included six of Canada’s leading journalists and industry experts. With a specific focus on the impact of the sharing economy, we dove deep into how the financial values and spending habits of consumers have changed and are continuing to evolve.

We discovered that when it comes to how and why consumers spend their money, the values of many Canadians, particularly millennials, are shifting.

Experiences Are the New Luxury

Continue Reading…

Q&A with North America’s first subscription-based Robo Adviser service

Randy_Photo
Randy Cass, NestWealth.com

Jon Chevreau: Most robo advisers in North America seem to use a model of charging a fee based on assets. As one of Canada’s original robo-adviser services, NestWealth.com uses a quite different model, based on subscriptions, correct? One, I might add, that you say is also unique in all of North America?

Randy Cass: Nest Wealth’s members pay a flat monthly price for access to a customized portfolio and a dedicated portfolio manager. Our subscription model doesn’t incentivize or commission sales people based on how much of a product they sell. We’re enabling Canadians to sidestep high fees and outdated banking practices that take a percentage of everything they invest throughout their lives.

Nest Wealth’s subscriber community understands that our subscription service fundamentally challenges the model banks, and even newer robo-advisors, have used to charge investors. Not only are we able to deliver a proven investment service capable of saving Canadians up to half of their potential wealth, but we’re continuously improving that service by listening and adapting to our members’ needs. This is a transformational advantage of the subscription model, and it’s one important reason why we see so many industries adopting it as a revenue model.

JC: Is this unique, both in Canada and the US and rest of world?

RC: Nest Wealth is the first and only subscription-based investing service that handles everything from end to end. Investors of all ages can subscribe to our service for $20 a month — less than the cost of a gym membership. And their subscription is capped at $80 no matter how much their assets grow overtime. We want to help Canadians do the math and recognize that our low, flat subscription payment can leave them with 100 per cent more savings than a traditional fee structure that charges based on assets.

The good news is we’re witnessing a clear shift in how Canadians want to pay for and access financial services. A new report by business consultancy EY says that the adoption of fintech services among Canadians will triple over the next 12 months. The report also shows that although consumers trust technology, they still lack awareness of its benefits. We are passionately committed to helping consumers understand and seek out a better way to build wealth. Broader awareness and education will lead to more informed choices about how families plan for their future. There’s quite a bit at stake here.

JC: Where did you get the idea in the first place?

RC: The ‘Aha’ moment came when I was watching Netflix with my youngest son and I recognized that the principles of subscription services like Netflix, Spotify, Salesforce and Zipcar were much more in line with how investors needed to be treated than the status quo.

Continue Reading…