Debt & Frugality

As Didi says in the novel (Findependence Day), “There’s no point climbing the Tower of Wealth when you’re still mired in the basement of debt.” If you owe credit-card debt still charging an usurous 20% per annum, forget about building wealth: focus on eliminating that debt. And once done, focus on paying off your mortgage. As Theo says in the novel, “The foundation of financial independence is a paid-for house.”

Do Americans want Free Health Care or complete Student Loan Forgiveness?

A LendEDU study shows more Americans want free health care than student loan forgiveness. Free health care is a big plank for Democratic presidential candidate Bernie Sanders.

By Mike Brown

Special to the Financial Independence Hub

In Canada, the debate over health care isn’t nearly as fiery as the one that is going on within the confines of its southern neighbor, the United States. 

That is because Canadian citizens and permanent residents already have access to public health insurance that alleviates them from paying for health care services most of the time. 

But in the U.S., the debate rages on, especially with 2020 being a presidential election year. 

This election cycle is no different than any other one in recent memory because health care is once again a core issue amongst the candidates and constituents. Plans from both sides of the aisle range from maintaining the status quo to free universal health care. 

What is different about this year’s presidential election is the much greater emphasis that is being placed on the student loan debt crisis and the growing cost of higher education. 

Whereas before these joint-issues would have rarely been discussed at debates and rallies, they are now amongst the most discussed topics. 

And it’s easy to understand why; in the U.S., the total outstanding student loan debt figure is now roughly $1.61 trillion, which makes it the second largest class of consumer debt in the country behind mortgage debt. There are 44.5 million student loan borrowers and recent ones owe $28,565 in student loan debt. 

Student loan debt has gotten so out of hand in the U.S. in large part due to the ever-inflating cost of college tuition, which has outpaced the inflation rate by at least three times. Whereas the average cost of college in Canada for a Canadian citizen costs around $5,000 per year, it costs between $20,000 and $50,000 per year for an American attending college in the U.S. 

So, both health care and student loan debt plus the cost of higher education will be issues that weigh heavily on the minds of American voters in the 2020 presidential election. 

With this in mind, LendEDU, a personal finance company, conducted a survey of 1,000 Americans of voting age to gauge their preferences on the two topics. 

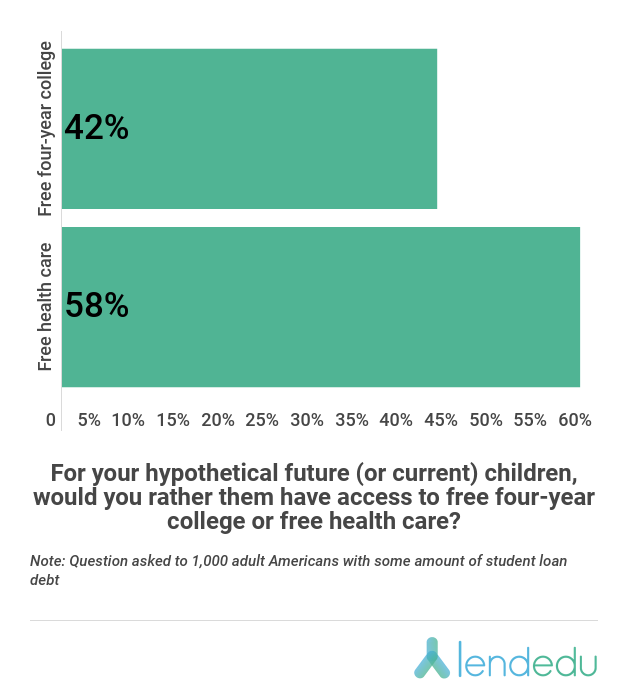
60% of Americans prefer free Universal Health Care to complete Student Loan Debt Forgiveness

LendEDU’s survey first asked respondents the following: “Would you rather have the United States’ $1.61 trillion in outstanding student loan debt be completely forgiven or have a free health care for all policy be implemented in the U.S.?”
reembargolifted(1)


While 40% of poll participants opted for complete student loan forgiveness, the majority (60%) still wanted free universal health care instead.

In terms of cost, forgiving the nation’s student loan debt would cost somewhere around $1.61 trillion, while free universal health care would cost anywhere from $25 trillion to $36 trillion over 10 years. Further, while the average student loan debtor owes $28,565 in student loan debt, the average cost of health insurance was $18,764 for the average American family in 2017, with $5,714 of that coming from out of the pocket.  Continue Reading…
What are Liens and how do they work?

By Emily Roberts

Whenever you borrow a significant amount of money from a lender, they will do their due diligence beforehand. This means ensuring that you are able to repay the money that you borrow on time and in full. A lien is a tool that lenders can use to secure their loans and lend money more confidently. Here is a short guide that explains a bit more about what a lien is exactly.

What Does a Lien Entail?

When a lien is placed on a property, it gives someone – usually a lender – the legal right to the subject’s property. With a lien in place, creditors are able to take property from borrowers in order to cover the money that they are owed. Liens are nearly always the result of a default on a debt, although they can also be awarded as judgments following some legal proceedings.

For example, let’s say that you take out a loan in order to purchase a new home. Often when you take out a loan, you will be required to put up some form of collateral: assets that can be used to cover the money you owe if you are unable to keep up with your payments. For the most part, lenders don’t have a tremendous amount of leverage and are therefore eager to find some way of protecting their loan.

What exactly can you offer that would satisfy the bank’s anxieties? The answer is to allow them to become the lienholder on your property. This doesn’t mean that they automatically have any rights to your property, but it does mean that if you don’t keep up with your debt repayments, then they can come for your property as recompense.

Liens are a matter of public record: something else which is important to know for borrowers and lenders alike. For lenders, publicly available lien records can indicate that an individual has already granted someone else rights to a property. You can have multiple liens, but many creditors will be reluctant to lend to you if they know that they are at the back of the queue when it comes to repayment of debts.

You can search for lien records, among others, by using the following site: https://publicrecordsreviews.com/lien-records. [Site is in the US and aimed at Americans: editor] Public Records Reviews enables you to search through a variety of public records for information about specific individuals – you can even use the service to check for your own records. Note that the lien records on Public Records Reviews are attached to individuals rather than properties. In other words, you will have to search for the homeowner rather than the home itself.

When are Liens used?

Liens are most commonly associated with loans and money lending. We have already covered home loans, perhaps the most common arena for liens to be used for, but another important category is auto loans. Continue Reading…

A cure for the headaches of fixed income investing

By Ahmed Farooq, Franklin Templeton Canada

(Sponsor Content)

Many advisors I speak with continue to struggle with the increasing complexities of today’s fixed-income environment and are looking for guidance. The combination of interest rate fluctuations, inflation threats, trade tensions and political upheavals is a challenging environment to make the right call for their clients’ portfolios. There is a real concern that volatility is on the horizon and fixed-income mandates will be needed to provide that cushioning to the overall portfolio.

Active management may be the best way for advisors to navigate this market. For advisors who want an expert’s opinion when it comes to managing future interest rates, credit quality or duration calls in their fixed-income allocation, I like to remind them that this is something that may be best left to a manger who can effectively deal with these factors and risks.

The trend towards active continues

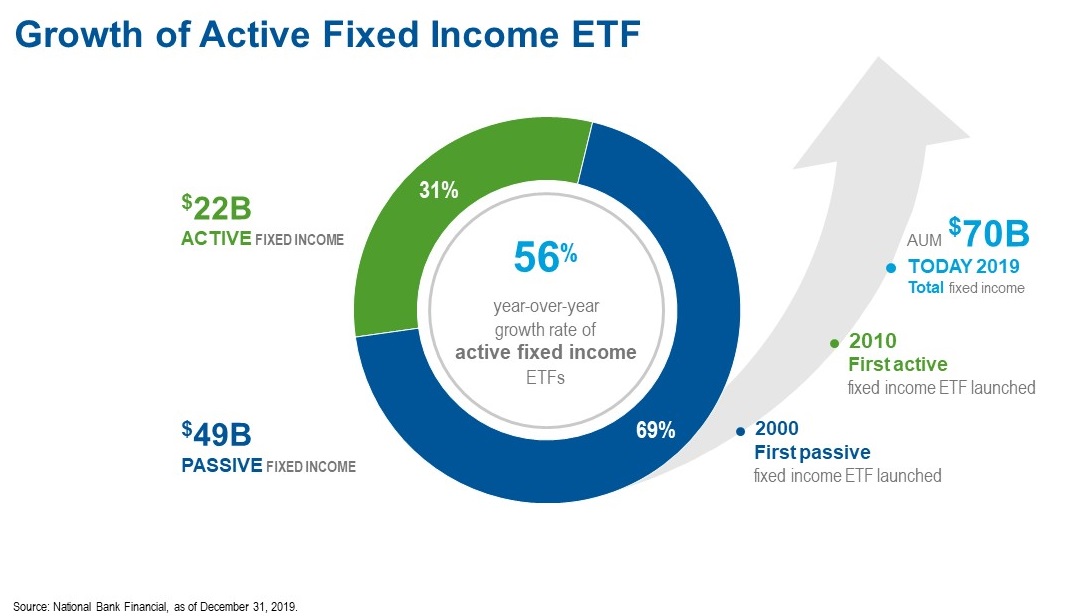
This trend of more advisors switching to actively managed fixed income solutions can be seen in monthly ETF inflow reports over this past year.  Within the world of fixed-income ETFs, actively managed products have seen the biggest area of growth. For example, National Bank of Canada’s January 2020 ETF Research & Strategy Report showed that at the end of January, the total AUM of fixed-income ETFs was $73.4 billion in Canada. Of that $22 billion was put into actively managed funds, which now amounts to nearly a third of all fixed-income ETFs.

Active strategies seek to achieve a specific investment outcome

The goal of passive indexing strategies is to minimize tracking error to the index, maintain index exposure by either fully replicating the index or though a stratified sampling approach; one thing a passive investment cannot do is adjust to any type of market events. This can certainly be a headache for most advisors as the onus on making any changes to their portfolio will be on them. Further, with the vast number of options available, this headache is something that cannot be easily solved. Active managers can adjust to different type of market events, changes to monetary policy and yield curve, adjustment from geopolitical events, and duration management. Outsourcing your fixed income exposure to align with your client’s outcomes will provide relief in this ever-tougher fixed income environment.

Improving client portfolios

As more advisors look at their options within the active fixed income space, I think they will be pleasantly surprised by the pricing of active fixed income funds. Continue Reading…

Make that last-minute RRSP contribution a conservative one

Every year around this time, people like me pound their fists on the proverbial table for ordinary Canadians to make an RRSP contribution.  Spoiler alert: that’s what’s going to happen here, too.

What’s different in this post is that I’m going to go a little bit further than others in making my plea … but only a little bit.  I’m not going to recommend a specific security or product. I am, however, going to recommend a specific asset class: income.

So many people tell me that the reason they don’t contribute is that they don’t know what to invest in.  I gently point out to them that deciding about how to invest your little tax-deduction generator is not a pre-condition of contributing.  Just put the money into your RRSP based on the room available on your most recent notice of Assessment before Monday March 2, already.  Generate a refund …. or at least a reduction in the amount owing.

Many people make RRSP contributions in the second half of February and contribute nothing else throughout the remainder of the year.  For them, this is an annual tradition where they make a one-time contribution into whatever catches their fancy and pay precious little attention for the next 52 weeks or so.

Most people should be investing in Bonds this year

If this sounds like you … and if you already have a somewhat balanced portfolio that has some combination of stocks and bonds in it, then I suspect that the stock portion of your portfolio did very well in 2019 and the bond portion did relatively less well.   That simple reality is why most people should be investing in bonds this year.

Let’s say you’re a traditional balanced investor with a target of 60% in stocks and 40% in bonds.  If you started out a year ago with that asset allocation and your stocks were up 20% while your bonds were up 3% over the past year, then you could re-balance using the contribution. Continue Reading…

How much would the Home Buyers’ Plan help in your market?


By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

For those trying to scrape together a down payment in Canada’s hottest housing markets, the Home Buyer’s Plan is known as an effective tool. Offered by the federal government, it allows first-time buyers to pull funds from the RRSPs completely tax-free to put toward their home down payment. If you’re lucky enough to have RRSP matching via your employer, or have been saving for retirement for some time, it can seem an especially attractive method to amass down payment funds.

However, there are a few restrictions buyers should be aware of:

  • Buyers must have a signed Agreement of Purchase and Sale to buy or build a property before applying to access the funds.
  • They can pull up to a limit of $35,000 from an individual’s RRSP, and up to a combined $70,000 from RRSPs held by two individuals buying together (assuming the funds are saved in the first place).
  • The funds must have been sheltered within the RRSP for a minimum of 90 days before they can be accessed.
  • Buyers are required to “pay themselves back”, contributing one fifteenth of the withdrawn amount on an annual basis over a 15-year timeline, or be taxed on that portion at their full rate.
  • Buyers must qualify as “first timers,” which the Government of Canada defines as not having owned a home, or occupied one that your spouse has owned, in the four consecutive years before this home purchase is made. (However, there are exceptions in the case of a marriage or common-law relationship breakdown where former partners can restore their first-time buyer status.)
  • Buyers must intend to dwell in the home as their permanent residence within one year of its purchase or completion.

How long would it take to actually save for the HBP?

Assuming a buyer satisfies all the criteria above, they also need to actually save the funds in the RRSP in order to use them for their home purchase: and that’s easier said than done in some urban centres than others.

To see how long it would take to actually set aside the maximum $35,000 in an RRSP, Zoocasa sourced individual income thresholds in 14 cities across the nation. The data was based on 2017 tax filings as reported by Statistics Canada, and assumed the income was earned income, eligible to create RRSP contribution room, and that individuals contributed the maximum to their RRSP annually (18% of earned income, to a maximum of $26,500). The study also compared how long it would take for those in the top 50%, 25%, and 10% income groups to save $35,000.
According to the findings, for a median-income household contributing the max amount to an RRSP, it would take between 4.3 – six years to pull together $35,000.

(See Infographic at the top of this blog).

How far would $35,000 go in your Housing market?

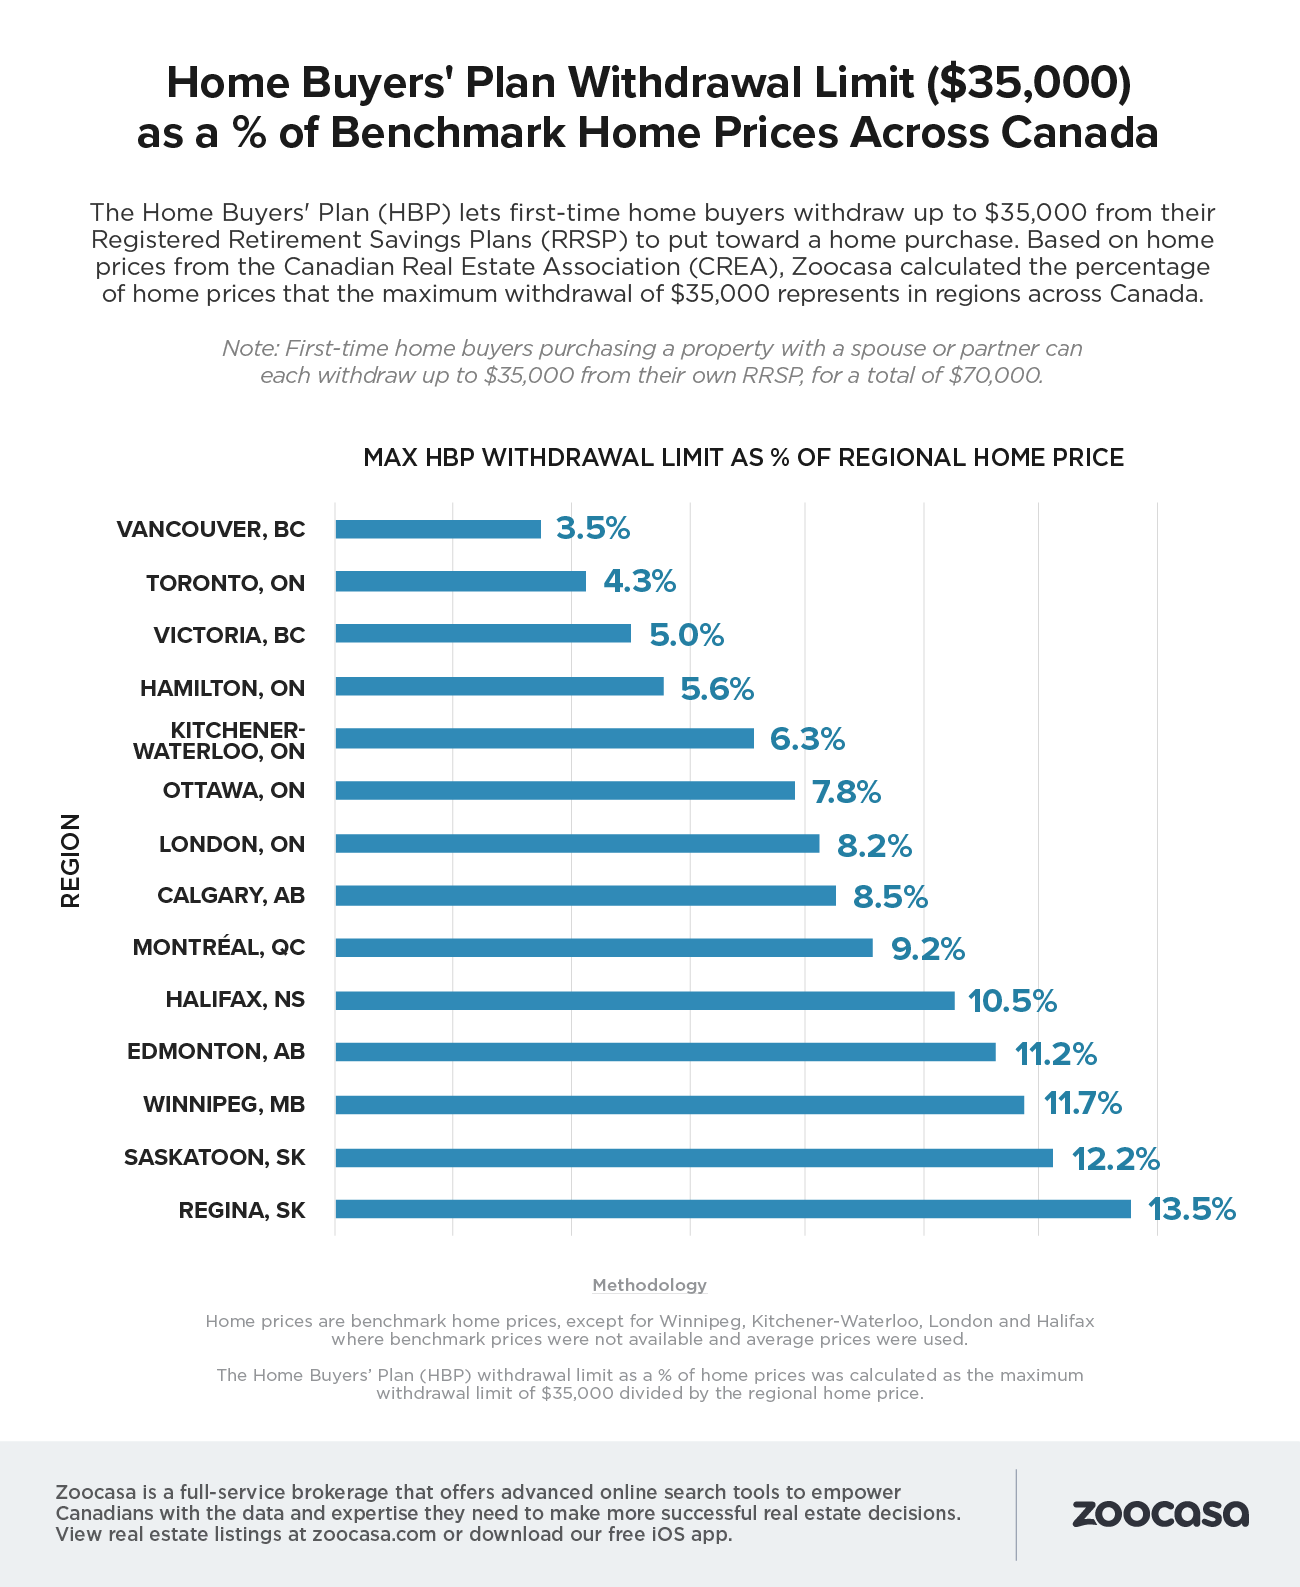
As well, the extent that the maximum HBP funds would actually aid in a home purchase varies across Canada; it’s no surprise that in the priciest markets, such as homes for sale in Toronto or Vancouver, that it’s hardly a drop in the bucket – just 4.3% and 3.5% of a benchmark home price, respectively. Continue Reading…