Decumulate & Downsize

Most of your investing life you and your adviser (if you have one) are focused on wealth accumulation. But, we tend to forget, eventually the whole idea of this long process of delayed gratification is to actually spend this money! That’s decumulation as opposed to wealth accumulation. This stage may also involve downsizing from larger homes to smaller ones or condos, moving to the country or otherwise simplifying your life and jettisoning possessions that may tie you down.

Rising or Falling Markets? Roll with it!

Image Outcome/Shutterstock


Luck’ll come and then slip away
You’ve gotta move, bring it back to stay
You just roll with it, baby

— Roll with It, by Steve Winwood


By Noah Solomon

Special to Financial Independence Hub

There is never any shortage of pundits opining on what could make markets rise or fall. Tragically, the greatest cheerleading has tended to occur when markets were at their riskiest and the loudest fearmongering has tended to occur when markets have harboured the greatest opportunity. However, this does not change the fact that anything can happen at any time:  markets have and always will continue to periodically present investors with dynamically evolving combinations of risk and reward.

To never suffer losses is an unrealistic objective for those who wish to receive a satisfactory return on their investments. Rather, it is far more efficient (and financially rewarding) to roll with it: which entails adapting to changes to (1) maximize gains when markets offer above-average returns with relatively low risk and (2) to minimize losses when markets offer below average returns with above average risk.

This month, I present a framework for investors to dynamically manage their portfolios to meaningfully participate in rising markets while limiting losses in bear markets.

The Sine Qua Non of Successful Investing

If 100% of your portfolio is sitting in cash, then it is impossible for you to lose money (at least in non-inflation-adjusted terms). However, if markets rise, you will miss the proverbial boat and suffer significant opportunity loss. At the other end of the spectrum, if your portfolio is 100% allocated to equities, while you won’t miss the party if markets advance, you will most certainly suffer substantial losses in the event of a bear market.

The Latin phrase sine qua non means “without which not,” which refers to something that is a necessary or indispensable requirement. The sine qua non of successful long-term investing entails constantly assessing and reassessing the magnitude of potential losses relative to potential gains. When downside risks are elevated and potential gains are muted, you should hold a more conservative portfolio. Conversely, when the risk of loss is eclipsed by potential gains, it is prudent to take more risks with your investments.

Theory, Practice, and Yogi Berra

Baseball legend Yogi Berra stated, “In theory, there is no difference between theory and practice. In practice, there is.”

If you dial up your risk profile when the odds favour doing so and take some chips off the table when the probabilities dictate as such, your long-term performance will inevitably be well above average: so far so good. Unfortunately, accurately assessing and reassessing these probabilities as they ebb and flow over time is no easy feat.

You can’t Predict Behaviour

First the bad news: I don’t believe there is any accurate way to calculate the relative magnitude of upside vs. downside risk over the short term … and by the short term, I mean periods of at least one to two years! One need only to observe markets over the past three decades to appreciate that investors can persist in irrational behaviour for longer periods and with greater voracity than might seem possible.

In hindsight, most investors should have exercised prudence long before tech stocks reached their peak in early 2000 or real estate sung its swan song in 2008” but they didn’t. Similarly, they should have been scooping up bargains en masse either before, during, or not long after markets bottomed in early 2003 and March 2009: but they didn’t.

Excesses and financial aberrations cannot be explained by classic financial theory. Rather, their root lies in human behavioural biases and emotions, which can prove sufficiently powerful to propel asset prices to unrealistically optimistic and pessimistic levels. Greed and fear are impossible to precisely gauge or time and are arguably the largest determinants of prices over the short term. Given these facts, attempting to assess the relative risk of loss vs. opportunity cost over shorter horizons is an exercise in futility.

Valuations are a Proxy for the Margin of Safety

Valuations serve as a proxy for the margin of safety that is embedded in asset prices, and by extension for how vulnerable prices are to delivering subpar or even negative average annualized returns over the next 5-7 years.

Market Responses to Various Environments by Valuation Level

  • When valuations stand near the high end of their historical range, even strong economic and earnings growth may fail to result in higher-than-average annualized returns over the next several years, while anything short of such an environment is more likely to result in anemic performance or even losses.
  • When valuations stand near the middle of their historical range, prices are most likely to track economic conditions and profit growth.
  • When valuations reside near the bottom of their historical range, average or even above-average returns can persist even in the face of subpar economic conditions and/or profit growth, while more favourable or even average conditions are likely to produce strong gains.

Risk and Reward: Probability Distribution by Valuation


As valuations increase, the probability distribution shifts to the left, indicating a lower likelihood of gains and a higher probability of losses. Similarly, a decline in valuations results in a rightward shift in the distribution, portending an increased chance of gains accompanied by a lower risk of losses. At extremes, when markets are priced to perfection, there is almost no amount of good news that can prevent subpar returns over the next five to seven years, and when they are priced for Armageddon, strong returns are likely to ensue over the same timeframe in all but the most cataclysmic circumstances. Continue Reading…
IMAX: A World of Opportunity for International Equity ETFs

Image source: Hamilton ETFs

By Hamilton ETFs

(Sponsor Blog)

International equities continue to be in focus. As global market leadership broadens, Canadian investors are paying closer attention to geographic diversification and opportunities beyond North America. International stocks, which outperformed the U.S. stock market in 2025, have continued to attract attention as the geopolitical landscape evolves.

So far this year, Canadians have poured $22.8 billion into international equity ETFs, according to National Bank of Canada Capital Markets[1]. In contrast, they directed just $13.4 billion to Canadian equity funds and $11.3 billion to U.S. equity funds, over the same period.

Recent market performance has helped reinforce this trend. Since December 31, 2024, the MSCI EAFE Index rallied 40.5% compared to 24.6% for the S&P 500[2].

This combination of improved relative performance and more attractive valuations has helped bring international equities back into focus for investors looking to broaden exposure beyond North America. This shift has also been reflected in market commentary. Yardeni Research began recommending a “Go Global” approach in December 2025, after more than a decade of favouring a “Stay Home” allocation. “So far this year, the U.S. has been among the laggards in the global performance derby,” he wrote in a research note published April 27, 2026.

Canadian investors have plenty of options for accessing international equity exposure. Yet for those seeking attractive, tax-efficient monthly income from developed markets outside North America, the available solutions have been far more limited. That’s why we’re closing that gap with the Hamilton International Equity YIELD MAXIMIZER™ ETF (IMAX).

Introducing IMAX

IMAX is designed for investors seeking diversified international equity exposure paired with attractive, tax-efficient monthly income. To achieve this, IMAX holds ETFs that provide exposure to both the MSCI EAFE Index and MSCI EAFE IMI Index and overlays a covered call strategy on a portion of the portfolio. The MSCI EAFE Index captures developed markets outside the U.S. and Canada.

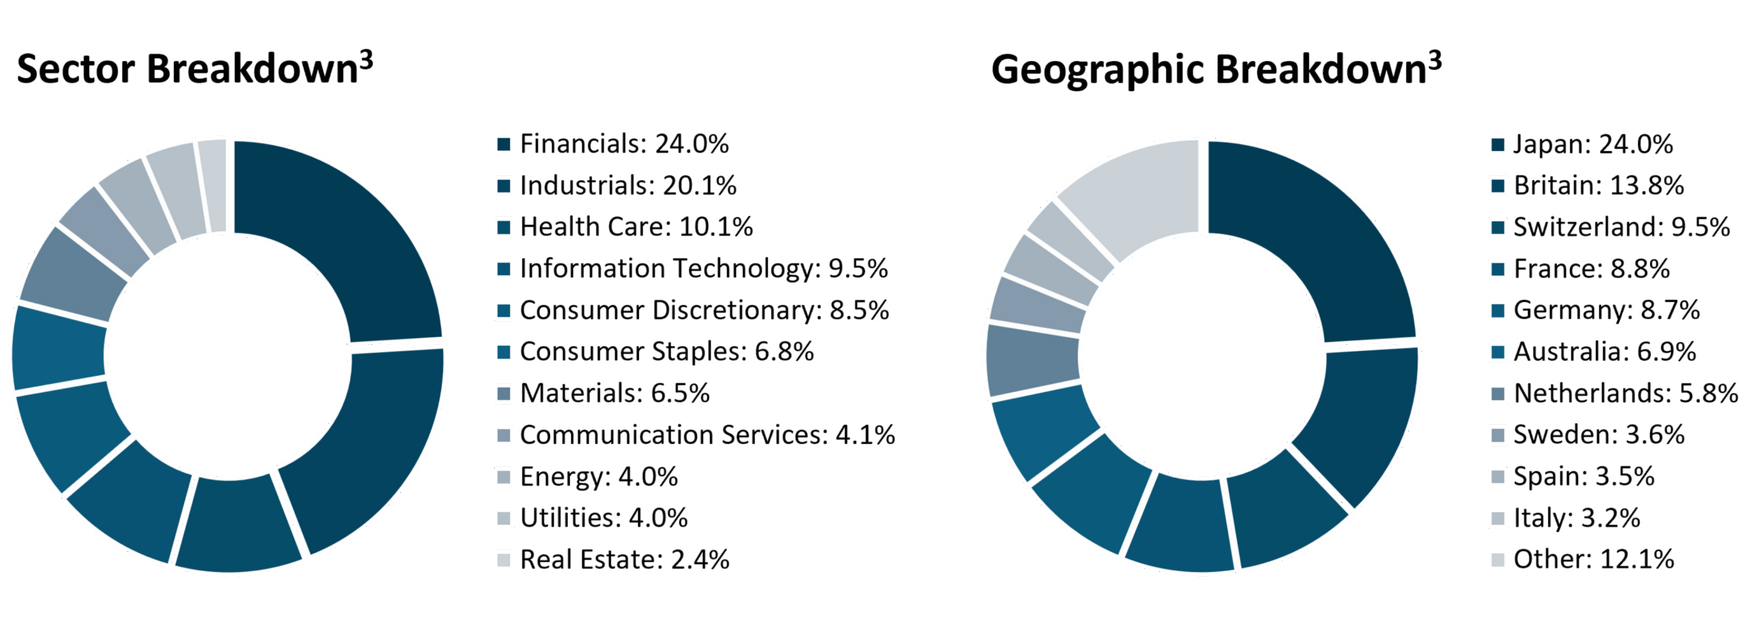
International and global covered call ETFs remain relatively limited in Canada. The few available strategies often have significant geographic concentrations, such as Europe or the U.S., or provide exposure to a narrower group of companies through concentrated portfolios. By contrast, IMAX offers broad developed market exposure specifically outside North America. Through this approach, investors gain exposure to more than 2,500 large-, mid- and small-cap equities across markets including Japan, Britain, Switzerland, France, Germany and Australia.

To help generate monthly income, IMAX employs an actively managed covered call strategy overseen by our experienced options team. Like the other ETFs in our YIELD MAXIMIZER™ suite, IMAX utilizes an income first approach that primarily writes at-the-money call options in an effort to generate higher option premiums to provide enhanced cash flow potential. The strategy also maintains a flexible coverage ratio, allowing the portfolio management team to balance monthly income generation with long-term capital appreciation potential.

Importantly, IMAX helps provide tax efficient income, as options premiums are generally taxed as capital gains and/or return of capital.

Going Global with IMAX

Diversification is one of the most important principles of portfolio construction, and it applies not only across asset classes (stocks, bonds, commodities etc.), sectors and market capitalizations, but also regions. Continue Reading…

BMO ETFs’ third annual ETF Investor Day aimed at DIY investors

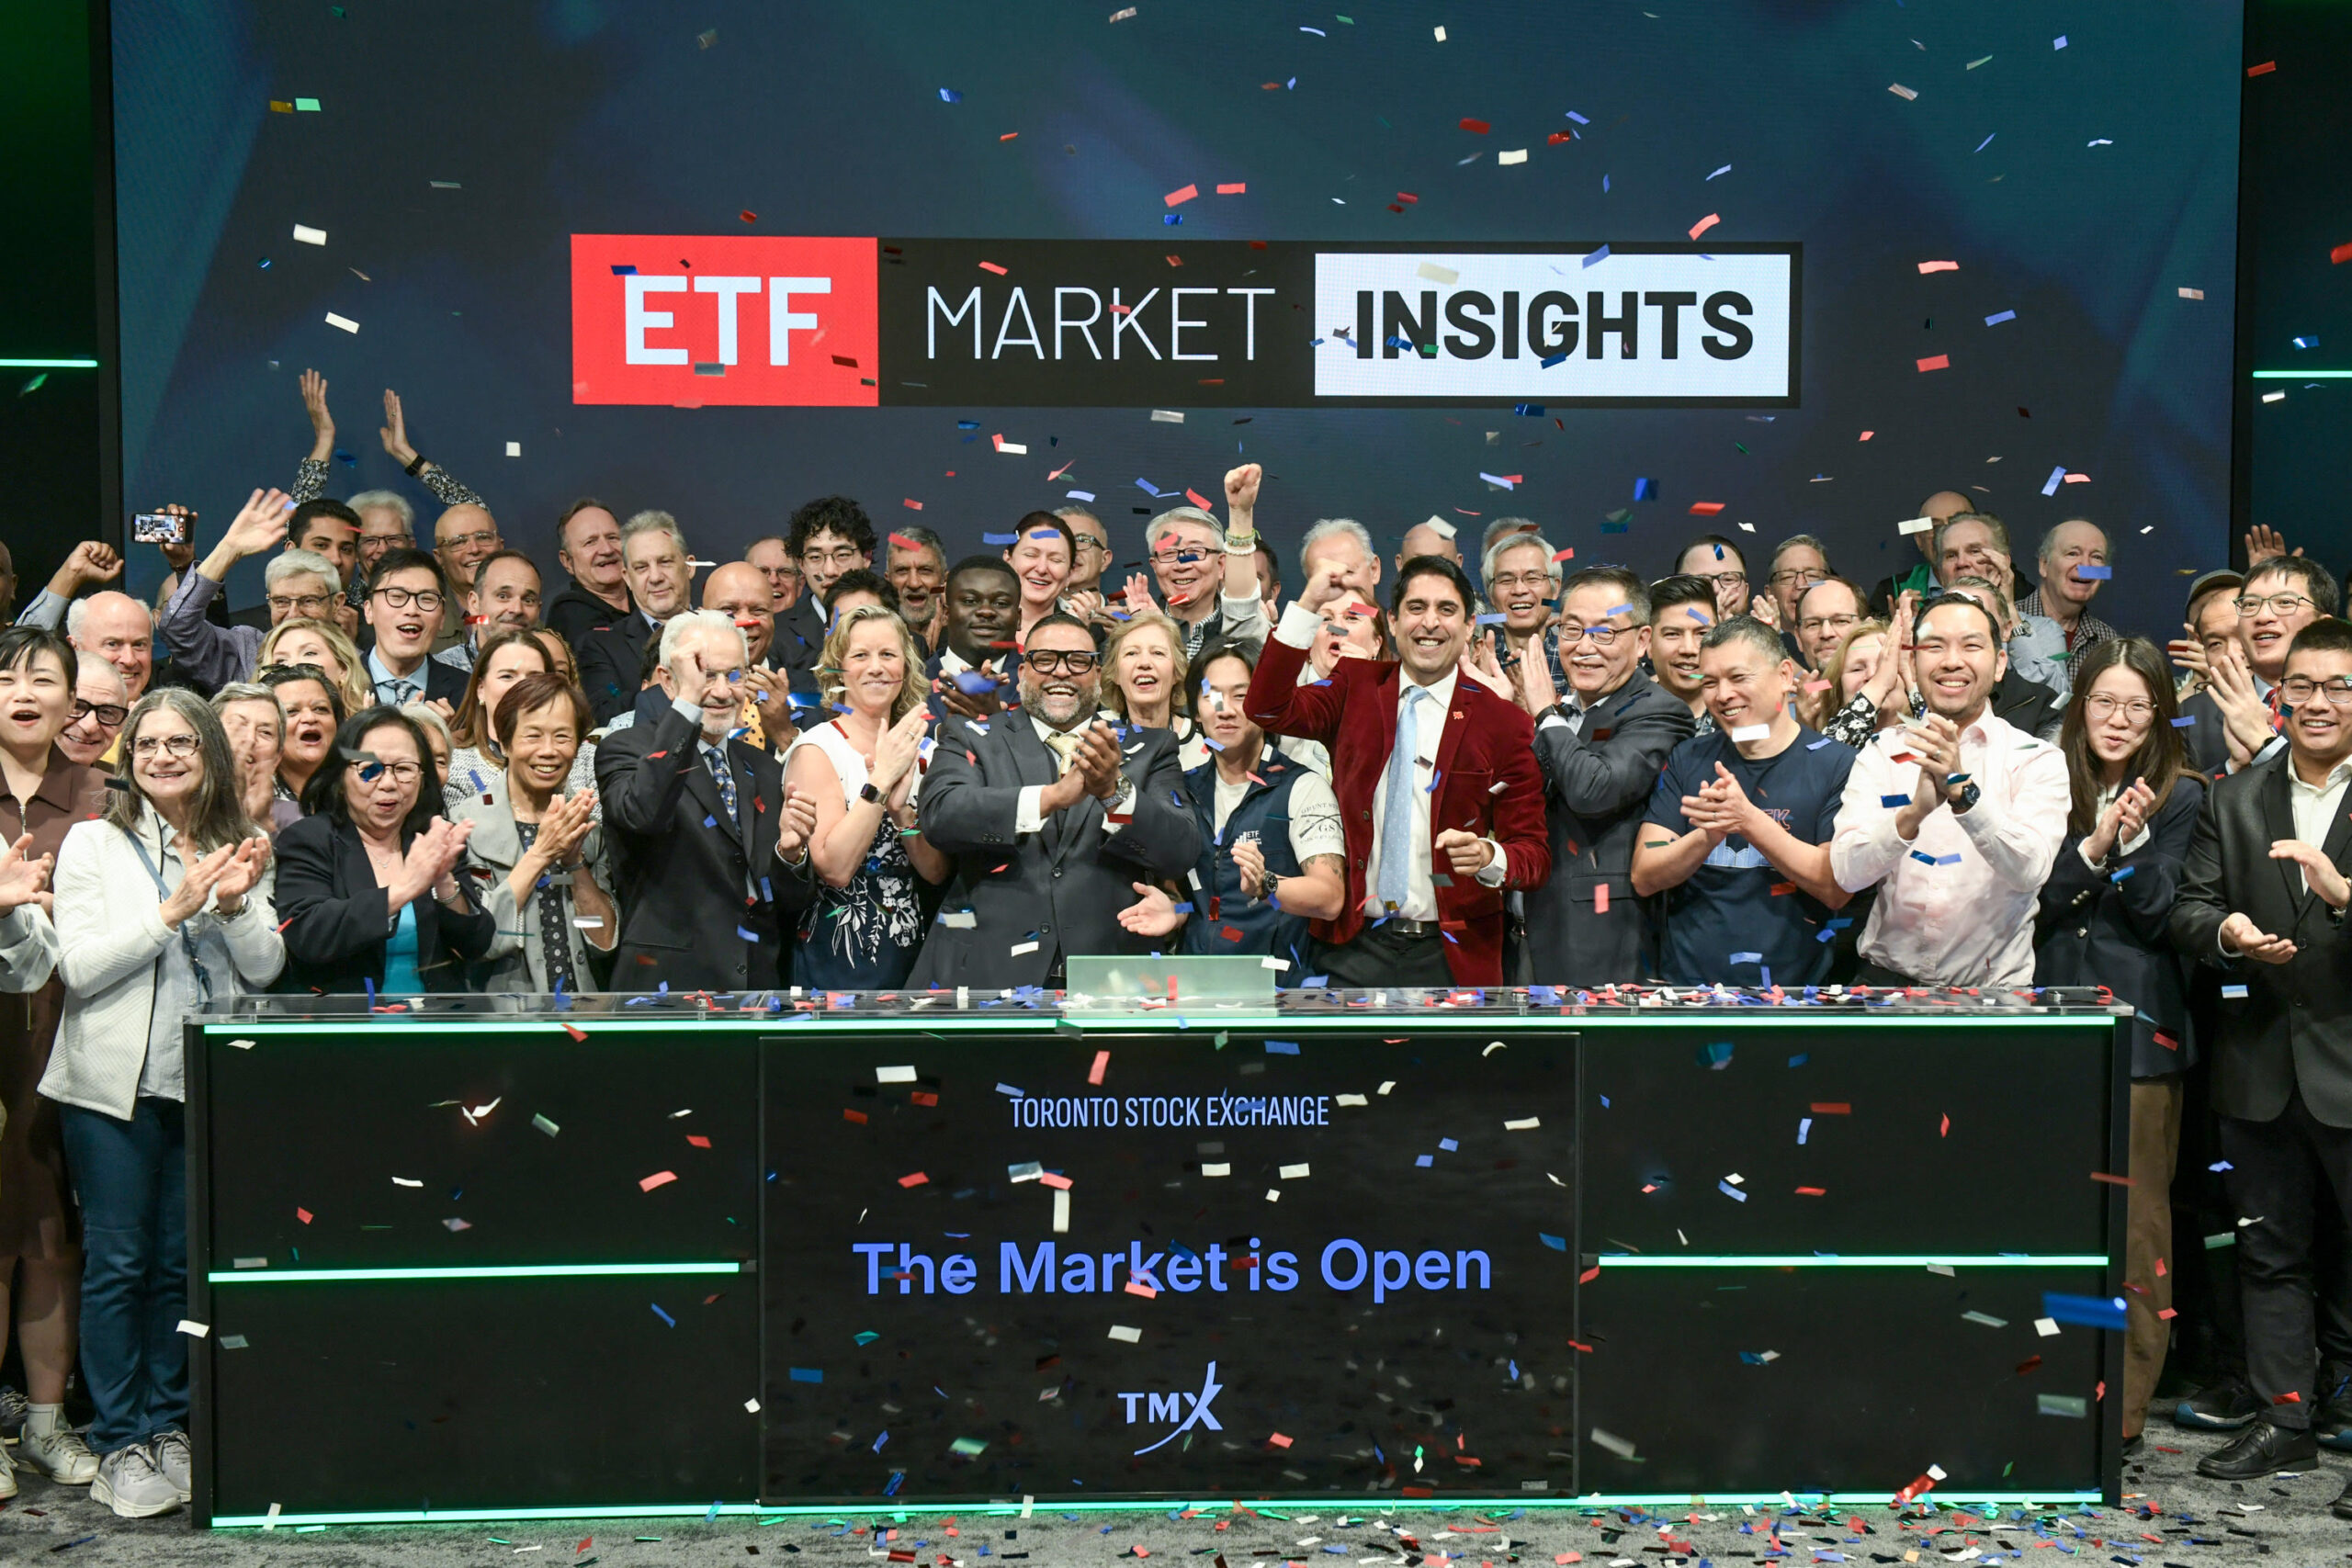
On Tuesday, BMO ETFs conducted its third annual ETF Investor day. Conducted at the Toronto Stock Exchange, Do-it-yourself investors and finfluencers [Financial Influencers] were on hand for the ceremonial opening of the exchange, shown in the photo on the left. The Investor Day will also be held in Montreal on June 18: Details here. 

This marks BMO’s 17th year as a Canadian ETF provider, with $165 billion in Assets under management and 66 tickers  with a 10-year track record.

The first presentation was an economic and investing overview from Fred Demers, Director of Multi Asset Strategy at BMO Global Asset Management. He teased whether the R word refers to a Recession or Resilience when it comes to forecasting the economy. While the world is likely to remain messy, “the good news is the world always carries on.”

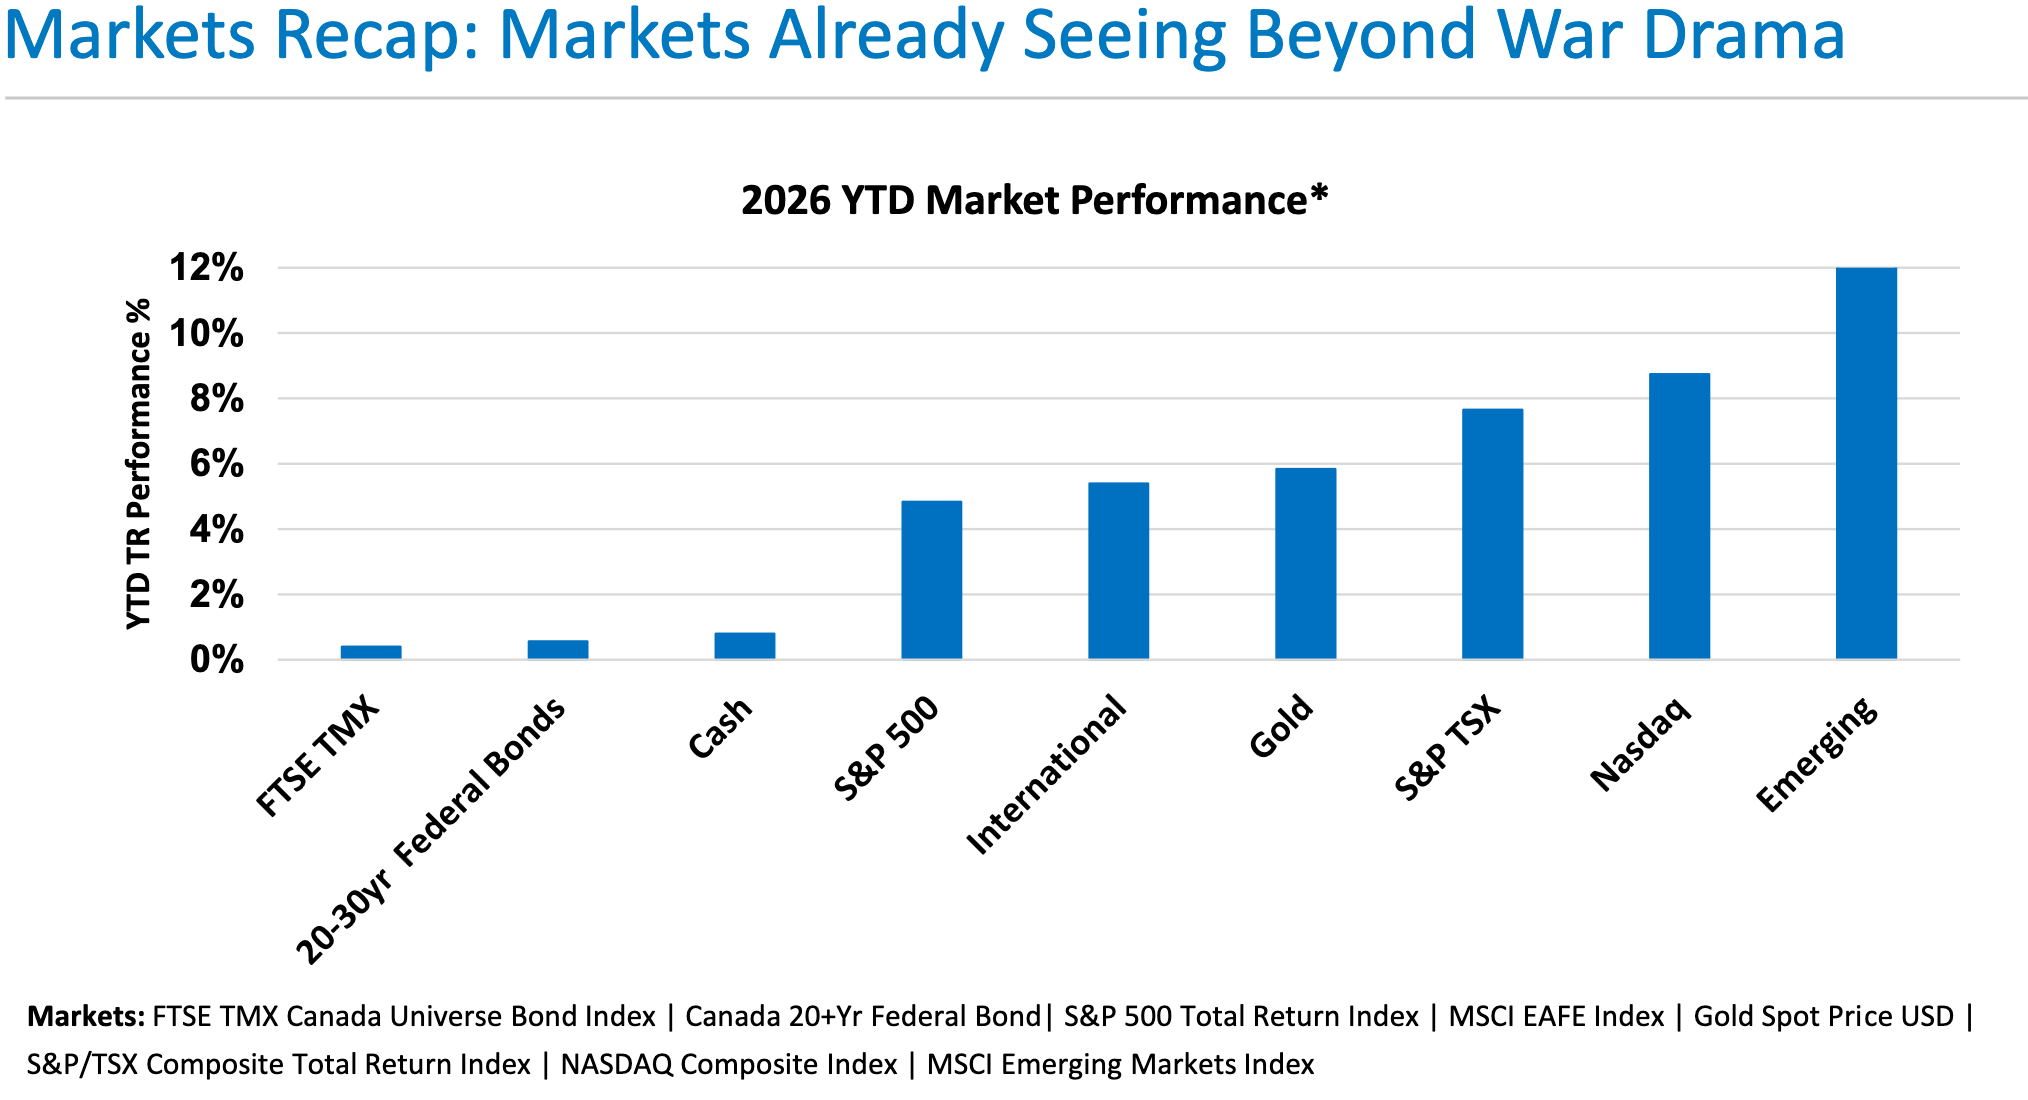
Demers is particularly bullish about the long-term prospects of the U.S. economy and the Tech giants that power innovation and in particular the A.I. Capex boom and AI infrastructure buildout. Stock markets are already seeing beyond the drama of the war in Iran, he said, led by a 12% gain YTD 2026 in Emerging Markets, 9% or so for the Nasdaq and almost 8% for the TSX, as shown in the chart below taken from the presentation.

Fixed income is not doing much of anything, which is to be expected when the economy is doing well but would show its value if a Recession got under way accompanied by Job Loss, which he said is not yet where we are. Gold has returned almost 6%, disappointing given the Middle East conflict but “still doing its thing short-term.” Its role is not to diversify equities but to diversify fixed Income.

Obviously the oil shock hurts and is a clear negative for Growth but it remains to be seen how severe it will be. Demers said Trump’s Tariffs amount to basically the equivalent of a 3% GST (a reference to Canada’s Goods & Services Tax).

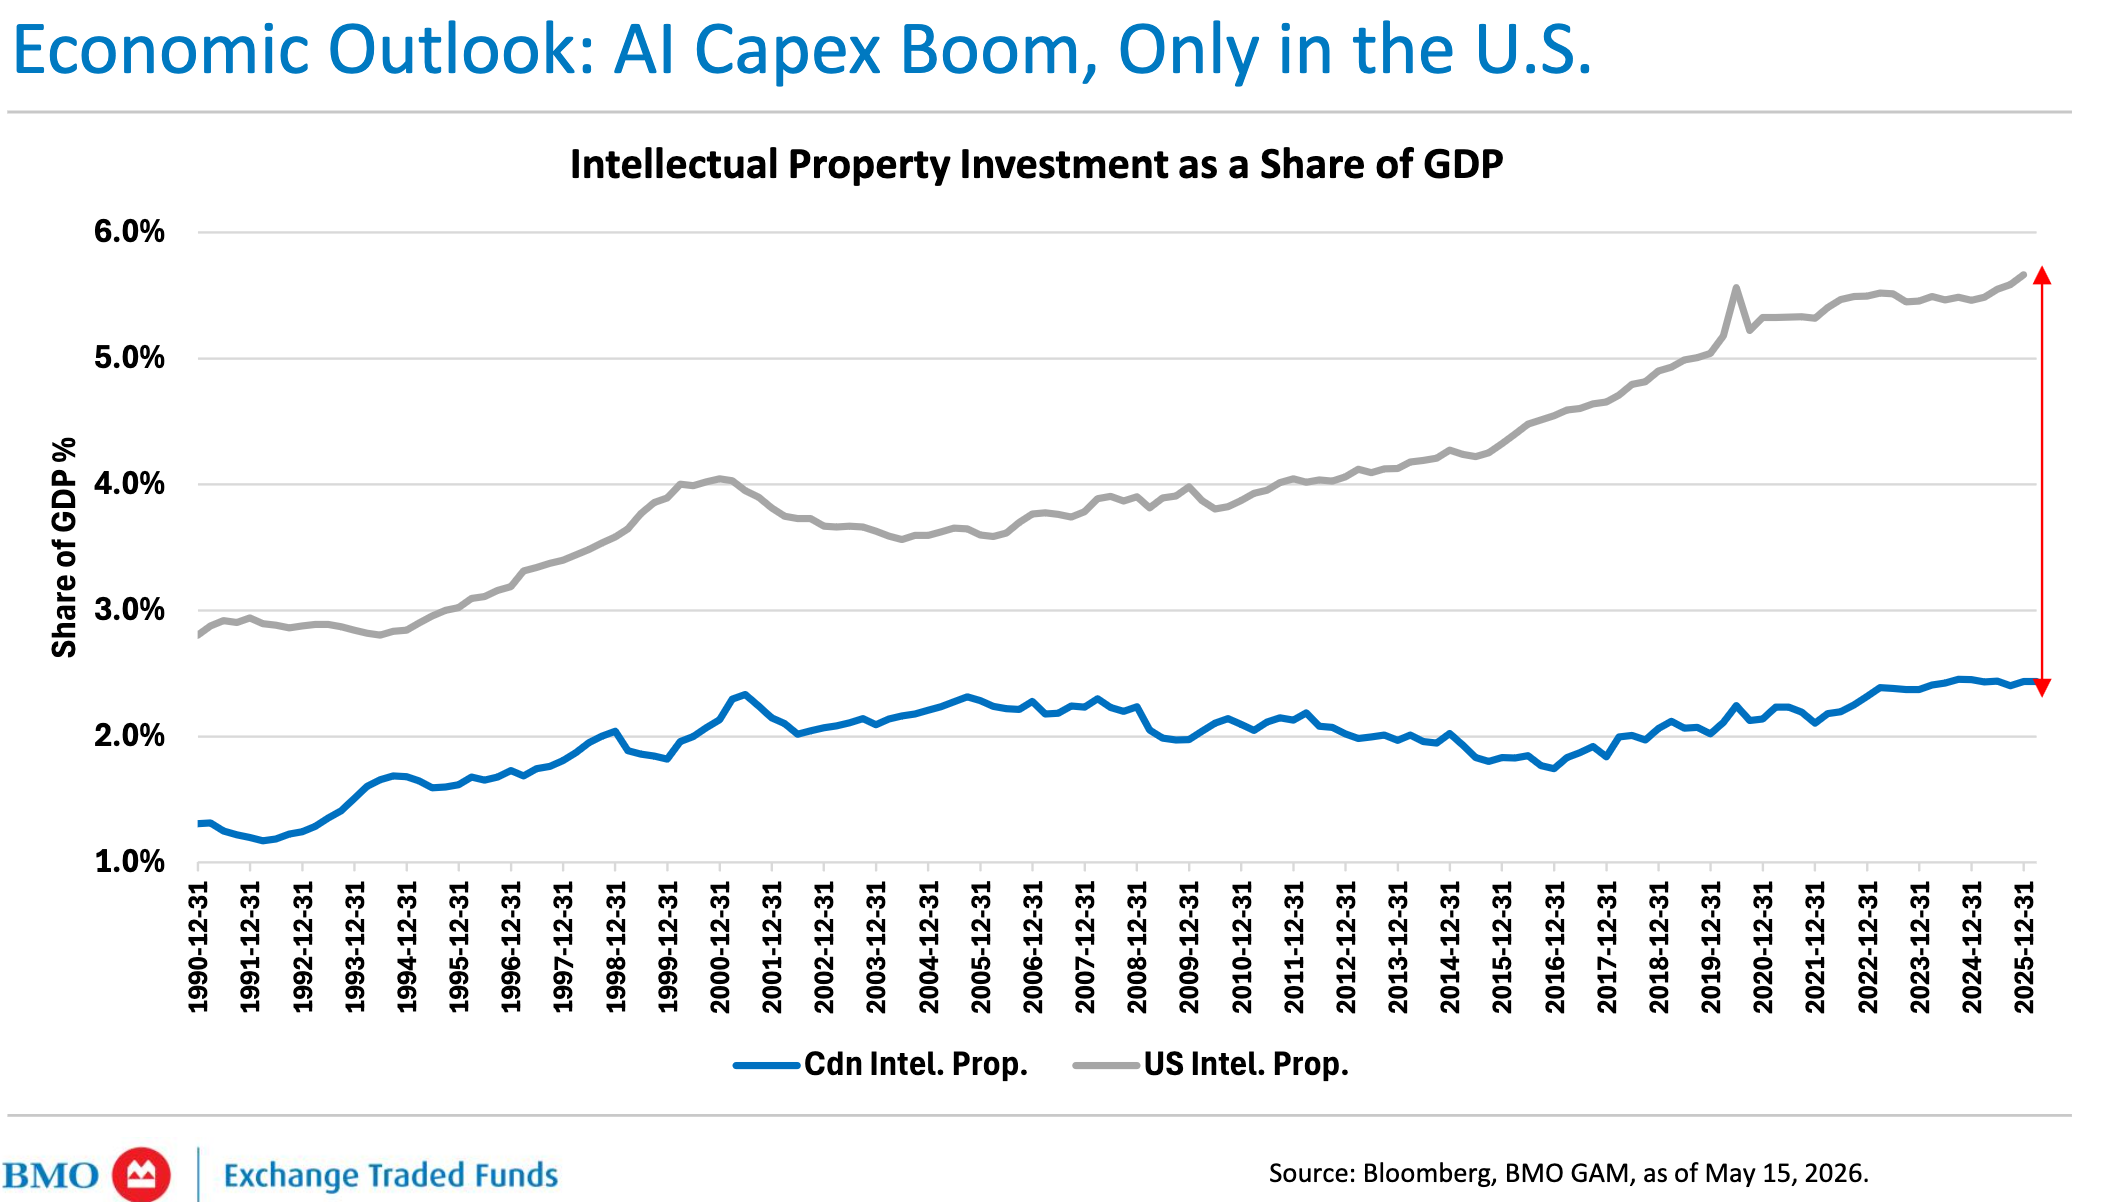
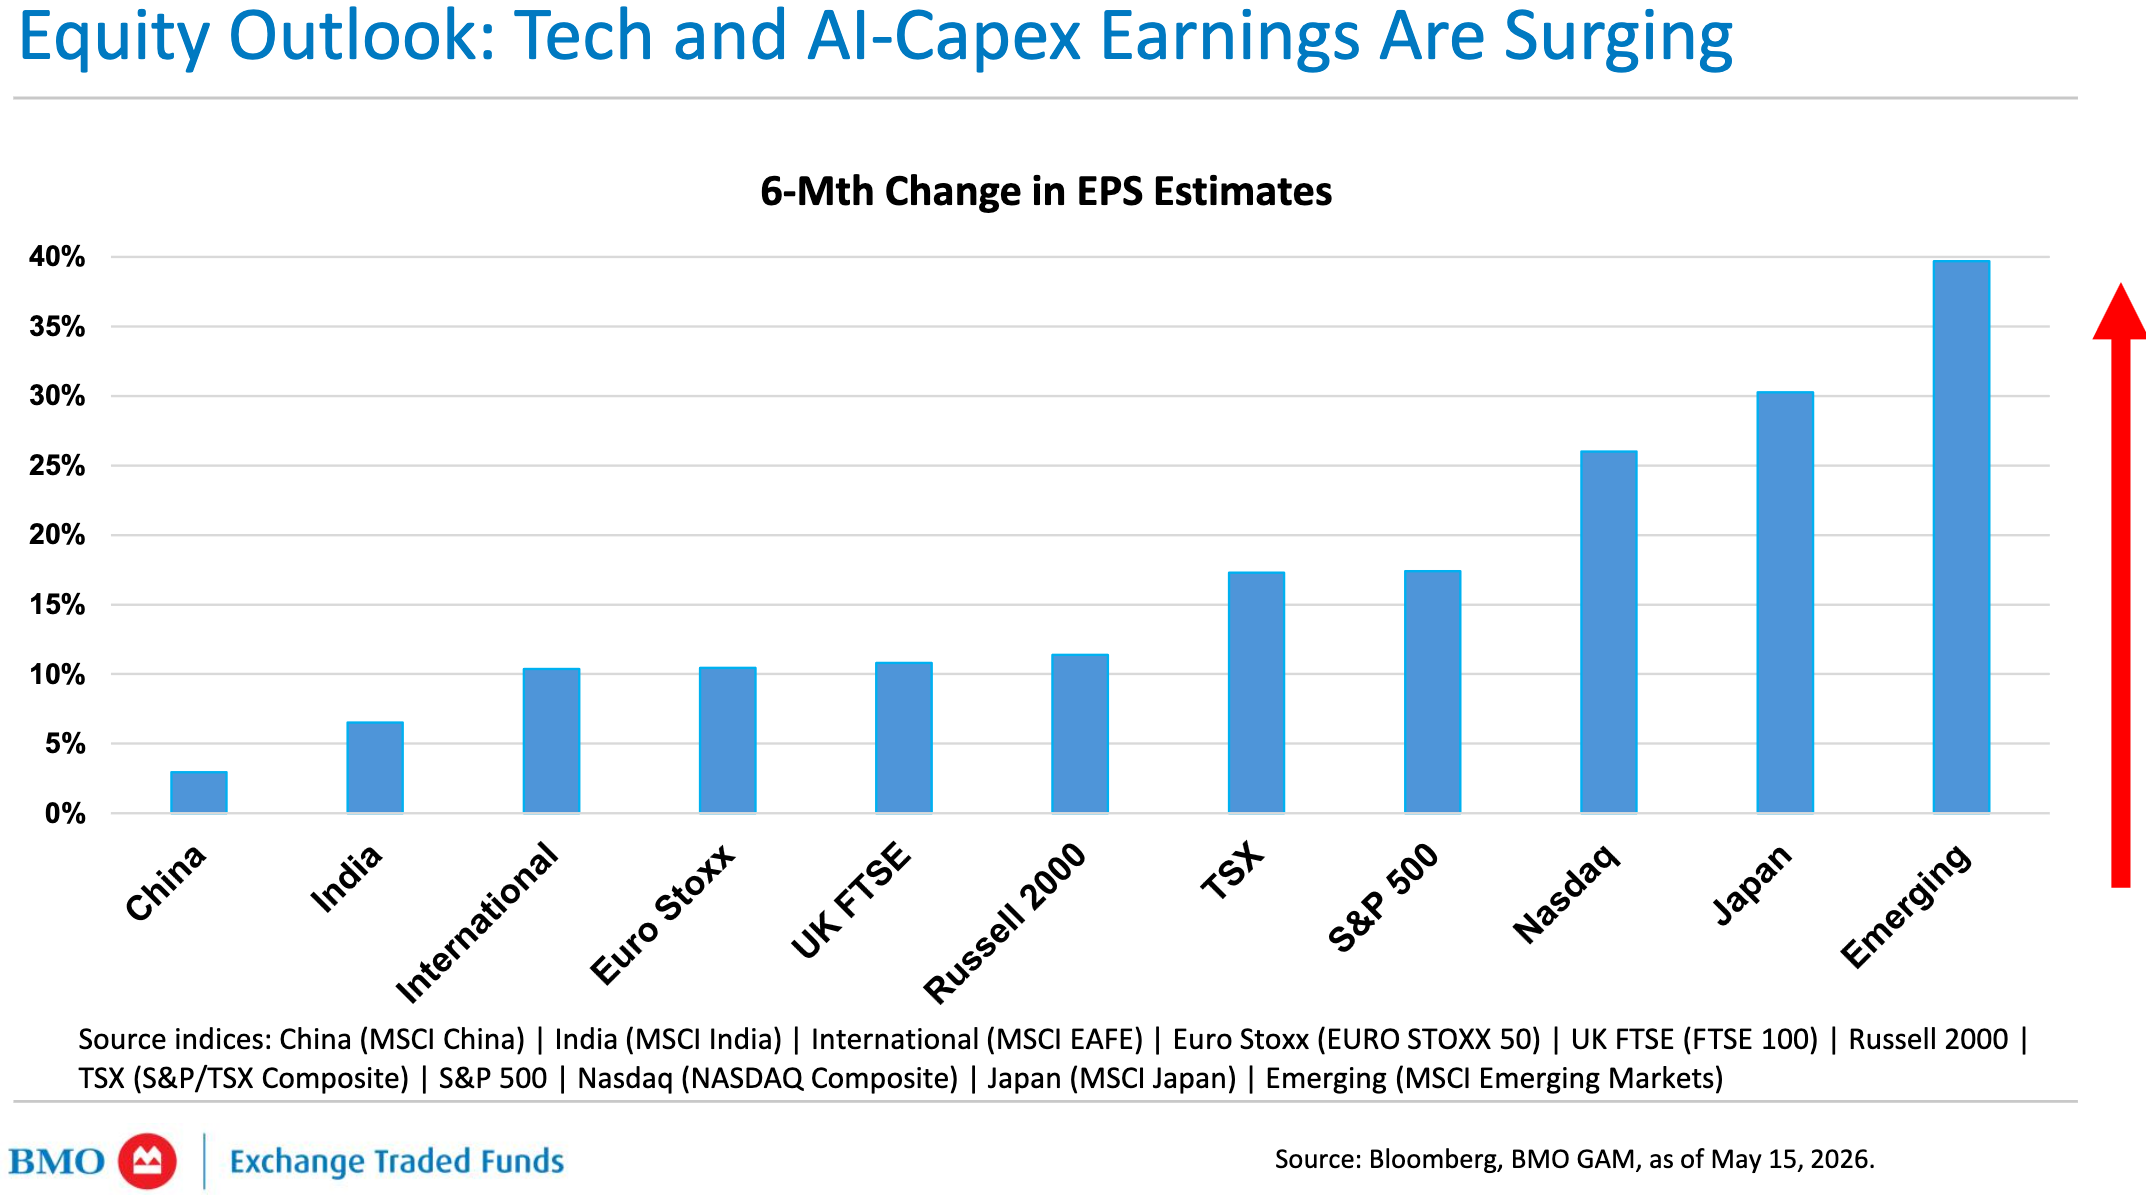
He said it’s good to diversify globally but investors worried about the impact of Trump should “be careful about exiting the U.S. entirely.” The AI race is primarily between the US and China and AI Capex will keep roaring for years if not for decades. We are “not even half way through the capex cycle.” AI Capex spending has reached a “phenomenal” US $350 billion, and is on track to pass US$750 billion in 2026; the hyperscalers are planning between $1.1 and $1.2 trillion.

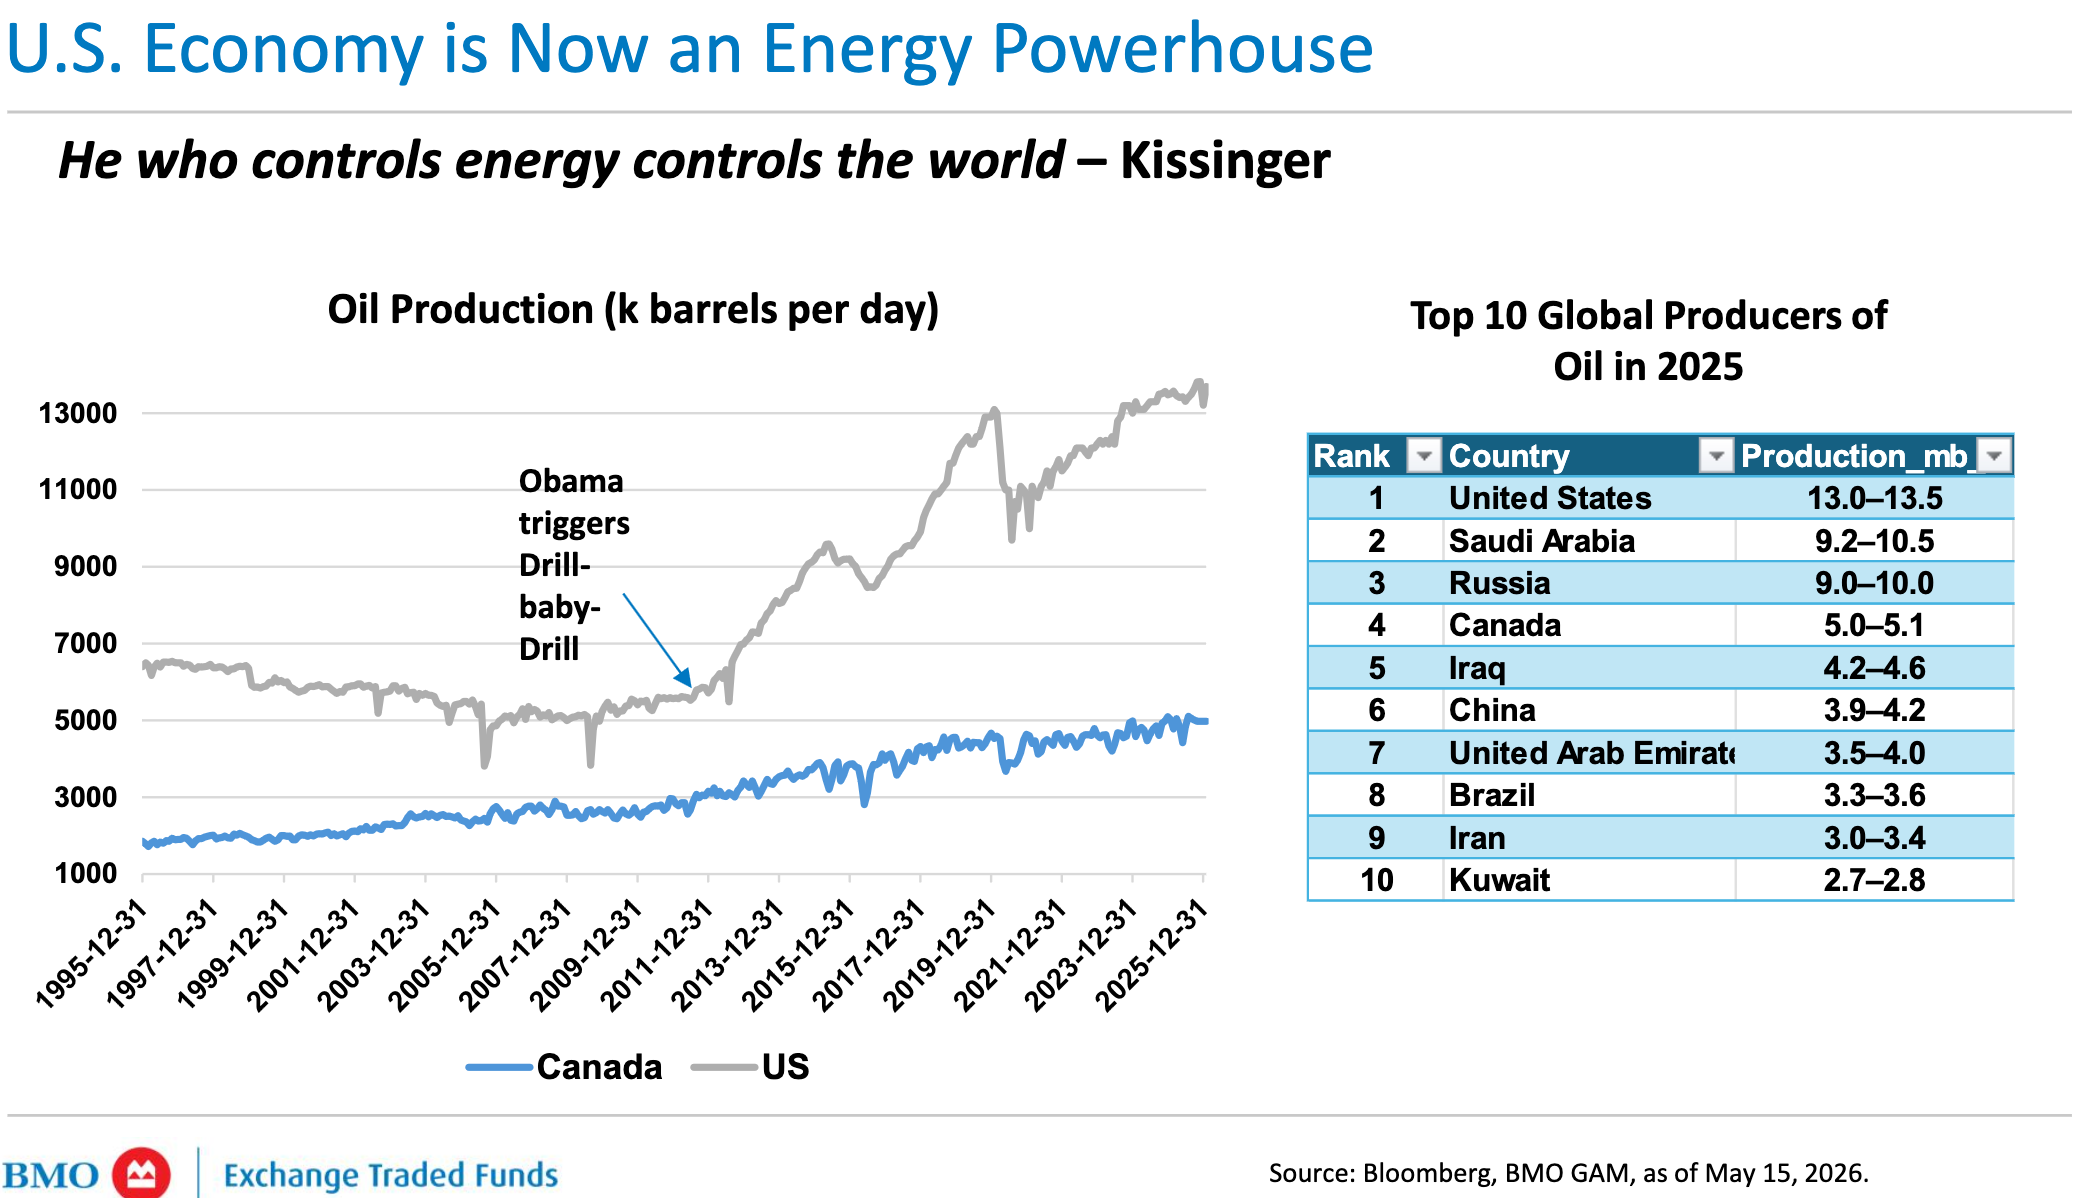
By contrast, AI Capex in Canada is not even $50 billion. Just ten giant American companies generate a third of the country’s economic activity. These are the big-tech titans but the U.S. economy has also become an Energy Powerhouse: the biggest oil producer in the world and net exporter of energy. Next is Saudi Arabia and Russia, with Canada in fourth and Iran is ninth. (See chart shown in the Sector section below)

Sector ETFs

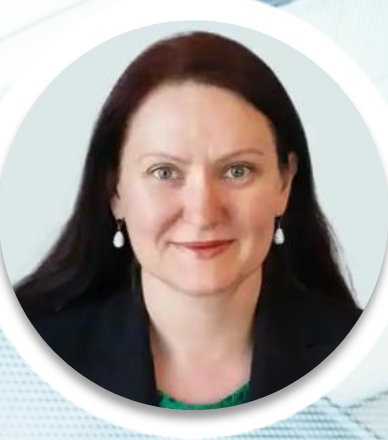
The second talk was by Simona Mocuta, managing director and chief economist for State Street Investment Management (shown on the left). BMO recently launched a suite of BMO SPDR Select Sector Index ETFs with State Street and sector investing was the focus of her talk.  She started by saying she agreed with everything Fred said, drawing laughs when she said “it’s nice to see a Canadian that still likes the United States.”

BMO’s vice president of Online Distribution ETFs Zayla Saunders asked Mocuta about a SPDR energy ETF [XLE/TSX] to capitalize on surging oil and gas prices sparked by the Iran conflict. “Go for it,” Mocuta says, “Talk AI all you want but you need Energy to make it happen.” With the Iran war, the U.S. is telling Europe to buy from the U.S., which makes Energy as “compelling buy-and-hold.” The chart below is from Demers’ presentation:

Among other sectors, Technology was by far the best performer in April, Mocuta said, but there have been over the last 12 months strong inflows into Industrials, Materials and Energy.” However, investors should also consider less-loved sectors like Healthcare.

In response to an audience question about the U.S. financial sector, Mocuta said that in the medium term banks are being deregulated, which is a huge positive after the regulatory burdens imposed after the Great Financial Crisis. Continue Reading…

Silver Tsunami: Why the Best Business Transitions involve a Warm Hand

Image: Unsplash

By Jeff Johnstone, National Bank Financial Wealth Management

Special to Financial Independence Hub

In my world, financial planning is a lot like building a home. You can spend decades refining the interior — growing revenue, managing cash flow, building something you are proud of — but without a strong foundation, the entire structure remains vulnerable.  For the roughly 500,000 small business owners across Ontario, that foundation isn’t only  the balance sheet; it’s a clear, well-structured succession plan.

 We’re standing on the edge of what many call a “silver tsunami.” By 2030, more than one in five Ontarians will be 65 or older. It represents one of the largest transfers of leadership and wealth in history. Today, nearly 75% of business owners are planning to exit within the next decade. For founders, that creates a new reality because it’s no longer about finding just a buyer, it’s about being a business worth finding and buying. Yet while many expect to exit, few have a clear plan for what happens next.

 When entrepreneurs sit down with us, three themes tend to surface:

  • Concentration risk — the majority of their net worth is tied to a single asset: the business
  • Tax complexity — not whether tax will be paid, but how much can be preserved
  • Uncertainty — stepping away is not just financial, but deeply personal

 These challenges are all interconnected. For incorporated business owners, personal and corporate wealth need to be aligned: linking how value is created inside the business with how wealth is ultimately realized outside of it. The goal isn’t  to extract value at the end, but to translate it gradually into long-term financial independence.  Without that bridge, the business risks becoming not a means to an end, but the end itself.

Founders often underestimate Timing

 One of the biggest misconceptions we see is timing. Many founders believe they can decide to sell and complete the process within six months. When in reality, a successful, high-value transition rarely follows a short-term timeline. The average timeline is closer to five years from initial planning to final sale. Understanding this matters because, if you wait until you’re ready to exit — or until you’re burned out — and believe it can be all closed quickly, you’ve already lost leverage and, in many cases, left value on the table. Buyers don’t just assess financial performance; they assess risk. A business heavily dependent on its founder carries a very different profile than one that can operate independently.

 The earlier you start, the more control you have. That’s the takeaway here.  Early planning changes what buyers see. It creates time to strengthen management, reduce key-person risk, and professionalize operations. It also allows for what I often describe as a “financial clean-up”—organizing financials, addressing shareholder loans, and ensuring the business can run without you at the center.  Because ultimately, it’s about being profitable, as well as it’s being sellable.

 One of the  most complex parts of succession is rarely financial, and  happens outside the boardroom and round the dinner table.  We call this “dinner table math,”  when assumptions are made but haven’t (or rarely) been discussed. For example, parents may assume the children will take over the business, but they do not want to. Yet,  the children may feel obligated to, even if their interests lie elsewhere. Beneath it all are unspoken expectations about what feels fair.

Where many transitions begin to unravel

 This is where many transitions begin to unravel. Nearly 70% fail because of breakdowns in communication and trust, versus market conditions. For example, in one case we had one family assume the business would pass to the next generation. Through structured conversations, it became clear that while the children respected what had been built, none of the kids wanted to run it. That honesty  was difficult, but the clarity was necessary.  It opened the door to a different path that was  focused on a structured sale to an external buyer, alongside a plan to distribute proceeds in a way that felt fair and transparent. Just as importantly, it preserved the family relationships.

 These are not decisions founders should navigate alone. With the right advisory team — wealth advisors, accountants and legal professionals — we can help create space for better conversations and more thoughtful decisions.  In our experience, the best work happens alongside a dedicated M&A and investment banking team who can help deliver a more coordinated approach. Preparation becomes more intentional, buyer selection more strategic and outcomes — across valuation, structure, and legacy — more aligned with what matters most. Continue Reading…

Retired Money: FIRE Bloggers starting Early Retirement in their 50s and even 40s

Deposit Photos

My latest MoneySense Retired Money column looks at a handful of FIRE bloggers who should be familiar to readers of this site, Findependence Hub: notably Mark Seed of myownadvisor and Bob Lai of Tawcan.

As you can see by clicking on the column headline, How are FIRE adherents making out?, Seed recently announced he has reached his Financial Independence in his early 50s. Bob Lai, meanwhile, is still working in his 40s but blogged on how he hopes to reach Findependence before 2030.

The MoneySense column also updates the status of veteran personal finance columnist Rob Carrick, who ended full-time employment at the Globe & Mail last year, the subject of an earlier Retired Money column.  And we mention a good blog by The Retirement Manifesto’s Fritz Gilbert about the 12 Good Years between age 60 and 72. As I ironically close the column with, it seems I have just used up my own 12 good years!

The real focus of the MoneySense column is however Mark Seed, just as it was Carrick last summer. In both cases, we exchanged views in Zoom or GoogleMeets over the course of an hour or so.

By now, it’s hardly necessary to remind readers that the FIRE acronym stands for Financial Independence Retire Early, as the image above  illustrates.

Note that our FIRE subjects in the column span four decades: Lai his 40s, Seed his 50s, Carrick his 60s and I am in my 70s, evidently still running this website and writing for MoneySense, a former employer.

The end of Salaried Employment does not mean no more Working

The observant reader will note that none of the bloggers mentioned here have actually begun the traditional “Full-Stop Retirement.” When FIRE proponents describe Early Retirement, they usually mean leaving the comfort of full-time salaried employment and all that it entails: commuting, bosses, endless meetings, tax deducted at source, annual performance reviews and so on. Continue Reading…