Decumulate & Downsize

Most of your investing life you and your adviser (if you have one) are focused on wealth accumulation. But, we tend to forget, eventually the whole idea of this long process of delayed gratification is to actually spend this money! That’s decumulation as opposed to wealth accumulation. This stage may also involve downsizing from larger homes to smaller ones or condos, moving to the country or otherwise simplifying your life and jettisoning possessions that may tie you down.

Switching your RRSP to a RRIF is best for those retiring soon

Portrait Of Smiling Senior Couple Saving Money In The Pink PiggybankConverting your RRSP to a RRIF is clearly the best of three alternatives at age 71 and there are four ways to make sure you get the maximum benefit from the RRIF (Registered Retirement Income Fund).

If you have one or more RRSPs (registered retirement savings plans), you’ll have to wind them up at the end of the year in which you turn 71. We think converting your RRSP to a RRIF (registered retirement income fund) is the best option for most investors.

You have three main retirement investing options:

• You can cash in your RRSP and withdraw the funds in a lump sum. In most cases, this is a poor retirement investing option, since you’ll be taxed on the entire amount in that year as ordinary income.

• You can purchase an annuity.

• Proceed with the RRSP to RRIF conversion

RRIFs are the best retirement investing option for most investors

Continue Reading…

Fixed Income: What about inflation?

WT_Blog_722x140_FixedIncome

kevin-temp2By Kevin Flanagan, Senior Fixed Income Strategist, WisdomTree

Special to the Financial Independence Hub

The last few months have certainly given the money and bond markets a lot of divergent news headlines to digest. Not surprisingly, the focus has been on negative rates abroad, geopolitical events and, a bit more recently, some better-than-expected employment news juxtaposed with a softer-than-expected GDP report. That begs the question: What about inflation? Isn’t that a key ingredient in the bond market mix?

Without a doubt, U.S. inflation data has taken a backseat for fixed income investors, and for good reason; there just haven’t been any fresh developments lately. Certainly, the conversation has shifted from a year ago, when deflation concerns were permeating market psychology. But the latest figures don’t elicit concerns that price pressures will be rearing their ugly head anytime soon, or at least that’s what the collective thinking is in the fixed income markets.

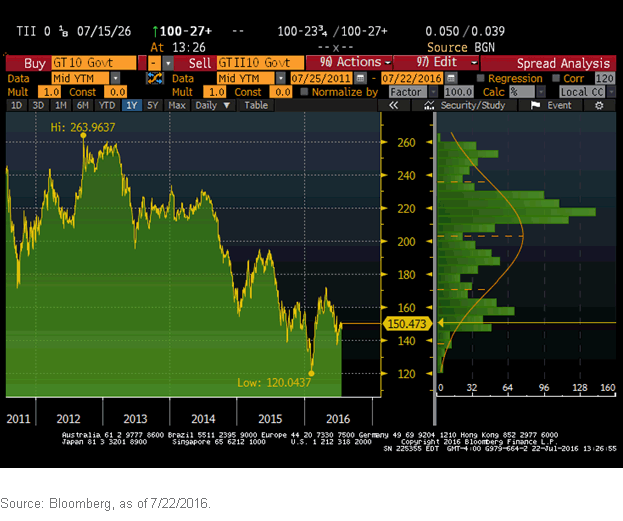
Breakeven inflation ratesvrGP Breakeven-Inflation-Rate

So, what does the inflation backdrop look like? According to the widely followed Consumer Price Index (CPI), the year-over-year inflation rate came in at +1.0% in June (Note 1)—very little changed from the readings posted over the last four months, but definitely higher than the +0.1% for the same month in 2015. The core gauge, which excludes food and energy, rose at a +2.3% annual clip and has been residing in a range last seen in 2012. There continues to be a large dichotomy between core goods (-0.6%) and core services (+3.2%) .(Note 2)

Continue Reading…

How much will my Defined Benefit pension pay in Retirement?

depositphotos_5971382_s-2015I contribute to a defined benefit pension plan at work. How much will I get from the pension plan in retirement? That depends on when I retire or leave the plan. Hang on, we’re about to get math-y.

Normal retirement age is 65 and I joined the pension plan in 2009 at age 30. Retiring in 2044 (the year I turn 65) would give me 35 years of pensionable service.

The pension plan has a retirement calculator on its website. Curious about the amount of retirement income I’d receive at various ages, I took a look. The calculator just needed a couple of inputs: current salary, plus an assumption for future annual salary increases (I used 2 per cent).

Retiring at age 65 would max-out my pensionable service and give me an annual retirement income of $46,000 in today’s dollars. But what happens if I don’t make it until 65? Retiring five years earlier at age 60 changes the equation substantially.


Retiring at 60

Continue Reading…

Capital gains tax is one of the lowest you’ll ever pay

Hand with pen pointing to GAIN word on the paper - financial and investment conceptsThere are three forms of Investment Income in Canada: Interest, Dividends and Capital Gains. Each Is taxed differently. Here’s a reminder of how smart investors use their knowledge to taxation rates, especially tax on Capital Gains, to protect their returns.

With stocks, you only pay capital gains tax when you sell or “realize” the increase in the value of the stock over and above what you paid for it. (Although mutual funds generally pass on their realized capital gains each year.)

Several years ago, the Canadian government cut the capital gains inclusion rate (the percentage of gains you need to “take into income”) from 75% to 50%. For example, if an investor purchases stock for $1,000 and then sells that stock for $2,000, then they have a $1,000 capital gain. Investors pay Canadian capital gains tax on 50% of the capital gain amount. This means that if you earn $1,000 in capital gains, and you are in the highest tax bracket in, say, Ontario (49.53%), you will pay $247.65 in Canadian capital gains tax on the $1,000 in gains.

The other forms of investment income are interest and dividends. Interest income is 100% taxable in Canada, while dividend income is eligible for a dividend tax credit in Canada. In the 49.53% tax bracket, you’ll pay $495.30 in taxes on $1,000 in interest income, and you will pay $295.20 on $1,000 in dividend income.

Three capital-gains strategies

Continue Reading…

Dividends: The Foundation of the Smart Beta Movement

blog-see-more-dividendschris_gannatti_crop-bwBy Christopher Gannatti, Associate Director of Research, WisdomTree

Special to the Financial Independence Hub

Smart beta exchange-traded funds (ETFs) are rapidly proliferating and capturing assets at a faster clip than the broader ETF industry. In 2015, 143 smart beta ETFs came to market, [Note 1] representing half of the year’s new ETF launches, or double the percentage of traditional beta products born last year.

Dividend strategies are one of the primary drivers of smart beta ETF growth. Smart beta ETFs had about $616 billion in assets under management at the end of 2015, [Note 2] and more than a quarter of that total was allocated to dividend-oriented funds.

Since the publication of the widely followed Fama-French research in 1993, outperformance of fundamentally weighted indexes has mostly been attributed to the market factor, the size factor (mid- and small caps outperforming larger stocks) and the value factor. [Note 3] Later, momentum factor was added as an accepted driver of fundamental weighting’s ability to top market cap-weighted strategies.

At WisdomTree, we believe weighting by dividends elevates fundamental indexing or smart beta. In 2006, 25 dividend ETFs [Note 4] came to market, 22 of which courtesy of WisdomTree. Our Dividend Stream® weighting methodology offers distinct advantages over weighting by market capitalization, dividend yield or focusing on the number of consecutive years that companies have increased payouts. Continue Reading…