Decumulate & Downsize

Most of your investing life you and your adviser (if you have one) are focused on wealth accumulation. But, we tend to forget, eventually the whole idea of this long process of delayed gratification is to actually spend this money! That’s decumulation as opposed to wealth accumulation. This stage may also involve downsizing from larger homes to smaller ones or condos, moving to the country or otherwise simplifying your life and jettisoning possessions that may tie you down.

Avoiding the big retirement mistakes

By Mark Seed, myownadvisor

Special to Financial Independence Hub

In a few posts on my site over the years, I’ve shared some big retirement mistakes to avoid. This becomes even more important now that we’re entering a new chapter in our lives: semi-retirement / work on own terms.

Are we ready? Can we avoid some big investing and related retirement mistakes that experts share?

In that spirit as part of new pillar post I hope to update annually and anchor my progress around, here are some of the ways I hope to avoid some big retirement mistakes.

I certainly won’t be perfect but I’ll do my best based on this infographic and more below:

20-common-investing-mistakes - Visual Capitalist November 2023

Attribution/thanks to Visual Capitalist. @VisualCap

1. Expecting too much

I believe I/we have reasonable long-term return and inflation assumptions. Our projections include at the time of this post:

  • 5% annualized returns from a 90% equity/stock + 10% cash/cash equivalents portfolio (excluding my small workplace pension), and
  • 3% sustained inflation. 
  • Some go-go spending years from now until age 79/80 give or take.

I’ll link to my latest Financial Independence Budget update at the end of this post to support any planning assumptions you might have.

What are your key assumptions?

2. No investment goals / 3. Not diversifying

I think we should be good:

  1. We remain invested in our Canadian and U.S. individual stocks near-term, although I could see a near-term day in 2025 or 2026 whereby I sell off all remaining/handful of U.S. individual stocks we own and just put all ex-Canada stocks into a low-cost ETF like my favourite to date: XAW. I would however keep my existing 25 Canadian stocks for income and growth for now; to avoid capital gains in our taxable accounts.
  2. We are not focused on short-term returns since we remain 90% equities. That said, short-term, we are hopefully setting aside enough cash/cash equivalents in 2025 to draw down said cash in 2026 and 2027. Planning for 2028+ has not started yet but we have time to organize ourselves …
  3. We have our long-term drawdown plan: NRT which means a mix of living off dividends from our Non-Registered Accounts (N) with corporation withdrawals, drawing down our RRSPs (R) over time, and therefore leaving our TFSAs (T) until the end.

Our hybrid investing approach using a mix of stocks and ETFs is not going to change:

  1. We own a number of Canadian dividend-paying stocks (with some U.S. stocks for now) for income and growth.
  2. We own a few low-cost ETFs for extra diversification.

4. Focusing on the short-term

Fail!

I’m looking forward to the short term!

We are looking forward to our semi-retirement years and seeing what opportunities may appear in the coming years. I get what the infographic is saying though. 

5. Buying high and selling low

I can’t predict the future, can you?

I’m at a point in my investing life whereby if I have the money, sure, I will invest more but I don’t have to.

Besides, when you index invest, the best price is today’s price. The stock market is a forward looking tool.

“Someone is sitting in the shade today because someone planted a tree a long time ago.” – Warren Buffett

6. Trading too much

Nothing really to worry about here. I’m no longer 22-years-old and into penny stocks on this list!

Here are other ways to kill your retirement plan:

7. Paying too much in fees

No longer a problem via owning many individual stocks; no trading, I only do some periodic buying and we maintain low-cost ETFs for growth.

8. Focusing too much on taxes

In other articles on my site about investing mistakes, I’ve seen some expert concerns about dividend income in a taxable account and at the same time, I’ve seen the same experts say not to let the taxation tail wave the investing dog per se.

Mixed messages for sure.

When it comes to dividends, I continue to remain on record that dividends are not the be-all, end-all but work for us especially in our non-registered accounts in that:

  • any company that does not pay out a dividend, may alternatively provide other forms of shareholder returns: in the form of future capital gains, stock price increases, share buybacks, other.

This means dividends aren’t everything and never have been but they can be very good.

So I do like them. I will spend them. I hope to get more of them over time!

9. Not reviewing regularly

We review our portfolio every few months, in detail. We are good.

10. Misunderstanding risk

I like this one. I feel market volatility and risk while related are not the same.

Volatility:
  • Consider this like the price swings – how much an asset value fluctuates in price over time.
  • High volatility means prices swing up and down sharply, while low volatility suggests a smoother, more predictable up and down ride.

Risk:

  • Possibility of losing money over time, with many specific types of risk: stock market risk, credit risk and housing market risk and so on.
  • Risk can be framed as short-term or long-term, like “there is a risk of cash losing out to inflation over the next 2 years.”

Volatility isn’t the same as risk but they are related. Some stocks in some sectors might be highly volatile, like tech-stocks, but not all stocks nor all tech-stocks may carry the same risk.

11. Not knowing your performance

I monitor our portfolio performance often but I’ve largely given up on detailed benchmarking since it makes no sense to obsess over benchmarking if you are not meeting your objectives.

As long as you are meeting your goals, that’s good. That’s the priority.

Obsessing over a benchmark and feeling the need to meet an index because some expert said it was a good idea, is not.

12. Reacting to the media

Guilty.

I mean, recent tariff wars have been terrible for many reasons. While I have not yet adjusted my portfolio due these wars, I do find all the annexing of Canada rhetoric both very problematic and very concerning.

13. Forgetting about inflation

See above.

I use 3% higher spending per year in my projections.

Is that enough I wonder? You? Continue Reading…
Safe Retirement Withdrawal Rate Strategies in Canada

By Kyle Prevost 

Special to Financial Independence Hub


The concept of a safe withdrawal rate (and the 4% rule) is a key planning tool for Canadians of all ages.  After all, if you don’t have a general withdrawal plan, how can you know how much you need to save in the first place?

If you have been reading MDJ for years, you already have an idea of how to use a Canadian online broker account to DIY-invest your way to a solid nest egg.

Now you’re planning for retirement (whether it’s 20+ years away or next year) and you’re wondering how to take money out of that nest egg.  Perhaps hoping that there is a rule for how much you can take out each year in retirement, and never go broke.  That concept is generally referred to as a safe withdrawal rate, and we’ll go into detail on how this works in just a second.

We’ll even look at how to incorporate multiple accounts, such as your TFSA, RRSP, and a non-registered account into your safe withdrawal rate – as well tax rules surrounding the withdrawal of investments from those accounts.

And finally, we’ll seek to answer the question you probably really want answered: How do I turn my nest egg into a usable stream of money that I can depend on and spend as I look forward to retirement? 

Surprisingly, when it comes to discussing Canadian safe retirement withdrawal rates, and talking to folks who have retired at all ages, spending their retirement savings represents a massive mental strain for them.  I guess (as someone who has never retired or sold investments to pay for retirement) that I always thought that saving for retirement would be the hard part.

Isn’t spending supposed to be more fun than squirreling away?

It turns out that once you get into that savings mindset, it can be hard to flip the switch back to enjoying spending the fruits of your labour.  This is especially true for folks who are looking at retirement withdrawal strategies for an early retirement because they are much more likely to have been super-aggressive savers during their time in the workforce.

I didn’t go into the topic of safe withdrawal rates for retirement expecting the topic to be so deep and full of variables! After all, the concept seems simple enough, right?

How much can I take out of my investment portfolio each year, if I need that nest egg to last for 30, 35, 40, or even 50 years?

Is your Retirement Savings on Track?

Each year BMO does a retirement survey that asks Canadians a wide range of questions.

Are You Saving Enough for Retirement?

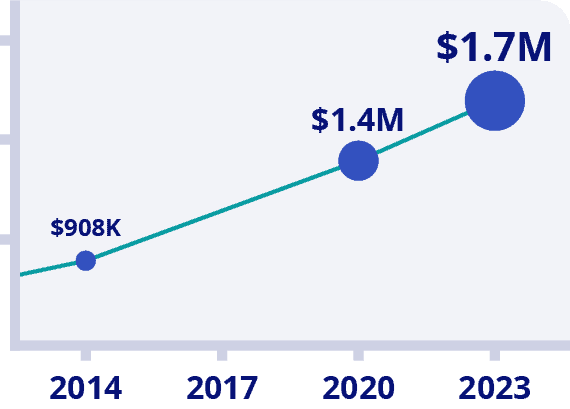
A graph showing the increase in how much Canadians need to retire

Canadians Believe They Need a $1.7 Million Nest Egg to Retire

Is your Retirement on Track?

Become your own financial planner with the first ever online retirement course created exclusively for Canadians.

The problem is that most Canadians don’t really understand how their income and expenses will interact in retirement.  Are you saving enough? Find out for sure with the first online course for Canadian retirees (click here for more details).

The 4% Retirement Withdrawal Rule

Ok, so let’s maybe start with the rule of thumb that advisors have used when looking at retirement drawdown plans for a while now.

Back in 1994 a financial advisor named William Bengen looked at the last 80 or so years of markets and retirement, did a bunch of math, and arrived at a concept we now call “The 4% rule.”

The basic idea of the 4% retirement withdrawal plan is that someone could safely withdraw 4% of their investment/savings portfolio each year and – assuming a 60/40 or 50/50 split of bonds/stocks in their portfolio – they would never run out of money.

This idea of withdrawing a certain percentage of your portfolio to fund your retirement is called the Safe Withdrawal Rate (SWR). The math behind this magic 4% figure means that if you have the nice round $1 Million investment portfolio that we all dream of, you could safely pull out $40,000 the first year, and then adjust for inflation and withdraw 4% plus inflation after that. (So if there was 2% inflation between year one and year two, you could now withdraw $40,800.)

Bengen, and another highly influential study took their rule and retroactively applied it to retirees from every single year from 1926 to 1994. They found that nearly 100% of the time (depending on what was in the investment portfolio) people could retire, and withdraw 4% of their portfolio for 30 years of retirement: and not run out of money.

In fact, over half of the time, if retirees followed the 4% rule, they not only didn’t run out of money, they finished life with more money than when they started retirement!

Keep in mind, these authors didn’t worry about OAS or CPP, or a workplace pension, or even the tax implications of different types of withdrawals. They were simply trying to come up with a useful rule of thumb for how much a person could safely withdraw from their retirement portfolio.

What the 4% Rule Means for your Magic Retirement Portfolio Number

If you can safely withdraw 4% of your portfolio to fund your retirement, then the simple math tells us that if you can accumulate 25x your annual retirement budget, you no longer have to work.

Here’s the breakdown:

  • Jane looks at her budget and realizes that once she retires she will have a lot less spending demands.  She carefully weighs the numbers and believes she’ll need $40,000 per year to quit her 9-to-5.
  • Consequently, Jane needs the magical “4% of her portfolio” to equal $40,000 per year.
  • For a 4% withdrawal to equal $40,000, Jane will need a $1,000,000 portfolio.
  • If Jane reassesses and realizes she needs $60,000 per year in retirement, Jane would need 25 times $60,000 (because 4% goes into 100% twenty-five times) which is $1.5 Million.
  • Jane might not need anywhere close to $1.5M if she intends to do a little part-time work in retirement, and is willing to use some math + research strategies to help herself out a bit when it comes to managing her nest egg!  But more on that later…

4% Safe Withdrawal Rate for Retirement: Potential Problems

Up until the 4% rule became a thing, when financial advisors were asked about safe withdrawal rates, the only thing they could really say is, “it depends.” Continue Reading…

Mark Seed on the 2% Retirement Rule

By Mark Seed, myownadvisor

Special to Financial Independence Hub

Well hello!

Welcome to some new Weekend Reading related to an article I read on not 4% rules, not 3% rules but the 2% retirement rule.

The 2% Retirement Rule

“The best retirement withdrawal strategy requires flexibility and course corrections depending on the market environment, inflation and your personal spending levels. No one actually follows through with this stuff like it shows on a spreadsheet.”

These are statements that really reasonated with me from Ben Carlson’s post entitled Why the 4% Rule is More Like the 2% Rule.

  • I desire flexibility related to our retirement income spending needs.
  • I want to use an approach that enables course corrections to happen easily.
  • I have never lived my life in a spreadsheet yet some tracking is necessary.

The 2% rule occurs when many retirees who even worry about the 4% rule constantly underspend from their portfolio from fear of outliving their money.

As Ben writes:

“There is a psychological hurdle that exists with some people because you worry about outliving your money, inflation, high healthcare costs, sequence of return risk or something coming out of left field.”

This also speaks to me.

It will be interesting to see how I combat these fears as my wife enters retirement next month and I consider retirement myself from current part-time work in 2026. Lack of a steady paycheque will be new territory to us.

Things we are considering for our retirement income spending as early retirees at least:

  1. Be flexible with our spending. If markets are good/positive, we’ll consider spending more. If markets are unfavourable, then we’ll spend a bit less. Spending a bit less means cutting back on travel plans.
  2. Keep a cash wedge at all times. Any money needed for spending in the next 1-2 years will be maintained in cash/cash equivalents. This way, when market corrections happen that I can’t see coming, we are ready to cover spending in advance.
  3. While we don’t budget (I recently wrote about that) we do track our spending and we’ll continue to do so. This will ensure we are spending money on things we value and/or are aligned to our values.

Retirement will be uncharted waters for us. My wife begins her journey next month. Our psychological and emotional hurdles when it comes to spending money without two steady paycheques will begin very soon: it will interesting to see and feel how we manage that.

I’ll keep you posted.

Other than 1, 2, 3 above, what other advice do you have for me? Words of wisdom from folks that have been there, done that?

More Weekend Reading – Related to the The 2% Retirement Rule

Ben’s post and my reflections of it remind me of this older but goodie post from Mr. Money Mustache about retirement income planning with a fixed chunk of money. Continue Reading…

5 Steps to a Successful Retirement Investment Plan

Build a retirement investment plan more successfully when you focus on tried and true ways of saving, like using an RRSP and a RRIF, among other strategies

TSInetwork.ca

Instead of taking on extra risk, take the safer route to retirement planning. Save more now, work longer, or plan to spend less. Retirement leaves you with lots of free time, and filling it costs money.

But postponing retirement, or working part-time as long as you’re able, can pay off in higher current income, more contentment and greater long-term security.

Here are five retirement investment plan tips to help you prepare for a successful future.


1.) Turn frugality into a game as part of your retirement investment plan

Retirement income planning doesn’t have to be about moving money around. Sometimes it’s easier to live frugally. People who come from humble circumstances often develop a degree of both frugality and industriousness early in life.

It’s easy to let frugality evaporate in mid-life, when money becomes more plentiful. But some find that if they return to frugality later in life, it’s more fun than ever. It’s a little like taking pleasure from a game that you haven’t played since you were young.

Your enjoyment of, or distaste for, frugality is partly a matter of attitude. But that’s under your control. Don’t think of it as penny-pinching. Think of it as taking charge of a part of your life, so that more of your money goes to things you choose.

2.) Invest in a Registered Retirement Savings Plan (RRSP) as part of your retirement investment plan

RRSPs are a great way for investors to cut their tax bills and make more money from their retirement investing. RRSPs are a form of tax-deferred savings plan. RRSP contributions are tax deductible, and the investments grow tax-free. (Note that you can currently contribute up to 18% of your earned income from the previous year. March 1, 2025 is the deadline to contribute to an RRSP for the 2024 tax year.)

When you later begin withdrawing the funds from your RRSP, they are taxed as ordinary income.

If you want to pay less tax on dividends while you’re still working, investing in an RRSP is the way to go.

3.) Convert your RRSP to a RRIF at age 71 to get the maximum benefit

Convert your RRSP to a RRIF at age 71 to make sure that you get the maximum. RRIFs offer more flexibility and tax savings than annuities or a lump-sum withdrawal. And like an RRSP, a RRIF can hold a range of investments.

If you have one or more RRSPs (registered retirement savings plans), you’ll have to wind them up at the end of the year in which you turn 71. When you do, you’ll have three main retirement investing options: Continue Reading…

8 Effective Strategies for Managing Retirement Income and RMDs

Pexels photo by Marcus Aurelius

Retirement income management and Required Minimum Distributions (RMDs) can be complex topics for many Americans. This article presents effective strategies to help readers navigate these financial challenges. Drawing on insights from financial experts, the following tips offer practical approaches to optimize retirement income and manage RMDs efficiently.

  • Purchase Annuity for Guaranteed Retirement Income
  • Leverage Qualified Charitable Distributions for RMDs
  • Optimize Asset Location for Tax-Efficient RMDs
  • Consider Annuities for Steady Retirement Income
  • Use Trusts to Manage RMDs Strategically
  • Convert to Roth During Market Downturns
  • Implement Bucket Approach with Beneficiary Designations
  • Start Home-Based Business to Offset RMDs

Purchase Annuity for Guaranteed Retirement Income

It is important to always consider broader planning needs, but one strategy that can be useful for generating retirement income and managing required minimum distributions (RMDs) is purchasing an annuity. This annuity would be purchased within an IRA and would create a level stream of guaranteed income for the rest of one’s retirement. This will not only satisfy one’s RMDs, but it can also lower taxes by stretching income across many years. In particular, it could help avoid large, irregular distributions that might push one into higher tax brackets. — Aaron Brask, Retirement planner, Aaron Brask Capital LLC

Leverage Qualified Charitable Distributions for RMDs

The obvious choice is to find a part-time job that aligns with your passion. This way, you can generate income and get paid to enjoy your favorite hobby. For example, if you love golfing, getting a part-time job at a golf course may give you discounts or even free games.

As far as managing RMDs, the amount that you must distribute is not determined by your income. It is based on the value of your Traditional IRA at the end of the year and the IRS Uniform Lifetime Table or Joint Life and Last Survivor Table.

This doesn’t include Roth IRAs. There are no RMDs in these accounts.

The best way to manage the increase in income, which can lower benefits such as Social Security or Medicare Part B (which are based on annual income), is to leverage Qualified Charitable Distributions (QCDs) for those who are philanthropic or give to a 501(c)(3) religious institution such as tithing.

When you reach the age to take RMDs, you can directly give to your favorite charity without incurring the tax implication or the increase in income that comes with RMD distributions. In 2025, you can donate up to US$108,000.

This will eliminate the RMD from being counted in your gross income and, at the same time, qualify for satisfying your annual distribution requirement.

I think this is useful because their favorite cause still receives donations, they satisfy their RMD, and they don’t have to pay the taxes up to that amount.

One thing I love about it is that you can make as many QCDs as you wish during the year as long as the total doesn’t exceed the threshold. — Alajahwon Ridgeway, Owner, A.B. Ridgeway Wealth Management, LLC

Optimize Asset Location for Tax-Efficient RMDs

After 15+ years managing corporate finances and helping businesses with cash flow optimization, I’ve seen how asset location strategy can be a game-changer for Required Minimum Distribution (RMD) management. The approach involves strategically placing different types of investments across taxable, tax-deferred, and tax-free accounts to minimize the tax impact when RMDs hit.

I worked with a client in the software technology space who had accumulated significant wealth through stock options and 401(k) contributions. We repositioned his bond holdings and REITs into his traditional IRA while moving growth stocks to his Roth accounts. When his RMDs started, he was pulling from bond interest and dividend income rather than forcing the sale of appreciating assets.

The key insight from my Financial Planning and Analysis (FP&A) background is treating this like portfolio optimization: you’re maximizing after-tax income rather than pre-tax returns. His RMD tax bill dropped by 18% because we were distributing lower-growth, income-generating assets instead of his high-performing tech stocks.

This works especially well for anyone with diverse investment types across multiple account structures. The planning needs to start at least 5-7 years before RMDs begin, but the tax savings compound significantly over time. — Michael J. Spitz, Principal, SPITZ CPA

Consider Annuities for Steady Retirement Income

Although annuities are often a source of debate and critique, they are still a functional and conservative way to generate income in retirement. If set up early enough, the steady income can often account for Required Minimum Distributions (RMDs) across all Individual Retirement Account (IRA) assets since the withdrawal rates are higher than the often quoted 4-4.5%. — Pedro Silva, Financial Advisor, Apex Investment Group, LLC

Use Trusts to Manage RMDs Strategically

After 25 years of helping clients navigate estate planning and witnessing countless families deal with Required Minimum Distribution (RMD) challenges, I’ve discovered the most effective strategy: creating an offshore Asset Protection Trust that feeds into a domestic charitable remainder trust for your RMDs. While this may sound complex, it’s incredibly powerful for the right situation.

Here’s how it works: I had a client with US$2.3 million in retirement accounts who was facing substantial RMDs that would push him into the highest tax brackets. We transferred a portion of his Individual Retirement Account (IRA) into a charitable remainder trust, which allowed him to take his RMDs as annuity payments over 20 years at a much lower effective tax rate. The added benefit? The remainder goes to charity, providing him with immediate tax deductions that offset other income. Continue Reading…