Decumulate & Downsize

Most of your investing life you and your adviser (if you have one) are focused on wealth accumulation. But, we tend to forget, eventually the whole idea of this long process of delayed gratification is to actually spend this money! That’s decumulation as opposed to wealth accumulation. This stage may also involve downsizing from larger homes to smaller ones or condos, moving to the country or otherwise simplifying your life and jettisoning possessions that may tie you down.

Dogs of the TSX Dividend Stock Picks

By Kyle Prevost, MillionDollar Journey

Special to Financial Independence Hub

I want to make it clear that the Dogs of the TSX is not something that I created. In fact, it’s actually an American idea. Michael B. O’Higgins wrote a book called the Dogs of the Dow back in 1991, and the idea was later adapted to the Canadian market. I first came across the “Dogs” method of stock picking when MoneySaver magazine started a column titled BTTSX – short for Beating the TSX – dividend stock strategy. (Click here to skip directly to my 2026 picks).

The theory behind the Dogs of the TSX strategy is to look for solid cash-flow-positive stocks that have fallen out of favour for one reason or another. In other words, you’re looking to take advantage of short-term market inefficiency when it comes to the pricing of blue-chip Canadian stocks. A low price and a high dividend results in a high dividend yield.

The chart below illustrates the total return (dividends plus price capital gains) versus the TSX 60 benchmark over the years. Looking at 2025, our Dogs of the TSX portfolio of 10 stocks was very similar to the overall TSX 60 index. In fact, the average return lead that the BTTSX strategy has over 3- and 5-year periods is fairly minor. That said, when we look out over the longer terms, we see consistent outperformance in the range of 2-3% per year.
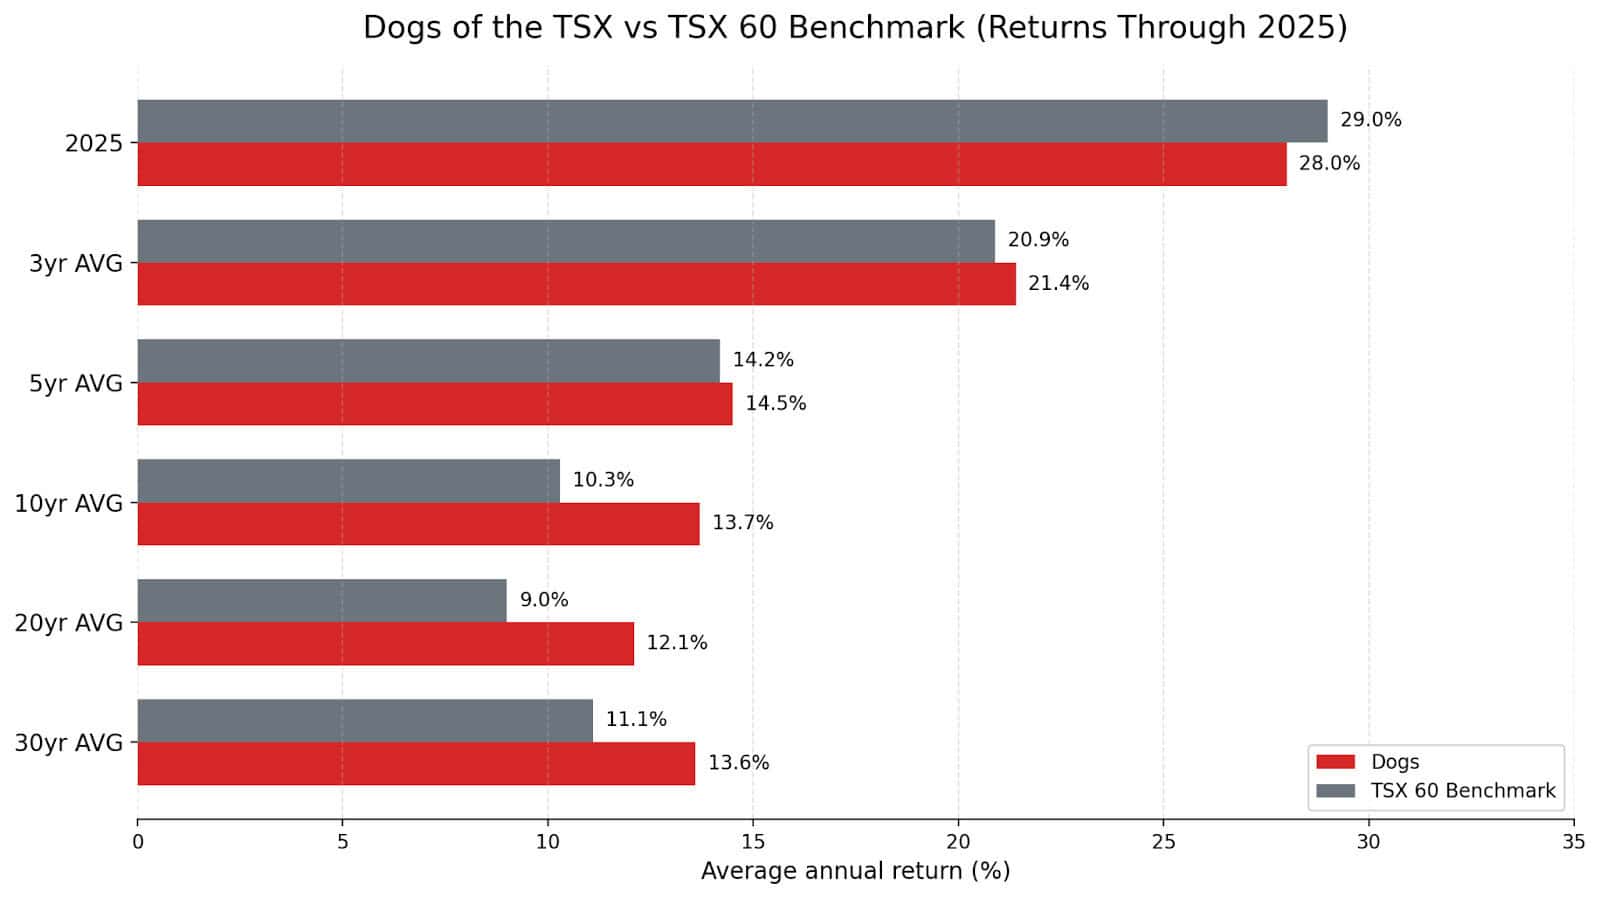
dogs of tsx vs benchmark2025

If you had $100,000 invested 30 years ago, the constant difference in compounding would have left you about $2 million richer today had you followed the Dogs of the TSX BTTSX strategy.

When we look back over the last year, the banks had a great year, and the telecommunications companies continued to get beat up. Consequently, we’re going to lose TD off of the list this year (its share price has finally caught up to its dividend payout).

In its pure original form, the Dogs the TSX strategy simply involved ranking the companies in the Toronto Stock Exchange 60 index (aka: TSX 60) by their dividend yield. The highest yield gets the top spot. Then you simply invest equal amounts in all top ten dividend yield stocks.

The idea is that investing in companies that have relatively high free cash flow – but relatively low share prices – is an excellent way to systemically outperform the broader market. No need to pick stock winners with any sort of fancy algorithm – just choose dividend stocks that are out of favour and consequently have high yields.

The average yield for the stocks making the 2026 Dogs of the TSX is about 5.26%. That’s down about 1% from last year – showing that valuations on these companies have raced ahead of their free cash flow and dividend payouts. (In theory, it could also be the case that these companies cut their dividends, but since only BCE did that, we can eliminate that theory.)

In my own implementation of the BTTSX strategy I often eliminate Real Estate Investment Trusts (REITs), and any stocks that have cut dividends OR have insanely high payout ratios (foreshadowing a future dividend cut). Those rules helped me avoid the Algonquin disaster in years past. I didn’t trim much of my BCE holdings before the cut, and I have to admit that I’m getting nervous about Telus: but haven’t pulled the trigger yet.

You’ll notice that my Dividend Dogs of the TSX list has a lot in common with my Best Canadian Dividend Stocks list that I update monthly. There’s obviously a lot of overlap in selecting value-driven, stable, Canadian company stocks.

Top Canadian Dogs of the TSX Pick for 2026: Emera (EMA)

My 2024 and 2025 Dogs of the TSX picks were identical to one another: Power Corp (POW).

While I looked pretty average in January last year, I look pretty darn smart today! That’s because Power Corp saw a total return of over 75% last year!!

In fact, the share price has done so well, that it has outpaced the dividend, and dropped POW right off the BTTSX list for 2026. The biggest driver was Great-West Life’s robust earnings. On top of that, IGM has quietly stabilized its asset base, and Wealthsimple continues to expand its footprint, with more rumours swirling about that Schedule 1 bank licence approval. Investors are finally pricing in the fact that Power Corp isn’t just a stodgy old financial holding company. It’s a well-run, diversified business with growth levers in both traditional finance and the fintech space.

The other stock I highlighted as a Dogs of the TSX stock to watch was TD Bank: and again, TD did so well (total return of about 70%!) that it’s not on the list this year!

It is nearly impossible to duplicate those results going forward. Those two picks both hit the perfect tailwind, and while I believed they were significantly undervalued 12 months ago, I would have told you that you were crazy if you said they’d have total returns of more than 50%, nevermind 70%!

Now, I’m not nearly as bullish on the overall market going into 2026 as I was in 2025. I don’t see any screaming “buy now” deals out there. That’s why my 2026 Dogs of the TSX pick is Emera.

It’s definitely not a stock that’s going to light up Reddit boards. What it is, is a regulated utility with a high starting yield, visible growth, and a US-expanding business mix that I think the market is still undervaluing.

At its core, Emera is a regulated electric and gas utility operator. More than 90% of its earnings come from regulated sources, and roughly 96% of its assets sit inside rate-regulated frameworks. That price stability is exactly what you want when you’re building a dividend-focused portfolio in a market that feels a bit stretched.

Emera operates across Canada, the U.S., and parts of the Caribbean, but the business is much simpler than the geographic footprint suggests.

The short version is this: Florida’s data center growth is the story. Canada is secondary. Everything else is noise.

Emera’s crown jewel is Tampa Electric, which sits under its TECO Energy subsidiary in Florida. That operation benefits from population growth, constructive regulation, and a steady stream of capital investment tied to grid hardening, electrification, and storm resilience. If you believe Florida continues to grow and data centers continue to put pressure on electrical grids (and all signs point that way), Emera has positioned itself very well.

One of the reasons Emera stands out to me right now is management’s five-year, $20 billion capital plan, announced late in 2025. This isn’t vague guidance. It’s a detailed roadmap that extends 7–8% consolidated rate base growth through 2030, with nearly 80% of that capital earmarked for Florida.

That’s meaningful growth for a regulated utility. And importantly, it’s growth that regulators expect and allow utilities to earn returns on.

Canadian assets (which are mostly through Nova Scotia Power) do introduce some political and regulatory friction. But when I look at where Emera is allocating capital, it’s clear management understands where the best risk-adjusted returns are coming from. The payout ratio is pretty darn high, and the balance sheet carries too much debt for my liking. That said, with interest rates coming down in the US, and regulations coming off the books, I like the short- and medium-term prospects.

In a market where many stocks feel priced for perfection, Emera feels priced for caution. That’s what I’m looking for in 2026.

June 2026 Update: So far so good, Emera. It’s up about 7% on the year, which means that it is slightly outpacing the overall TSX 60 index. When you consider that its dividend is higher than that of a TSX 60 ETF, the gap opens up a bit more. American assets and earnings continue to perform well (as I figured they would). So while it’s not performing as well as my Toromount Industries Dividend King pick, or as well as Power Corp (which just continues to power on after last year’s incredible run, up 13% so far in 2026), Emera continues to add steady dividends and capital gains to my portfolio.

One thing to note in regards to Power Corp (which still holds a prominent place in my TSX Dogs Portfolio after its big move last year) is that its Wealthsimple subsidiary continues to post explosive growth. While I don’t at all like the direction the company is going from a user perspective, it is undeniably finding new ways to monetize its young customer base. The company recently made waves by saying it was going to be one of the first Canadian companies to bring predictive markets (think online betting like Kalshi or Polymarket down in the States) to Canada. If casinos are a license to print money, online casinos are a license to print money right across an entire country!

Visit DSR & Get Our Exclusive Discount

Dogs of the TSX Dividend Stock Strategy Implementation

Here is the step by step procedure of how this strategy is implemented: Continue Reading…
Connectively experts on the classic 4% Rule and enhancements

William Bengen (LinkedIn)

Of all the Retirement Rules of Thumb discussed over the decades I’ve spent writing about investing and Retirement, few are more ubiquitous than financial planner William Bengen’s famous 4% Rule, which is his rough estimate of the annual percentage of a portfolio that can safely be withdrawn each year without causing your retirement nest egg to run out of money in old age (adjusted for inflation.) While he has more recently updated it to a slightly higher 4.7%, the “Rule” continues to fascinate and sometimes provoke financial advisors, retirement gurus and media pundits.

Indeed, the past weekend in the Motley Fool Hidden Gems Investing podcast, regular TMF Retirement contributor Robert Brokamp rebroadcast an earlier interview with Bengen, titled “The Father of the 4% Rule says Retirees can take out much more.” 

I have written on this topic more than once; most recently late last year in my MoneySense Retired Money column: Experts opine on various tweaks to Bengen’s famous 4% Rule.

Below, we asked various North American advisors, business owners and other experts to weigh in via Linked In and Connectively (formerly Featured.)

Here’s how the question was posed earlier this month on Connectively:

What is your view of William Bengen’s famous 4% Rule, which he seems to have adjusted up to about 4.7%? Are either of these realistic percentage gains, or are they too optimistic or too pessimistic? If you have clients of varying ages (from Gen Z to retired Boomers), did any religiously cleave to this Rule or is it just a starting point around which specific investment objectives were overlaid?

As usual, we have only lightly edited the responses which appear more or less intact, complete with author picture, title and links to their respective web sites.  The subheadings are either direct quotes from their input (indicated in quotation marks) or slightly edited variations of quotes.

“The Rule works as a conversation starter, not a finish line.”

Bengen’s rule is a solid anchor, not a contract. I’ve worked with retired clients who treated 4% as gospel and ended up leaving significant money on the table because they were terrified to spend: even when markets had doubled their portfolio.

The honest answer is that the “right” number depends entirely on sequence-of-returns risk, tax drag, and spending flexibility. A Boomer pulling from a traditional IRA faces a very different math than a Gen Z client with decades of Roth compounding ahead. Same percentage, completely different outcome.

Where I’ve seen the rule actually help is as a conversation starter, not a finish line. One business owner client near Crown Point was fixated on hitting a magic retirement number. When we layered in tax-efficient withdrawal sequencing — mixing taxable, traditional, and Roth accounts — their sustainable spending rate shifted meaningfully without touching the portfolio risk profile at all.

The Bengen rule also assumes relatively static spending, which almost no one has. Clients in their early retirement years typically spend more on travel and experiences, then spending drops mid-retirement, then healthcare costs spike late. A single fixed percentage ignores that entire curve. A living financial plan accounts for it. — Daniel Delaney, Owner, Seek & Find Financial

 A useful mental anchor but don’t treat it like gospel

The 4% Rule is a useful mental anchor, but treating it as gospel is like using a map from 1994 to navigate a city that’s been rebuilt three times since. Bengen’s original research was groundbreaking for its era. It gave people a simple number to hold on to. But the world it modeled — steady bond yields, predictable inflation corridors, a relatively stable geopolitical backdrop — that world doesn’t fully exist anymore.

Here’s how I think about it. The 4% Rule assumes you’re a passive participant in your own financial life. You retire, you draw down, you hope the math holds for 30 years. That framing made sense when most people had one career, one pension, and one plan. Today, the most financially resilient people I know, from Gen Z creators to semi-retired Boomers, don’t think in terms of a single withdrawal rate. They think in terms of optionality.

I’ll give you a real example. A former VC CFO I spoke with last year told me he stopped thinking about the 4% Rule entirely when he realized his “retirement” would include three or four income-generating projects running simultaneously, most of them enabled by AI tools that didn’t exist five years ago. His withdrawal rate fluctuates between 2% and 6% depending on what’s producing cash flow in a given quarter. The rule became irrelevant because his income never fully turned off.

Bengen adjusting to 4.7% reflects updated data, but it still operates inside the old paradigm: accumulate, then deplete. For younger generations, the line between accumulation and distribution is blurring completely. A 28-year-old building a side business with AI isn’t thinking about safe withdrawal rates. They’re thinking about how to make their capital work alongside earned income indefinitely.

So is 4% too optimistic or pessimistic? Neither. It’s just incomplete. The better question isn’t “what percentage can I safely withdraw?” It’s “how do I build a life where I’m never fully dependent on withdrawals alone?” That reframe changes everything. — Runbo Li, Cofounder and CEO, Magic Hour AI

GenZ and Millennials ignore it completely

I view the 4% Rule as more of an idea to explore, not something carved in stone, and the 4.7% update is essentially Bengen coming clean about what many of us already say: One number will not make it through intact after meeting real-world markets, tax brackets, and spending needs. It is those Boomers taking 4% as their gospel and panic selling in a tough year or, worse, never adjusting for a tough sequence of returns early on during retirement where I have seen people make their biggest mistakes. On the other hand, my Gen Z and Millennial audience members ignore it completely because they are decades away, and they have much better control over income right now through negotiation or side work such as surveys and focus groups than by worrying about a withdrawal rate that is years away from being used. In my opinion, use 4% as a quick and dirty check and build yourself a withdrawal range based on your own individual circumstances. — Scott Brown, Founder, MintWit

“Real life rarely matches the assumptions behind any single retirement rule.”

From my perspective, the 4% Rule has always been more useful as a planning framework than a guarantee. Whether someone uses the original 4% guideline or William Bengen’s later research suggesting that a higher starting withdrawal rate may have been sustainable under certain historical conditions, I don’t think either figure should be treated as universally correct.

I’ve worked with business owners and professionals at different stages of their careers, and one thing stands out: real life rarely matches the assumptions behind any single retirement rule. Markets change, spending isn’t static, people retire at different ages, and unexpected expenses inevitably arise.

That’s why I encourage people to use the rule as a starting point rather than a destination.

For younger professionals, including many entrepreneurs, the conversation is usually less about withdrawal rates and more about building assets, increasing income, and creating flexibility. For those nearing retirement, the focus shifts toward sustainable income, but I still don’t recommend relying on one fixed percentage alone.

I’ve also noticed that financially disciplined people tend to adjust their withdrawals based on market conditions instead of following the exact same rate every year. They’re willing to spend a little less after a difficult market and a little more when their portfolio performs well.

As a founder, I appreciate simple financial frameworks because they help people begin planning, but they shouldn’t replace individualized decision-making.

If I were advising someone, I’d say the 4% Rule — or even 4.7% — is a reasonable benchmark, not a promise. The more important questions are: How long does your money need to last? How much flexibility do you have in your spending? What’s your investment mix, and how comfortable are you with market volatility?

In my experience, successful retirement planning isn’t about finding the perfect withdrawal percentage. It’s about creating a strategy that can adapt as your life and the markets inevitably change. — Max Shak, Founder/CEO, nerD AI

The Rule is “a stress-test starting point, not a spending command.”

The first clarification is that 4% or 4.7% is a withdrawal rate, not an expected investment gain. Under the original approach, a retiree withdraws that percentage of the starting portfolio in year one and then adjusts the dollar amount for inflation.

For a $1 million portfolio, the difference between 4% and 4.7% is $7,000 in the first year: $40,000 versus $47,000. That difference may look modest, but it becomes important when retirement begins before a major market decline or period of high inflation.

I treat either figure as a stress-test starting point, not a spending command. The appropriate plan depends on retirement length, taxes, fees, portfolio composition, pension or Social Security income, essential spending and the retiree’s willingness to reduce withdrawals after weak markets. A person retiring in their forties should not automatically use the same assumption as someone retiring at seventy with reliable pension income.

I do not have U.S. retirement-advisory clients, but my finance approach is to model several scenarios rather than rely religiously on one percentage. The safer plan is usually one that protects essential spending, keeps a separate reserve and allows discretionary withdrawals to adjust when markets or inflation behave badly. — Cem Oner, Founder / Finance & Public Data Publisher, hesapcebimde.com

If you are underweight equities or neglect rebalancing, “a fixed 4 per cent can be too optimistic; with disciplined equity exposure and regular rebalancing it is more attainable.”

I view William Bengen’s 4% rule as a useful planning baseline but not a fixed rule for every retiree. It provides a clear starting point for estimating sustainable withdrawals, but its realism depends on factors I see often in client portfolios, such as asset allocation, rebalancing habits, and savings adequacy. When investors are underweight equities or neglect rebalancing, a fixed 4 percent can be too optimistic; with disciplined equity exposure and regular rebalancing it is more attainable. Very few clients strictly adhere to a single percentage in my experience. Instead, the rule is typically used as an initial benchmark onto which specific investment objectives and cash flow needs are overlaid. I therefore advise starting with the 4 percent figure, conducting a full portfolio audit, and automating contributions and rebalancing to align the plan with individual goals. — Amir Husen, Content Writer, SEO Specialist & Associate, ICS Legal

Financial Advice should not be based on a single Rate of Return

Looking back at my over two decades of experience working with financial companies to boost their Internet presence, one thing I’ve learned is that guidelines like the 4% rule are so well-known because they’re easy to remember. The problem here is that most people confuse headlines or popular guidelines as a reasonable solution for their retirement. Whether they’re talking about 4%, or William Bengen’s idea around 4.7%, in some circumstances, I would consider those as opening lines of discussion.

Highly trusted financial institutions do not base their advice on a single rate of return. Financial institutions provide interpretation of the assumptions made regarding rate of return and customize advice according to retirement age, required income, taxes, health care expenses and other sources of income.

From my perspective, good financial advice doesn’t make any promises about guarantees. This allows one to realize the reasons why a certain rule may be wrong and to start a conversation with an expert in this field. A notable percentage may help clarify a complex idea, but good retirement strategies are always based on flexibility. — Derek Iwasiuk, Co-owner, Director of marketing, Searchtides

It all depends on Sequence of Returns, which is out of your control

The 4% Rule works fine as a starting number. That’s why most people accept it as a default. But you shouldn’t consider it a guarantee. Just guidance, not prescriptive one. The rule works only within the confines of the assumptions used to create it. Bengen wasn’t using an average of the stock and bond market returns. He used one specific period in the market and one very particular mix of assets.

The 4.7% rule is similar, only it uses slightly different numbers. When looking to live off your investments for the rest of your life, can you really go wrong using either number? It depends on the sequence of returns, which is completely out of your control. Continue Reading…

Planning major Purchases during Retirement

Planning major purchases during retirement requires aligning income timing, market conditions, and long-term financial stability to support lasting flexibility.

Image courtesy Adobe Stock/peopleimages.com

By Dan Coconate

Special to Financial Independence Hub

Retirement changes how income flows, which means planning major purchases during retirement requires a more deliberate approach than it did during peak earning years. Instead of relying on a steady salary, retirees draw from savings and structured income sources, so each major expense must fit within a longer financial horizon.

Careful planning allows individuals to move forward with confidence while preserving the stability that supports future years, particularly when financial decisions must stretch across an extended retirement timeline.

Understanding how Cash Flow Evolves

Income arrives differently after retirement, and each source carries its own implications when funding a large purchase. Withdrawals from registered accounts may affect taxes, while selling investments can alter long-term growth potential, which makes timing a central consideration.

When retirees map out funding strategies before committing, they gain a clearer sense of how the purchase will influence future income. That preparation reduces the risk of decisions that feel manageable in the moment, but creates pressure later, especially when income must stretch across decades and support both planned and unplanned expenses.

Weighing Lifestyle Value with Financial Reality

Major purchases reflect personal priorities, whether that involves extended travel or a second property that supports time with family. These decisions carry meaning, yet they still require a disciplined evaluation of ongoing costs and expected use.

In the case of recreational real estate, retirees may notice that waterfront properties appeal to vacation home buyers because of their setting and long-term desirability. That perspective fits within a broader assessment, since ownership involves upkeep and financial commitments that must align with retirement goals and long-term affordability, particularly when property ownership extends beyond seasonal use.

Considering Market Conditions before Committing

Financial markets influence both the cost of large purchases and the resources used to fund them, which makes timing an important part of the decision. Selling assets during a strong market period may reduce pressure on a portfolio, while moving forward during a downturn can create a strain that lingers.

A disciplined timing strategy allows retirees to act when conditions support the purchase. Maintaining that discipline supports a more stable financial path, even as markets fluctuate, and reinforces the value of patience when making high-impact financial decisions that cannot be easily reversed or adjusted once completed.

Preserving Flexibility for Future Needs

Large purchases should not restrict the ability to respond to unexpected developments, since retirement still brings changes that require financial attention. Healthcare needs and property repairs can emerge without warning, making flexibility a key part of any plan. Continue Reading…

How moving to a Lower Cost-of-Living Area can Accelerate your FI Timeline

Image courtesy Pexels

By Dan Parks

Special to Financial Independence Hub

The modern worker faces rapid inflation in housing and consumer prices. This results in reduced savings and financial insecurity. As a result, the Financial Independence/Retire Early (FIRE) movement has garnered many loyal followers. Individuals are saving aggressively and investing wisely to retire early and have enough money to cover living expenses.

Understanding Financial Independence

Financial Independence is achieved when an individual can cover daily expenses without having to work. One of the biggest ones is renting or owning a home. In 2023, more than 21 million renters spent over 30% of their income on housing.

Since housing consumes a large share of income, people are looking to move to areas with lower rents. This salary-to-housing ratio is even more skewed in high-cost urban areas, where rent prices are sky-high, such as in New York, Los Angeles and Chicago. There are plenty of other cities that provide the same energy while having a more affordable cost of living.

Moving to a Lower Cost-of-Living Area

There are plenty of things to consider before moving to cities with a lower cost of living:

Benefits

Geographic locations also directly impact living costs such as rent, food, utilities, transportation and healthcare. With lower expenses, individuals can afford more luxuries like dining out compared to when residing in high-cost cities. Individuals can lead more relaxed lives due to less financial stress. Other factors to improve one’s quality of life include access to nature, community amenities and smaller populations.

Reduced expenses due to a lower cost of living can accelerate savings over time, especially when directed to diverse investment accounts, retirement accounts and income-generating assets, helping individuals gain Financial Independence earlier.

Moving Tasks

Before deciding on new locations, people can create structured plans regarding moving expenses, new living costs and potential earnings. Employment rates, average salaries and cultural opportunities need to be researched and compared with their current lifestyles.

Housing and job searches should also be handled before the move. After moving, local communities, online forums and professional networks can help ease the transition into the new city. Financial goals should also be reassessed to reflect changes in income and expenses to maintain progress toward FIRE.

Sacrifices and Trade-offs

Since 2017, home purchases rose by 81%, while rent prices rose by 54% compared to a 43% increase in earnings. To further increase savings, people can downsize their living spaces or sacrifice proximity to major urban areas.

They might experience an initial discomfort with the change in lifestyle, but that will be outweighed by the potential long-term financial benefits. By assessing what to give up, professionals can gain more control over their finances and way of life. They can be more prepared for emergencies or other future situations.

5 Affordable U.S. Cities to Accelerate the Financial Independence Journey

1. Grand Rapids, Michigan

Grand Rapids, Michigan, can help individuals significantly reduce expenses due to the city’s growing economy and consistent job opportunities. They also don’t have to sacrifice lifestyle quality, as the Grand Rapids area is known for its wide range of outdoor activities, emerging art scene and friendly communities.

2. Austin, Texas

Austin, Texas, is a burgeoning tech hub with more affordable rents than in Silicon Valley and Seattle. Tech presence in Austin includes Apple, Tesla, Dell, AMD, Amazon, Google, IBM, Meta, Microsoft and Samsung, among others. Besides its tech scene, Austin has a vibrant music community and plenty of outdoor activities at Lady Bird Lake, Mount Bonnell and Barton Creek Greenbelt. The city also offers a distinct food scene, especially Texas barbecue and tacos.

3. Boise, Idaho

Boise is an ideal city to relocate to for individuals looking to save on living costs. The city offers stunning landscapes without breaking the bank on rent, making it perfect for families and young professionals alike. Residents have plenty of activities to explore in the city, including hiking, biking and skiing. It has a solid job market, a stable economy and plenty of amenities for different lifestyles. Boise also has top-rated schools with relatively lower utility and transportation costs.

4. Charlotte, North Carolina

Charlotte is growing as a major financial, healthcare and tech center, making it a great option for many young professionals. The city also has plenty of welcoming communities with diverse interests and backgrounds. The cost of living here is lower than in other ultra-urban cities, which makes day-to-day living and saving significantly more hassle-free. Residents can drive to the Blue Ridge Parkway for a relaxing weekend trip in the Great Smoky Mountains.

5. Richmond, Virginia

Richmond, Virginia, is great for those who are inspired by a place’s historical significance. It also offers significant modern growth, cost-of-living affordability and culture. The city has plenty of galleries, theaters and music venues for any art-loving individual. Community events and volunteer opportunities are plentiful.

Embracing a Strategic Move for Financial Freedom

The Financial Independence Retire Early movement is widely known. It encourages individuals to save more, invest in income-generating assets and retirement accounts to be able to retire earlier than the rest of the workforce.

Relocating to lower-cost cities is one of the most viable paths toward increased savings. There are plenty of cities with a vibrant energy, welcoming communities and plenty of activities. In the right locations, individuals can increase savings without sacrificing quality of life, but proper planning before moving is essential to achieving a fulfilling lifestyle.

Dan Parks is a senior writer at Modded.com. Based in Washington, D.C., Dan has a proven track record of distilling complex subjects into accessible narratives across various fields. His expertise in clear communication and meticulous research makes him a valuable contributor to discussions on personal finance and investment strategy, helping readers navigate intricate topics with ease. Dan is dedicated to providing readers with well-researched insights to foster financial literacy and independence.

The underestimated Power of Pensions

Adobe Stock Image, courtesy CAAT Pension Plan

By Anthony Damtsis

Special to Financial Independence Hub

Expectations of the future shape how we behave today, especially when it comes to planning for retirement. When people overestimate or underestimate where their retirement income will come from, it can affect how they save, how they plan, when they retire, and how financially secure they feel over time.

That sounds simple enough. But retirement has a way of making simple things complicated.

Recent research from CAAT Pension Plan shows a clear gap between what working Canadians expect retirement to look like and what retirees actually experience.

The retirement we picture

Nearly one in four working Canadians expect personal savings to be their primary source of income in retirement. In reality, only about one in seven retirees rely on personal savings as their primary source of income.

At the same time, working Canadians appear to underestimate the role of workplace pensions. Among working people with a pension, only 10% expect it to be their primary source of income in retirement. But among retirees with a pension, 23% say their pension is their primary income source.   Pensions are a foundational source of income for many. Retirees with pensions report approximately $2,750 more in average monthly household income than retirees without pensions.

For many Canadians, that is the difference between getting by and living well. Defined Benefit [DB] pensions can provide a predictable stream of retirement income, reduce the burden of managing investments alone, and help protect against the risk of savings running out.

This expectation gap matters because expectations are not harmless. If people expect personal savings to carry more significance than they realistically will, they may delay planning, undersave, or assume they will have more time to catch up later. That can increase the risk of outliving savings, delaying retirement, or becoming more dependent on public supports.

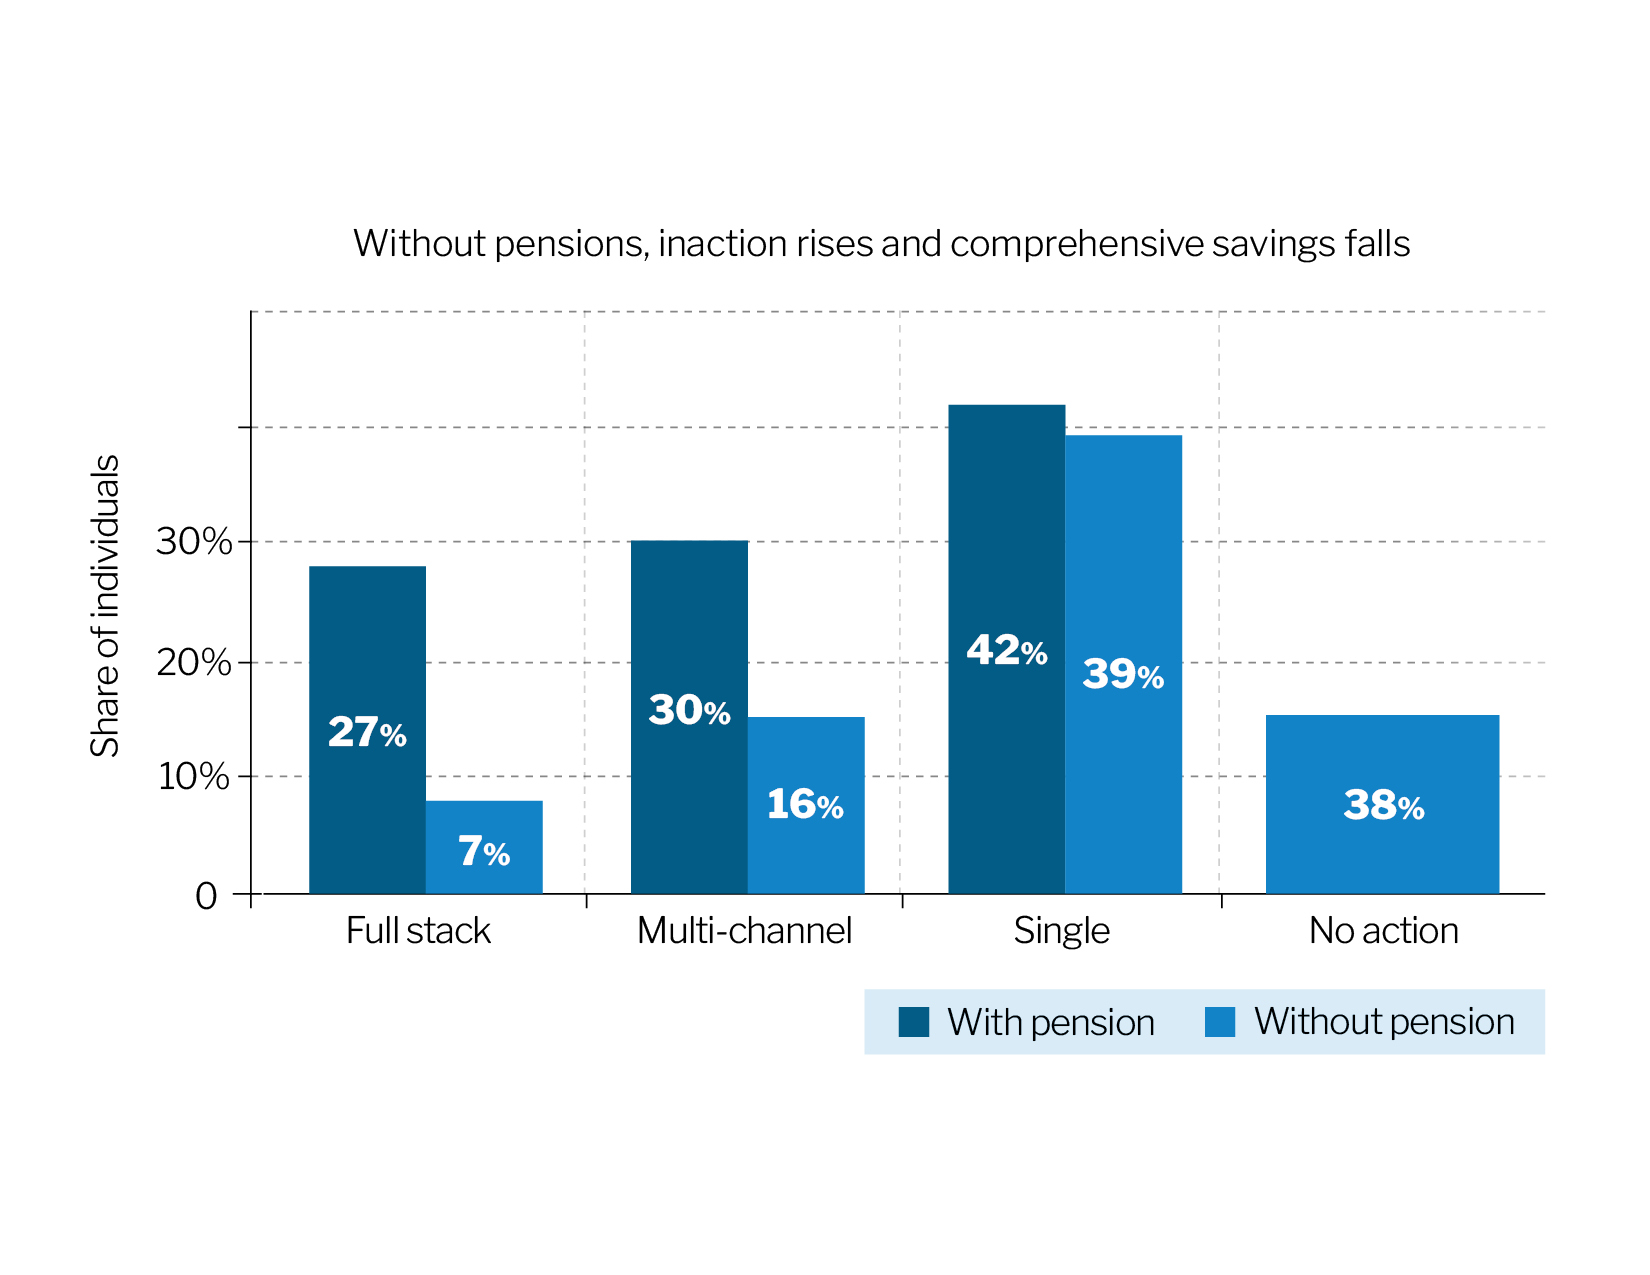
The reality today is that 38% of Canadians without a workplace pension report taking little or no action toward saving for retirement. Among Canadians with household income below $50,000, that figure rises to 60%.

This can show up as delayed retirement. For Canadians, the average ideal retirement age is 60, while the average expected retirement age is 67. For many people, there is a meaningful seven-year gap between the retirement they hope for and the retirement they think is realistic.

There is a quiet lesson in that gap. When people do not have a clear path to retirement, they do not always change their savings behaviour today. Sometimes they change their expectations about tomorrow.

The pension habit

This research challenges the idea that pensions crowd out personal saving. Savings habits are an important building block in creating predictable income in retirement. Pensions can act as a foundation for those habits because they make saving structured, automatic, and easier to sustain.

This matters because good financial behaviour is often less about willpower than design. If saving depends on making the right decision every month, life has plenty of opportunities to get in the way. A pension changes the architecture of the decision. It turns saving from something people have to repeatedly choose into something that happens more reliably in the background.

The research suggests this happens in the real world. Pension plan members are nearly four times more likely than non-pension plan participants to report using a full suite of retirement savings tools, such as TFSAs, RRSPs, and non-registered accounts. Specifically, 27% of pension members use a full suite of savings tools, compared with just 7% of those without a pension.

Canadians with workplace pensions are also more likely to use multiple savings approaches at the same time, 30% compared with 16% of those without a pension.

Access is the real barrier

Many Canadians want to save, but they do not always have access to the tools that make saving easier. Continue Reading…