Decumulate & Downsize

Most of your investing life you and your adviser (if you have one) are focused on wealth accumulation. But, we tend to forget, eventually the whole idea of this long process of delayed gratification is to actually spend this money! That’s decumulation as opposed to wealth accumulation. This stage may also involve downsizing from larger homes to smaller ones or condos, moving to the country or otherwise simplifying your life and jettisoning possessions that may tie you down.

HDIV: All-In-One Canadian Income & Growth ETF Turns 5 years old

Hamilton ETFs

By Hamilton ETFs

(Sponsor Blog)

Last month marked the fifth anniversary of the launch of the Hamilton Enhanced Canadian Covered Call ETF (HDIV), Canada’s very first modestly levered (or “enhanced”) covered call ETF, and there are many reasons to celebrate this marriage of income and growth strategy.

The idea for HDIV was born out of one question: can covered call ETFs be improved? Designed to provide higher monthly income, covered call ETFs have been a rapidly growing segment of the ETF market for several years, but the reality is the strategy does cap your potential upside in exchange for the tax-efficient income it provides.

We thought of a game-changing way to help mitigate this yield/return trade-off: add modest 25% leverage to generate higher monthly income and participate in more upside growth potential.

HDIV Growth and Performance

HDIV has grown to assets under management (AUM) of ~$1.8 billion since inception in July 2021, making it our second-largest ETF after the Hamilton Canadian Financials YIELD MAXIMIZER™ ETF (HMAX).

HDIV’s growth in assets has been impressive, and the fund has also delivered strong performance. Since inception, HDIV has delivered an annualized total return of 19.3%, outperforming the S&P/TSX 60 and the S&P 500 index over the same period[1].
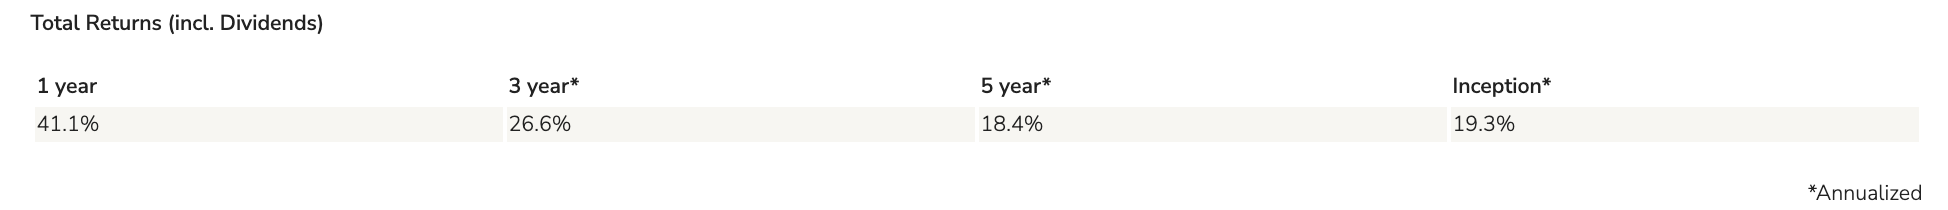
HDIV Performance Highlights:

  • Annualized total return (including dividends) of 19.3%, versus 15.2% for S&P/TSX 60 and 15.6% for S&P 500 (CAD).
  • Outperformed the S&P/TSX 60 in calendar years 2022, 2023, 2024 and 2025 by 3.7%, 1.8%, 2.1% and 4.7%, respectively[2].
  • 14 distribution increases for a total distribution increase of 64% since inception[3].
  • Attractive yield, currently 9.99% — versus 2.29% for S&P/TSX 60[4].
 

What does $100,000 invested in HDIV since day 1 look like?

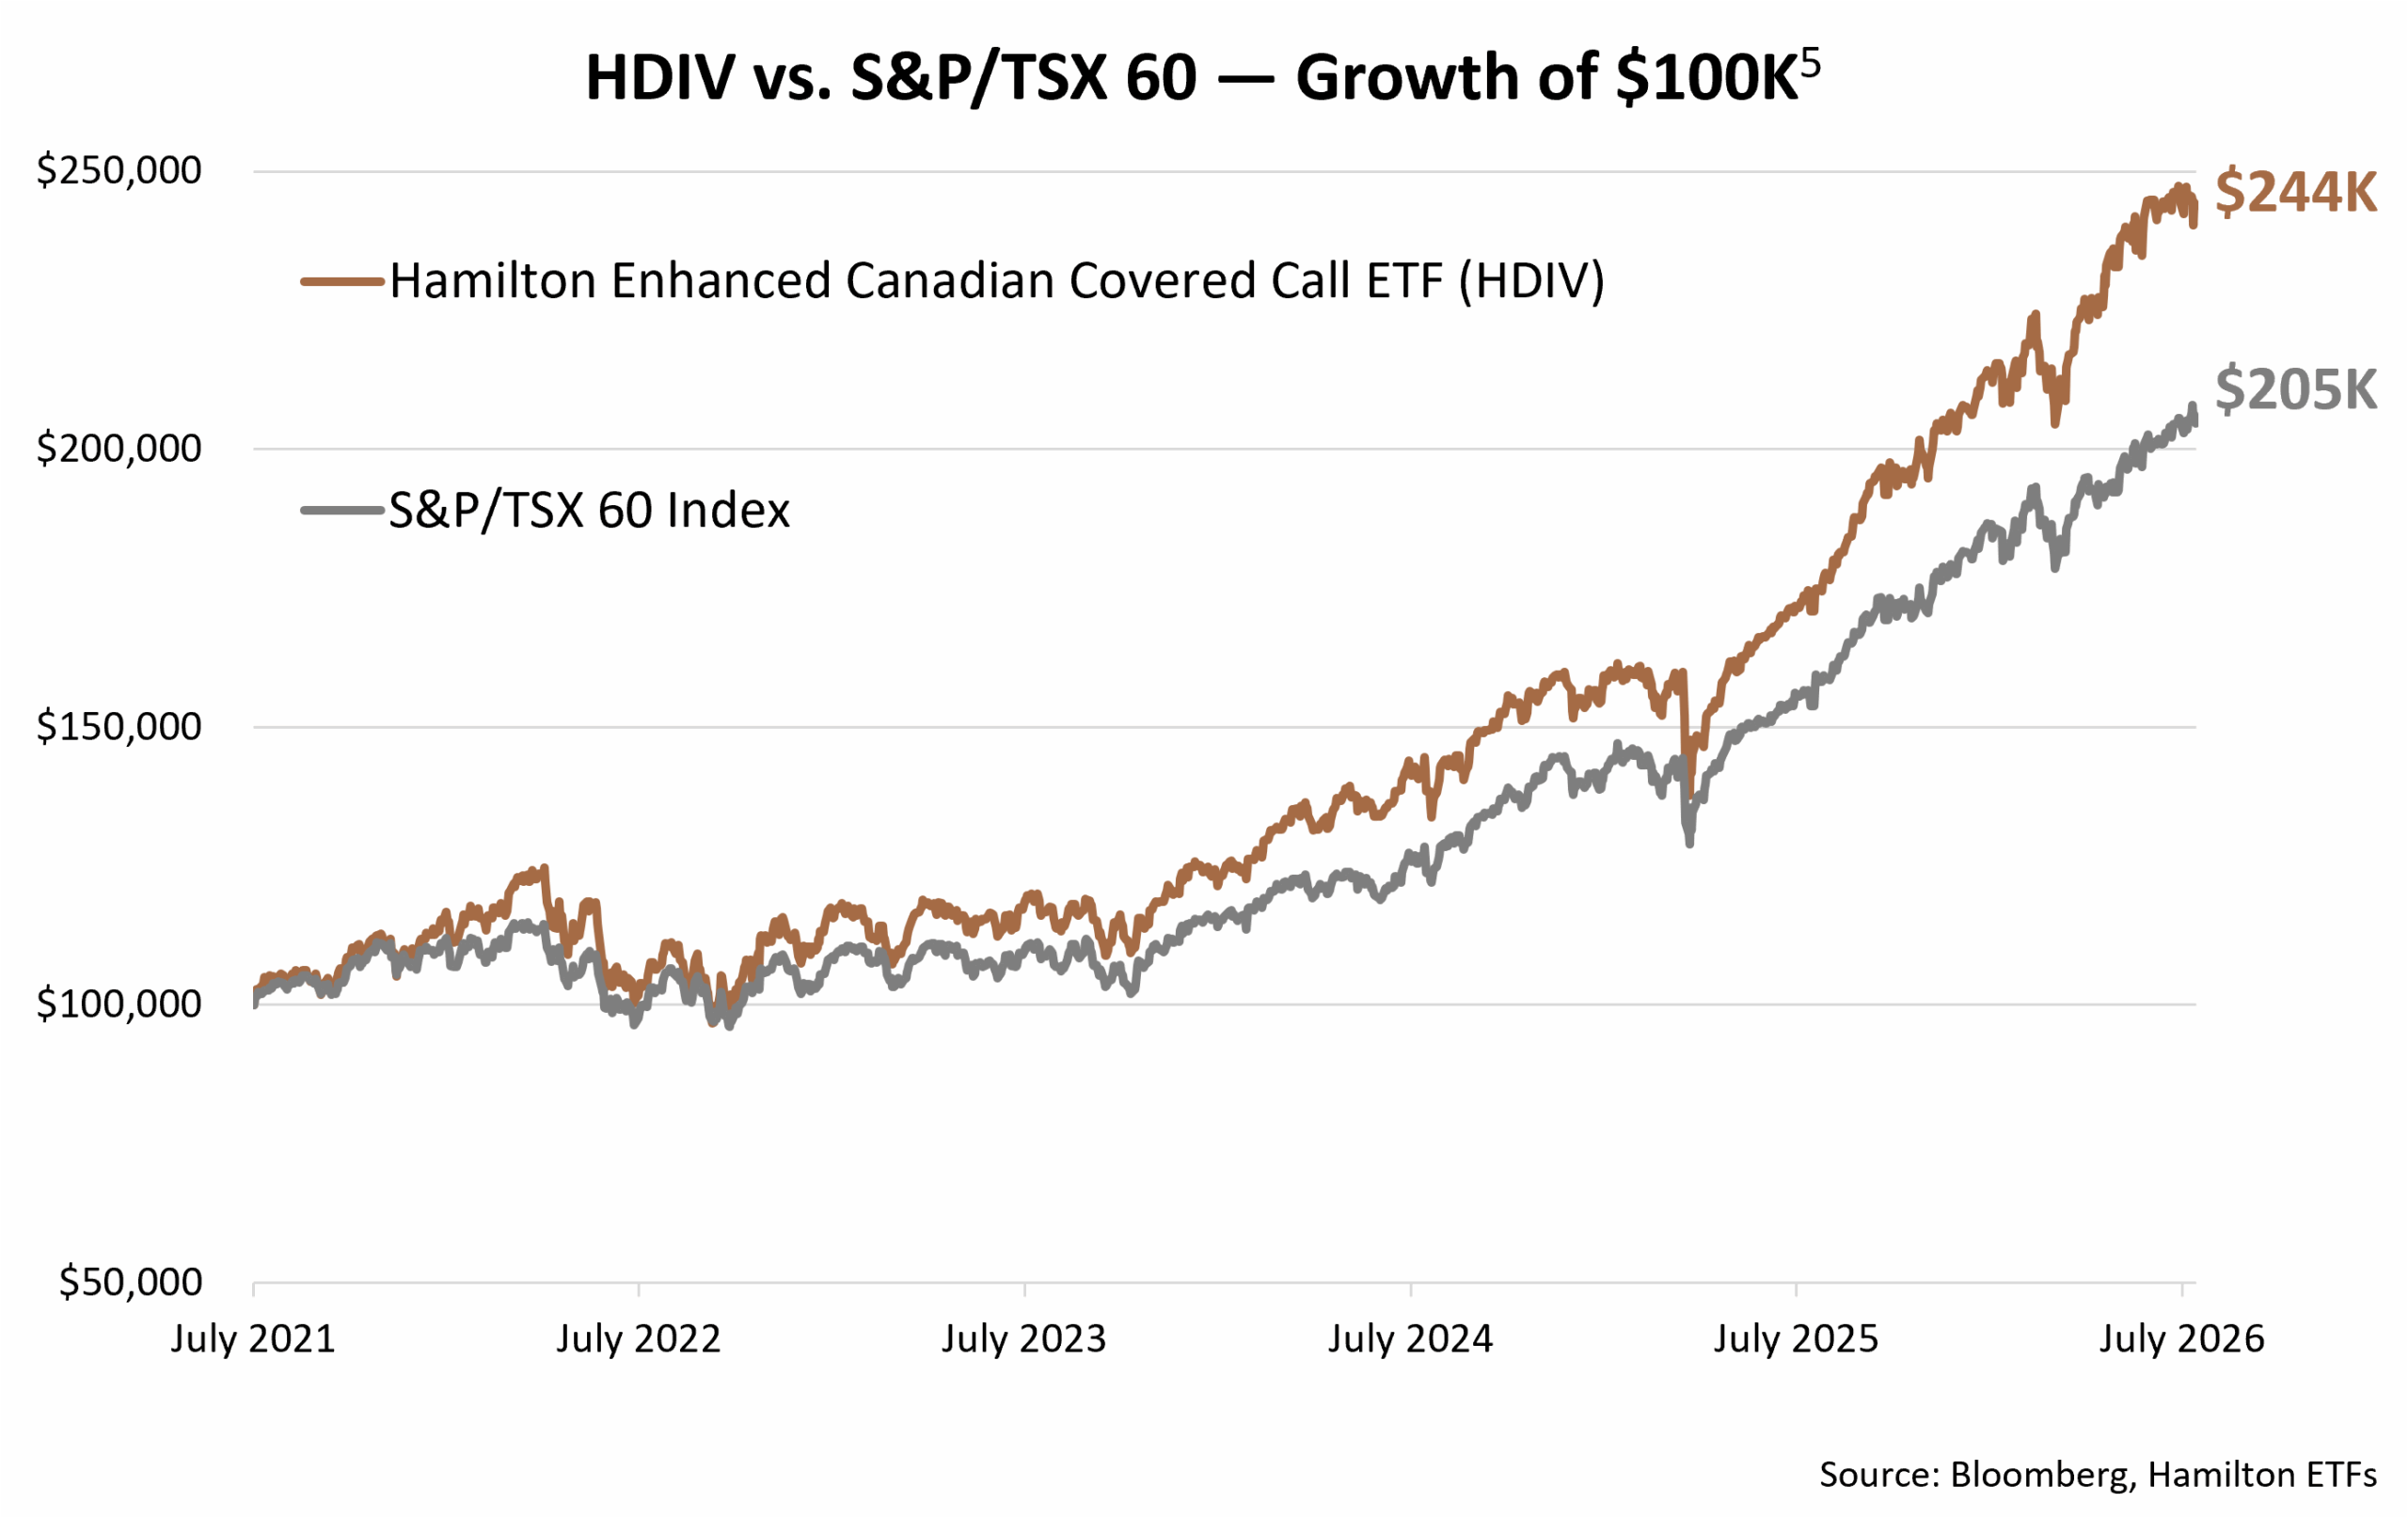
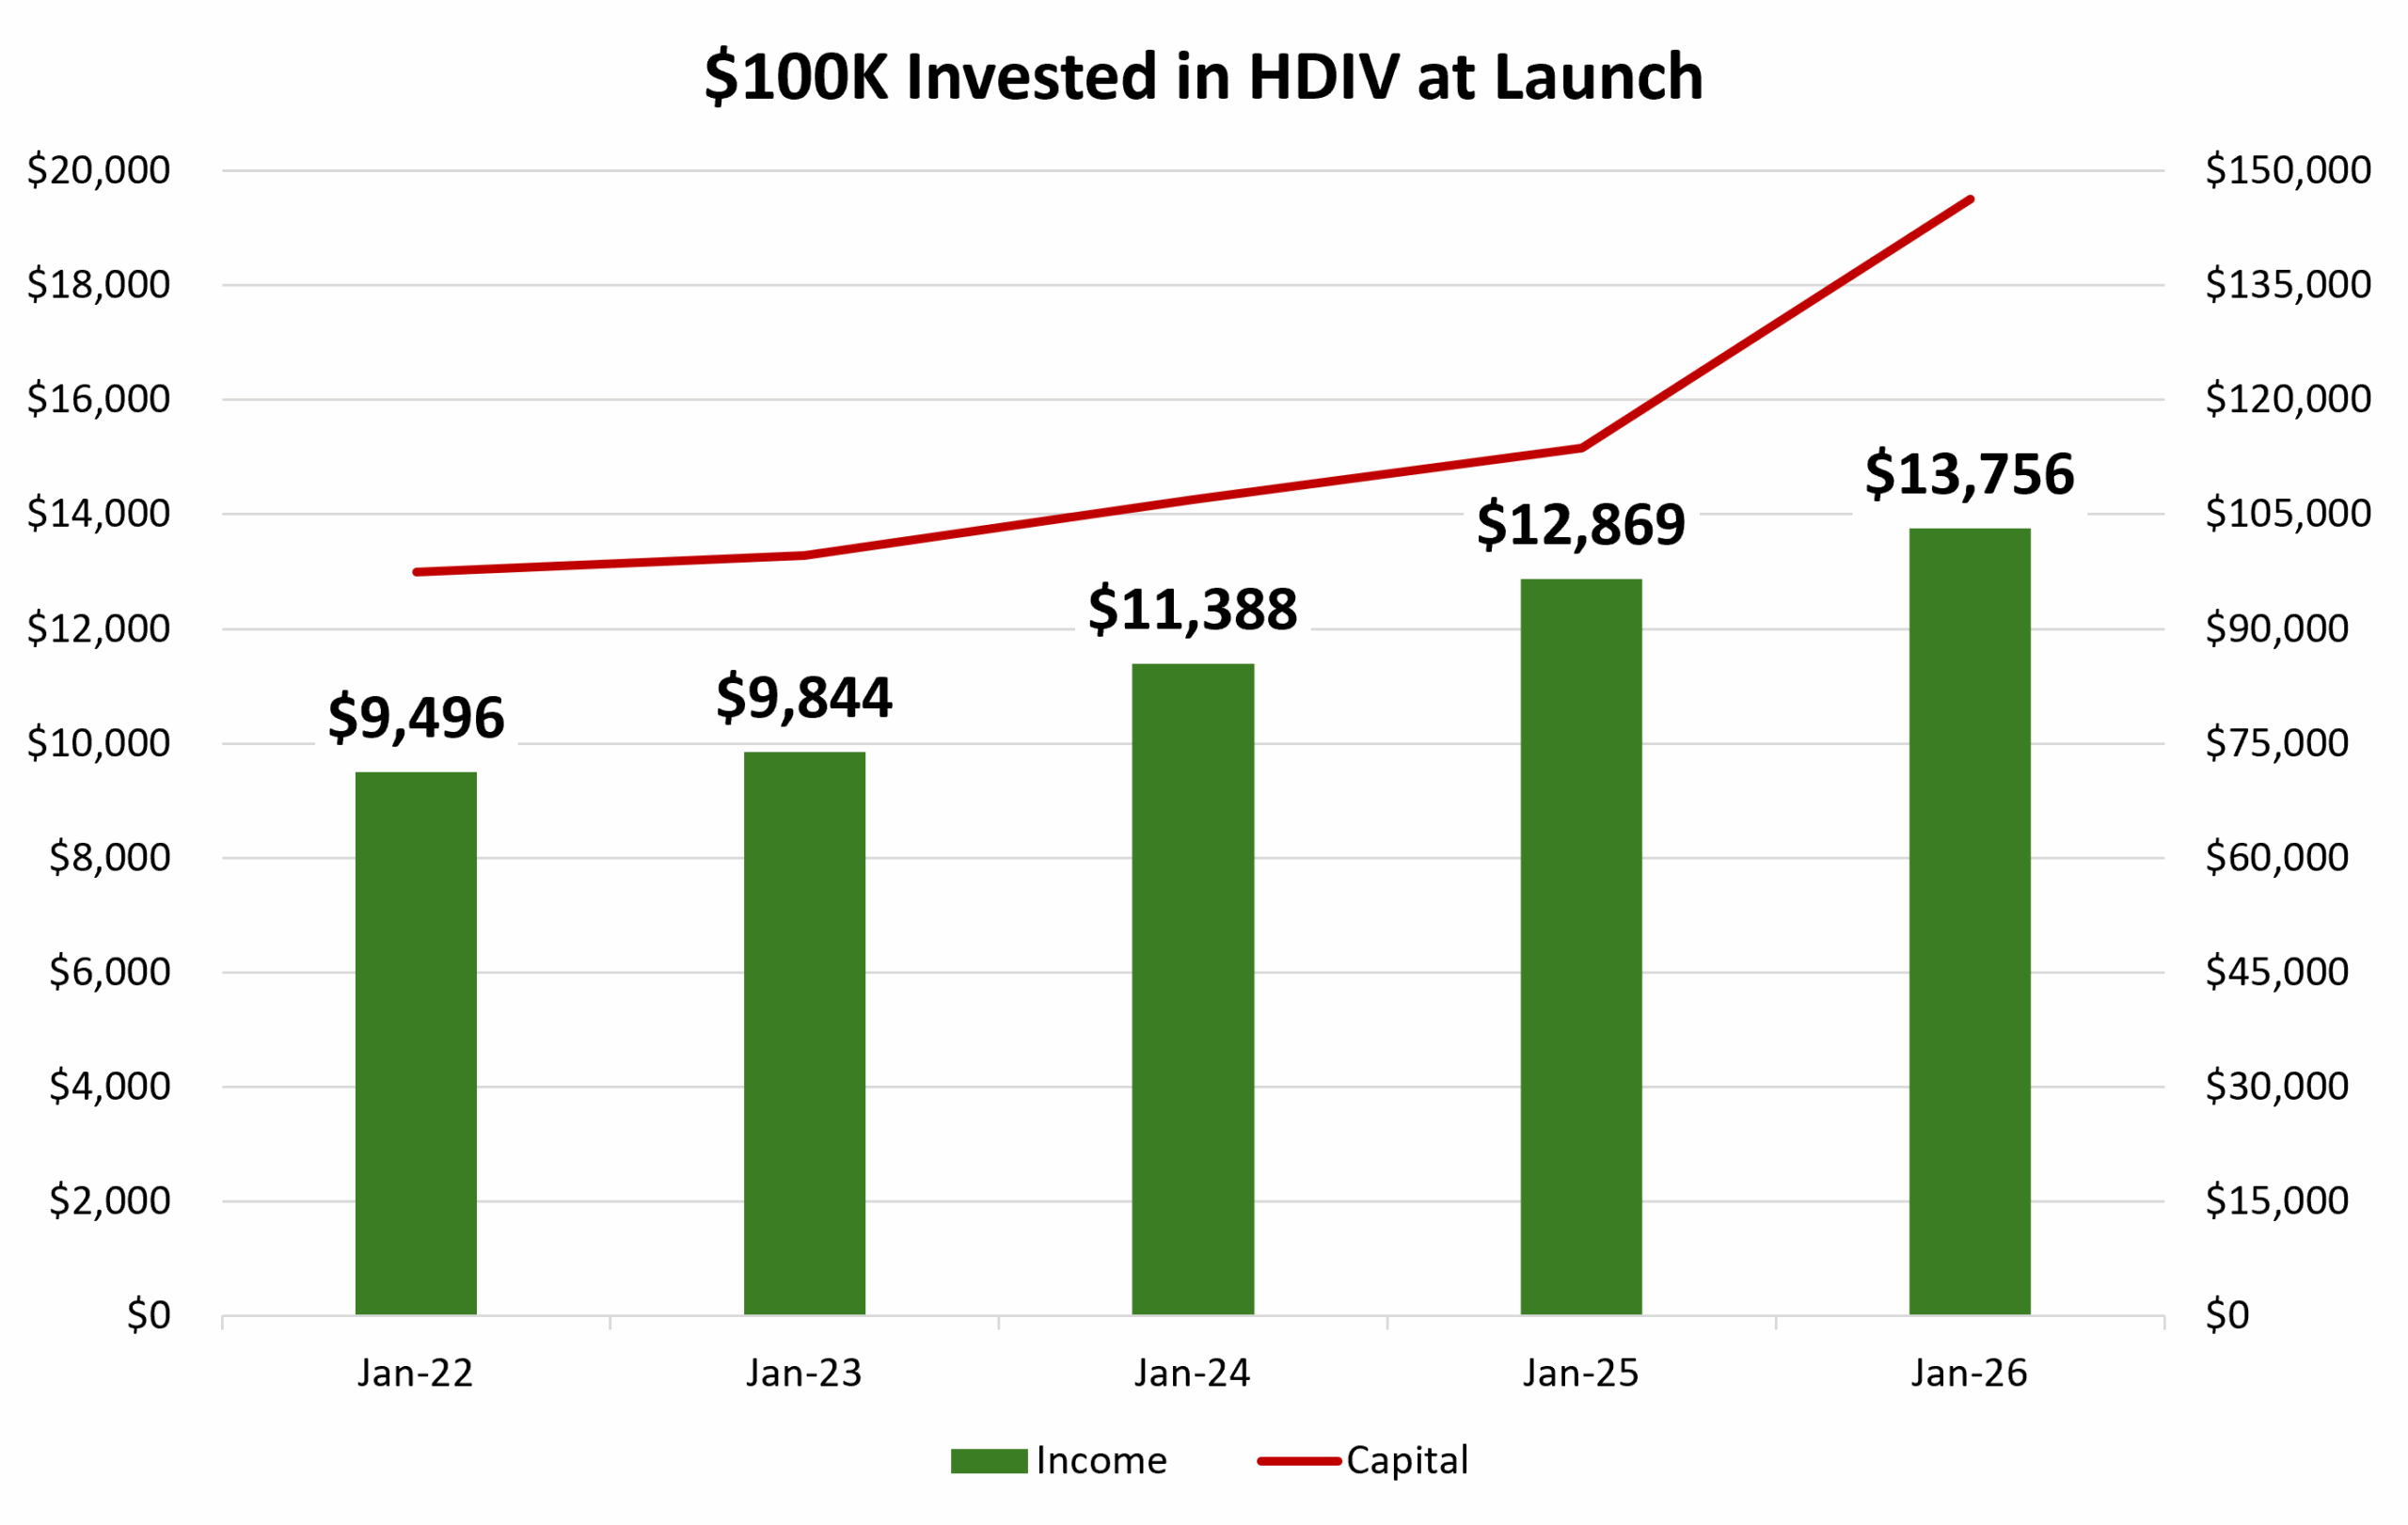
If you invested $100,000 in HDIV at launch, your investment would be $244,000 with reinvested distributions, as seen in the chart above. Assuming you did not reinvest your distributions, your invested capital grew from $100,000 to $144,875 and you received $56,950 in cash. The chart below shows your total annual income from HDIV and capital growth over five years. So you did not just receive cash flow; your capital appreciated as well.
What has driven HDIV’s performance?

Every aspect of our ETFs is carefully thought-out and tested with the intention that they be long-term responsible investments, and HDIV is no exception. Two structural features have been central to HDIV’s success: modest leverage and broad sector diversification.

Enhanced Structure

HDIV has an enhanced structure with modest leverage of 25%, achieved by borrowing at relatively lower institutional rates. How does this work? For every $100 you invest, HDIV borrows an additional $25, investing a total of $125 in its portfolio and amplifying the fund’s overall yield and growth potential.

Of course, investors should keep in mind that leverage can work both ways, amplifying growth during market rallies as well as losses during downturns. While leverage does add risk and volatility to your portfolio, HDIV only has a modest amount.

Broad Sector Diversification with Blue-Chip Holdings

HDIV is an ETF made up of 10 sector-focused, blue-chip covered call ETFs from our YIELD MAXIMIZER™, Enhanced Growth and DayMAX™ suites. Their weightings have been chosen with the aim of giving HDIV a sector mix broadly similar to that of the S&P/TSX 60.

HDIV’s focus on high-quality stocks is clear when you examine its underlying holdings, which are primarily leading large-cap companies with strong fundamentals. Around 44% of HDIV’s underlying holdings are the largest Canadian financial stocks like the Big Six banks and Canada’s largest insurance company by total assets, Manulife Financial[6]. Energy and technology giants account for over 30% of the fund[7].
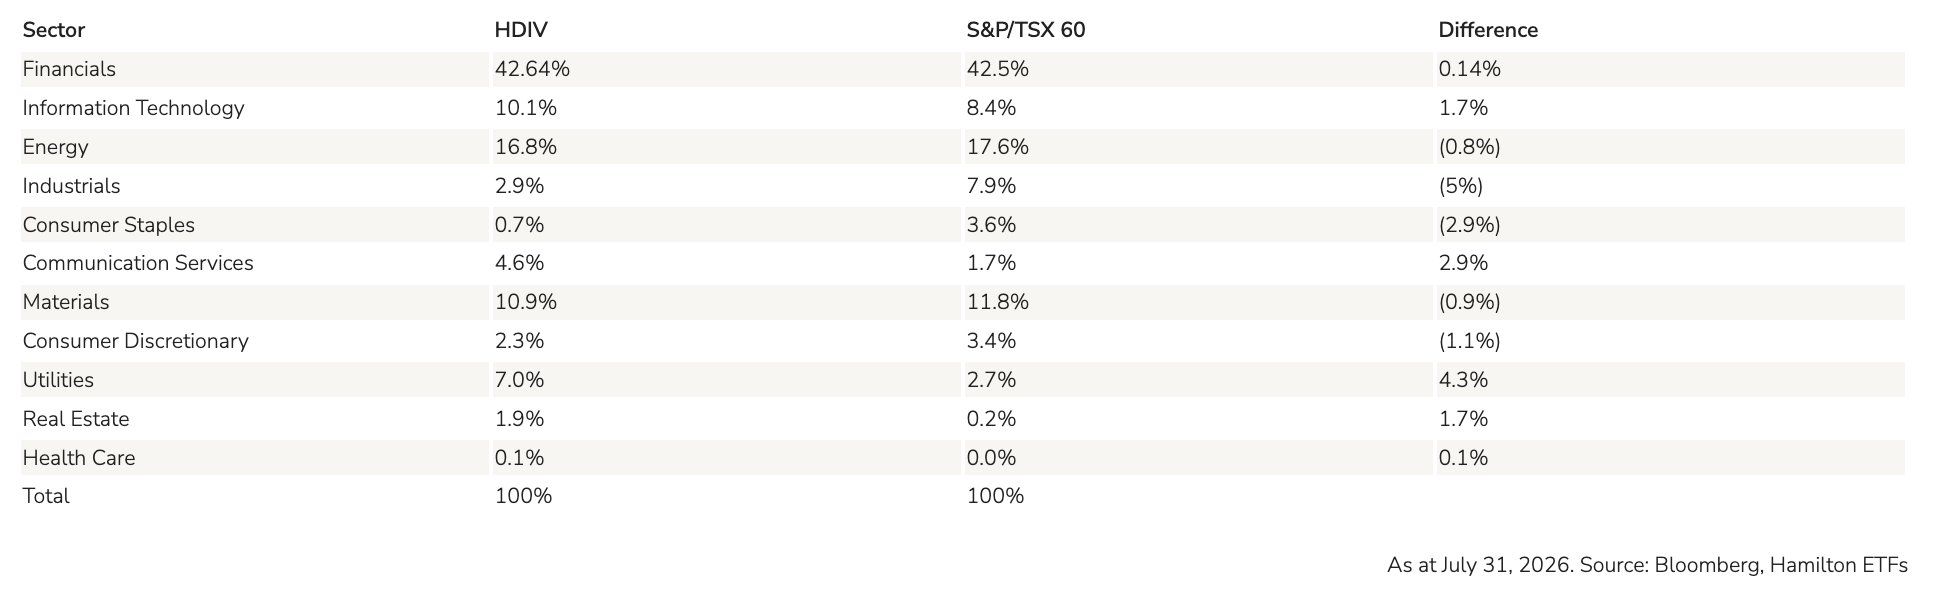
 

We also believe HDIV’s underlying holdings are an improvement in the breadth of the S&P/TSX 60 index. Certain Canadian sectors, like energy and technology, are heavily concentrated in a very small number of large-cap stocks. HDIV addresses this lack of diversification by including leading U.S. companies. For example, HDIV holds market leaders like Apple and Microsoft through the Hamilton Technology YIELD MAXIMIZERTM ETF (QMAX) and the Hamilton Enhanced Technology DayMAXTM ETF (QDAY).

The Hamilton ETFs advantage with covered call strategies

As a member of the Hamilton ETFs line-up, HDIV’s underlying covered call strategy is managed by our options team, which has 60+ years of combined experience and is led by Chief Options Strategist Nick Piquard.

Five years in

Five years after HDIV’s launch, we believe the results provide a tangible answer to our original question: can covered call ETFs be improved? HDIV has paired strong total returns with growing monthly distributions and broad diversification, clearly resonating with investors who have helped grow the ETF to more than $1.8 billion in assets. Its first five years have, in our view, demonstrated how an enhanced covered call structure can combine capital growth with a stream of monthly income.

Trivia

The AI investment boom is so big, it’s reshaping economies. What 19th century technological breakthrough triggered an even greater U.S capital spending spree (as a percentage of GDP)?

Hint: The two biggest holdings in Hamilton Utilities YIELD MAXIMIZER™ ETF (UMAX) are involved in this industry.

Answer: Railways.

Disclaimer

Certain statements contained in this article may constitute forward-looking information within the meaning of Canadian securities laws. Forward-looking information may relate to a future outlook and anticipated distributions, events or results and may include statements regarding future financial performance. In some cases, forward-looking information can be identified by terms such as “may”, “will”, “should”, “expect”, “anticipate”, “believe”, “intend” or other similar expressions concerning matters that are not historical facts. Actual results may vary from such forward-looking information. Hamilton ETFs undertakes no obligation to update publicly or otherwise revise any forward-looking statement whether as a result of new information, future events or other such factors which affect this information, except as required by law.

The S&P 500 Index and the S&P/TSX 60 Index (“Indices”) and associated data are a product of S&P Dow Jones Indices LLC, its affiliates and/or their licensors and have been licensed for use by Hamilton ETFs © 2026 S&P Dow Jones Indices LLC, its affiliates and/or their licensors. All rights reserved. Redistribution or reproduction in whole or in part are prohibited without written permission of S&P Dow Jones Indices LLC. For more information on any of S&P Dow Jones Indices LLC’s indices, please visit www.spdji.com. S&P® is a registered trademark of Standard & Poor’s Financial Services LLC (“SPFS”) and Dow Jones® is a registered trademark of Dow Jones Trademark Holdings LLC (“Dow Jones”). Neither S&P Dow Jones Indices LLC, SPFS, Dow Jones, their affiliates nor their licensors (“S&P DJI”) make any representation or warranty, express or implied, as to the ability of any index to accurately represent the asset class or market sector that it purports to represent and S&P DJI shall have no liability for any errors, omissions, or interruptions of any index or the data included therein.

Commissions, management fees and expenses all may be associated with investments in exchange traded funds (ETFs) managed by Hamilton ETFs. Please read the prospectus before investing. The indicated rates of return are the historical annual compounded total returns including changes in per unit value and reinvestment of all dividends or distributions and does not take into account sales, redemptions, distribution or optional charges or income taxes payable by any securityholder that would have reduced returns. Only the returns for periods of one year or greater are annualized returns. ETFs are not guaranteed, their values change frequently, and past performance may not be repeated.


[1] Based on total annualized returns since inception on July 19, 2021. As at July 31, 2026. Source: Bloomberg

[2] Source: Bloomberg

[3] Distributions are not guaranteed, may fluctuate and are subject to change and/or elimination.

[4] Current annualized yields as at July 31, 2026. The yield calculation excludes any additional year end distributions and does not include reinvested distributions. Source: Bloomberg, Hamilton ETFs.

[5] Source: Solactive AG, Bloomberg, Hamilton ETFs. Data from July 19, 2021 to July 31, 2026.

The graph illustrates the growth of an initial investment of $100,000 in HDIV vs the S&P/TSX 60 Index with annual compounded total returns. The graph is for illustrative purposes only and is intended to demonstrate the historical impact of the compound growth rate. It is not a projection of future performance, nor does it reflect potential returns on investments in HDIV. Investors cannot directly invest in the index. All performance data assumes reinvestment of distributions and excludes management fees, transaction costs, and other expenses which would have impacted an investor’s returns.

[6] As at July 31, 2026

[7] As at July 31, 2026



Retired Money on The Wealthy Barber’s retirement at the end of this year

My latest MoneySense Retired Money column looks at the imminent retirement of The Wealthy Barber himself: David Chilton. You can find the full column here:  The Wealthy Barber retires.

Chilton, who will reach the traditional retirement age of 65 late this October, announced in June on his popular YouTube podcast that  he’d be retiring at the end of 2026, a story soon picked up by the Globe & Mail.

My Retired Money column has focused on individual retirements now of Rob Carrick and blogger Mark Seed. Like Chilton, these people are younger than myself: I describe myself as only semi-retired, which is how I view Carrick and Seed. On his two-year-old The Wealthy Barber podcast, Chilton has now twice interviewed Carrick about his Retirement and also about his views on the high costs of housing.

As my MoneySense interview with him clarifies, Chilton views his transition as being closer to the traditional “Full Retirement” than the more gradual semi-retirement that Carrick and I are practicing. My view of Traditional Retirement is leaving a full-time salaried employee relationship and all that entails: commuting to a central place, bosses and meetings, taxes withheld at source, etc. Of course, Chilton has seldom if ever been an employee: he’s been a self-employed author and public speaker almost from the get-go. But as he reveals, his successful speaking career meant doing a lot of business travel and committing his time in advance: something he now wishes to reduce in order to have more personal freedom.

When and if he does pack it in in December, it will end an intense few years where he “aggressively” participated again in the Canadian personal finance content space that he helped pioneer in the first place.

Apart from public speaking, which he will cut back on in 2027, Chilton launched a successful biweekly podcast on YouTube that soon became weekly, promoted through video shorts on Facebook and TikTok. I can see how weekly podcasts could constitute almost a full-time job in itself so it should be no surprise that he will wind that up at the end of the year, despite the fact many around him would like to see it continue in some form.

Rewritten Canadian edition of The Wealthy Barber took longer to do than the original

The other big push he made was a massive two-year extensively rewritten 2025  Canadian edition of the book that made his career when he published it at age 27 in 1989. Chilton says it took him longer to revise (rewrite)  the new edition than to write the original! His focus is on Canadians 45 years old or younger, many of whom are struggling to get a toehold in the housing market (which includes my own daughter). Continue Reading…

The World didn’t break: Franklin Templeton Institute’s mid 2026 Investment Outlook

Image courtesy Franklin Templeton Institute

By Stephen Dover, CFA, Franklin Templeton Institute

(Sponsor Blog)

Executive Summary

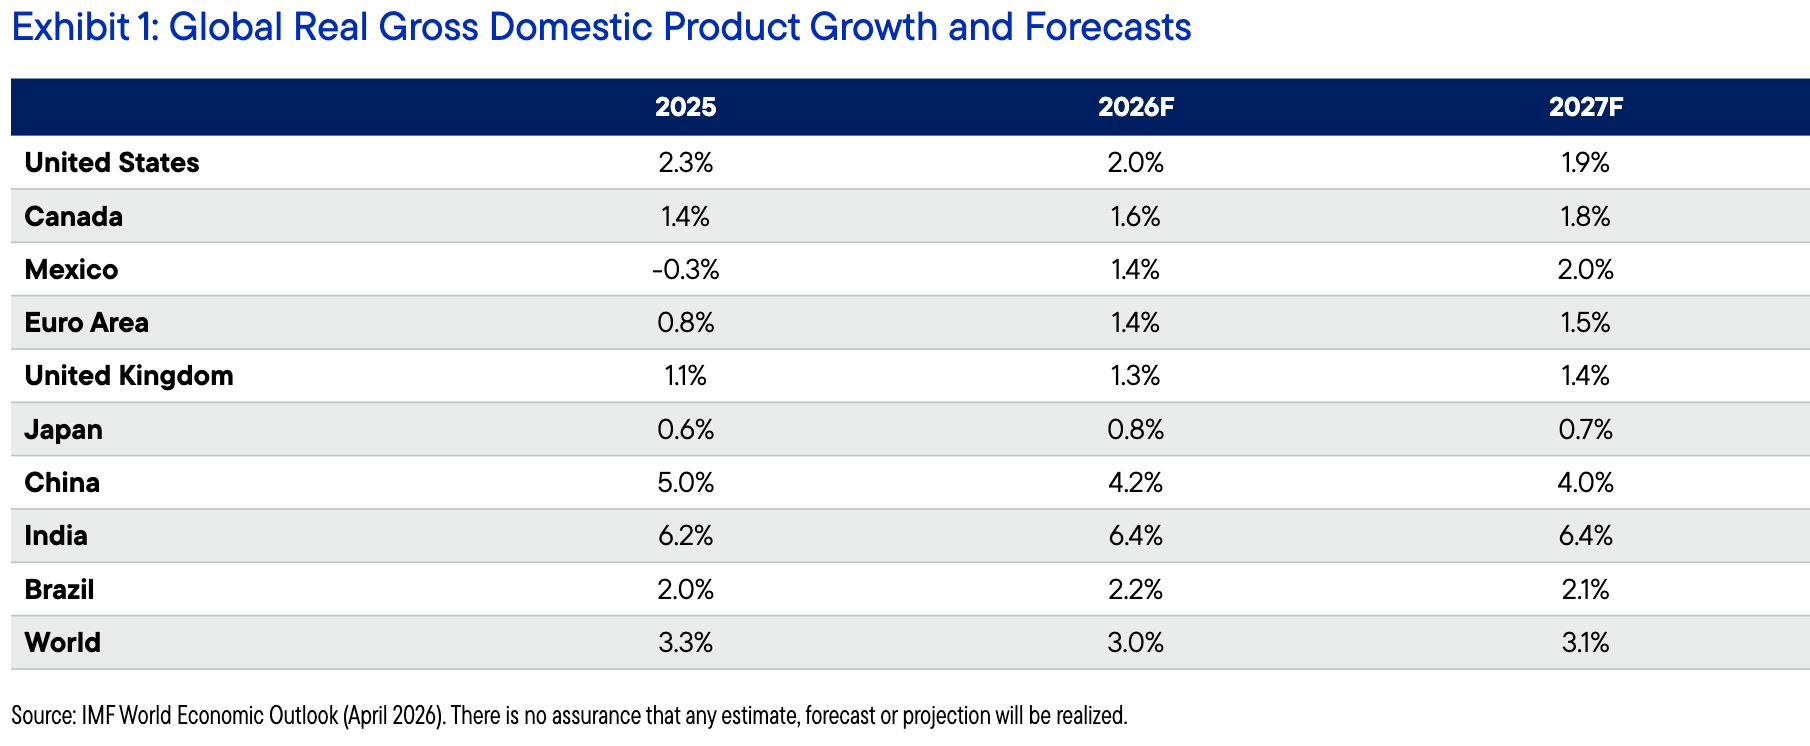
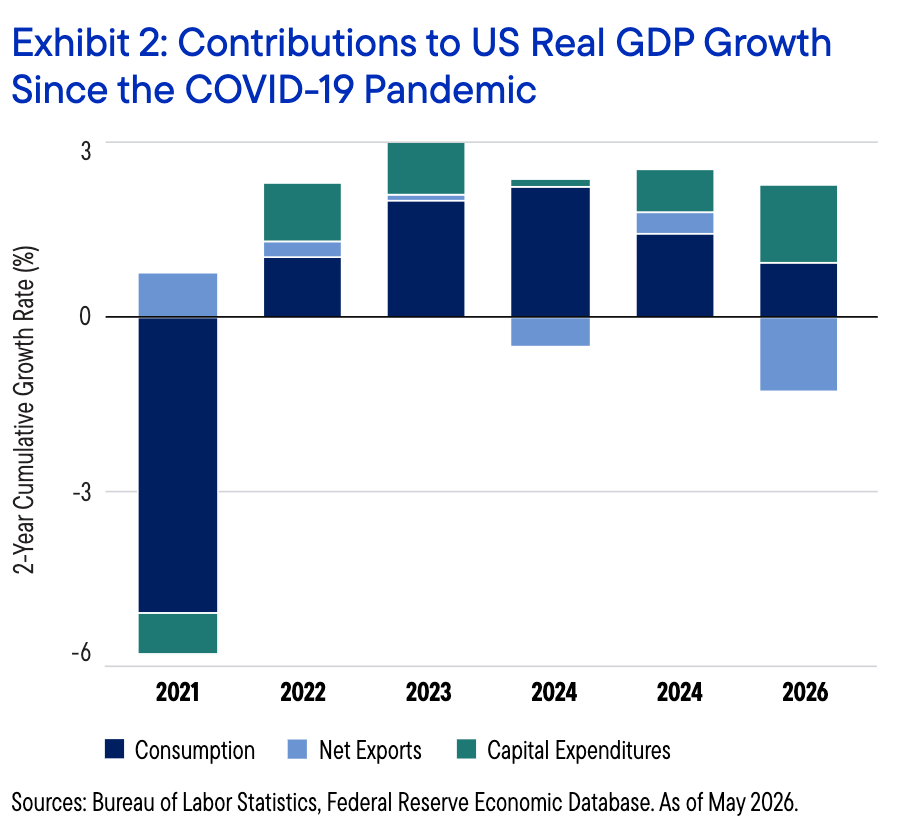
• Resilience is the key theme for 2026. Markets and economies have held up well despite geopolitical shocks, policy uncertainty and rising inflation. Global growth remains close to trend, supported by consumer spending, business investment, productivity gains and strong corporate profits.
• We expect investment opportunities to broaden across global equity markets, while corporate credit markets should remain stable. Strong earnings in the United States and emerging markets will support a wider set of opportunities across regions and sectors. • Tighter monetary policy should keep bond yields high and yield curves flat, creating opportunities to earn income. We favor US high-yield credit, select emerging market debt — especially in Latin America — and municipal bonds for US taxpayers.
• Long-term themes remain compelling. Artificial intelligence (AI) is driving demand for energy, infrastructure and broader economic change; rising investment in defense, national security and energy infrastructure create long-term potential return opportunities. Aging populations will require investment in labor-saving technologies, assisted living and health care innovation.
• In private markets and alternatives, secondaries, private credit, real estate and infrastructure offer attractive opportunities.
• Risk to the view. Geopolitical conflict, inflation and a stronger central bank response remain key risks for investors to watch in the second half of 2026.

Introduction

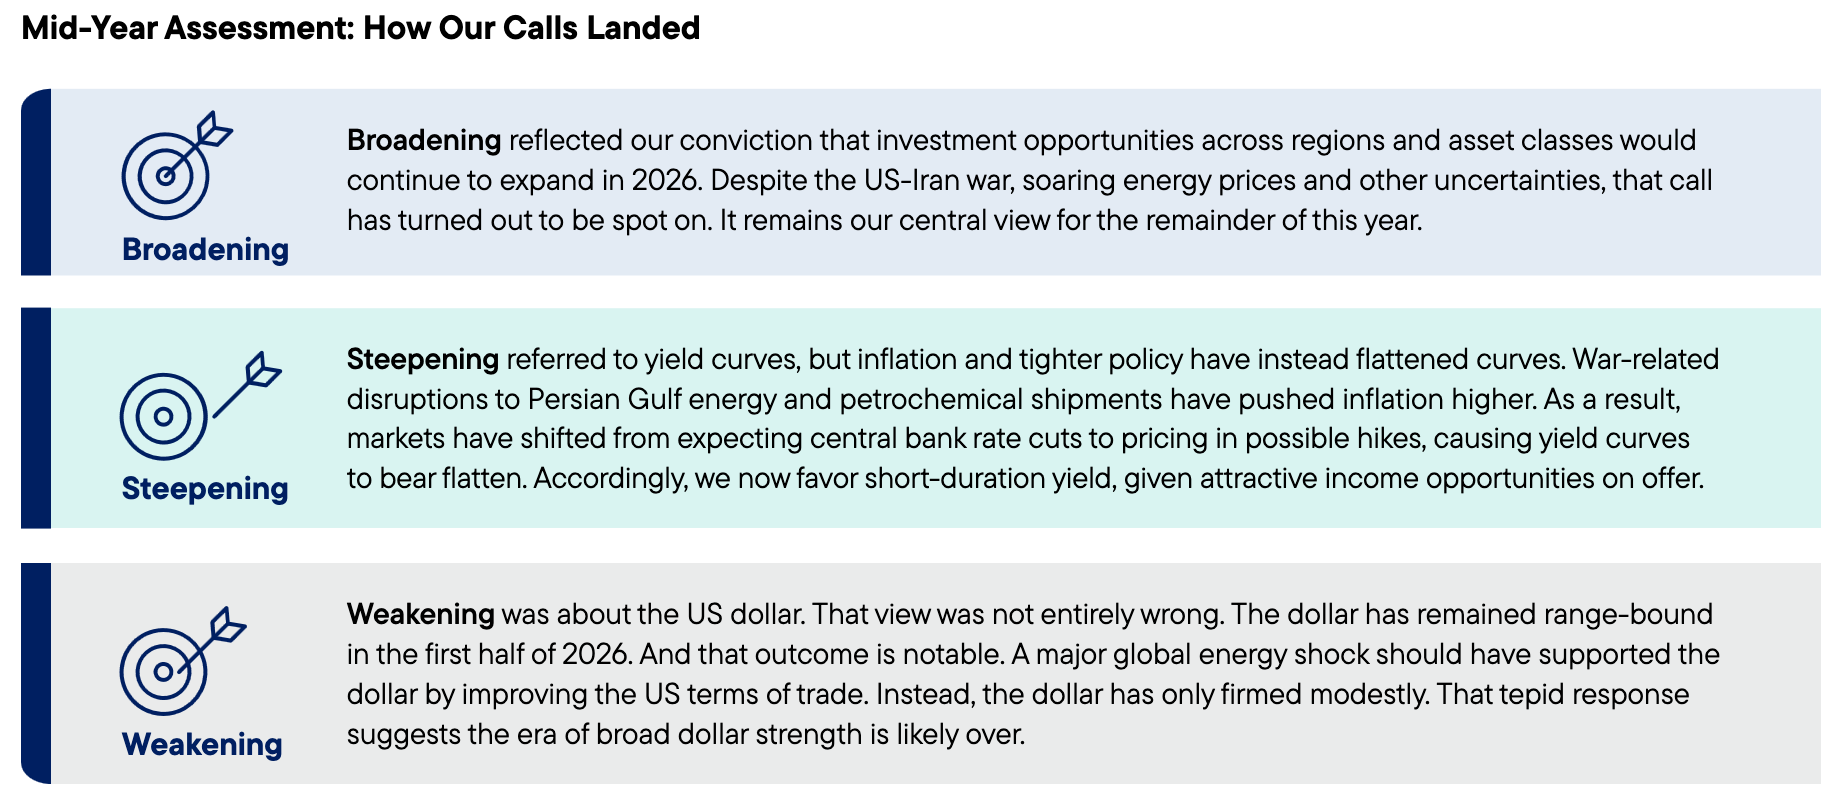
Global Investment Outlook: 2026 and Beyond was built around three cyclical themes — broadening, steepening, and weakening — and three longer-term forces shaping investor portfolios: intelligence, private markets and big government.

Midway through 2026, we think that framework still provides a useful starting point, but the balance of risks has changed. Broadening remains firmly intact, supported by resilient economic growth, strong earnings and improving opportunities across regions and asset classes. But steepening of yield curves has given way to higher-for-longer yields, reflecting higher inflation and tighter monetary policies. Higher yields, however, also offer improved income opportunities in shorter-duration holdings, including US high yield and select emerging markets.

Meanwhile, the US dollar has firmed and is likely to remain rangebound rather than weak over the remainder of 2026. Most importantly, the world did not break. Despite war, tariffs, inflation, tighter policy and geopolitical fragmentation, the global economy and financial markets have held together better than many expected. This update therefore reframes the outlook around a single organizing idea: resilience: both the resilience already evident in economies and markets, and the resilience investors may need to build into portfolios for the remainder of the year.

A more Resilient Outlook (or Resilience in Markets and Portfolios)

The rest of this outlook is organized around one central idea: resilience. The phrase “the world didn’t break” is not meant to suggest that risks have disappeared or that the outlook is free of strain. Rather, it captures the defining surprise of 2026 so far: economies, markets, companies and investors have absorbed a series of shocks without a sustained breakdown in growth, earnings, credit or global trade.
The first sections explain why the global economy and financial markets have held up better than many expected, despite 18 months of geopolitical turbulence, tariffs, war, elections and rising inflation. They also show how resilience has been supported by solid economic growth and strong corporate profits growth across sectors and regions.
From there, we translate resilience into investment implications for equities, fixed income, private markets and alternatives. We also identify key long-term (thematic) opportunities. In all dimensions, we focus on where resilience is apparent and where it can create opportunities for investors in the second half of 2026.

This year, the global economy has demonstrated remarkable resilience in the face of numerous challenges, including geopolitical tensions, trade disputes, fiscal pressures, rising inflation and a sharp re-pricing of central bank policy responses.

Globally, wealth effects and favorable financial conditions have also supported consumption and capital expenditures.
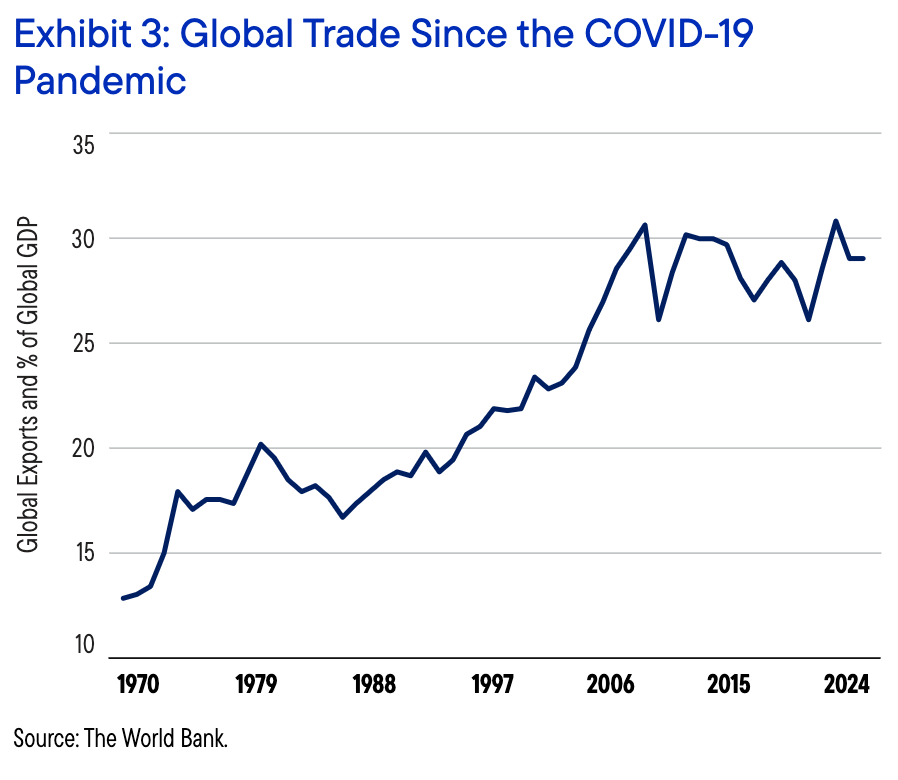
Notably, trade has held up better than many feared following the introduction of high US tariffs in 2025. Global commerce has continued to expand, with important contributions from services.

China’s economy has also demonstrated notable resilience in 2026 despite ongoing challenges from a weak property sector, geopolitical tensions and trade frictions with the United States. The diversification of China’s growth drivers has been a key factor. Strong investment in advanced manufacturing, technology, renewable energy, electric vehicles, batteries and AI has helped offset weakness in real estate. These sectors have benefited from both government support as well as from strong domestic and international demand.

China’s exports have also remained more robust than many expected. Chinese firms have adapted to changing trade patterns by expanding into emerging markets, strengthening supply chains and increasing exports of higher-value-added products. As a result, China has maintained a significant role in global manufacturing and trade despite rising protectionist pressures. Continue Reading…

How to Spot employers with a Modern Career Path conducive to Financial Independence (FIRE)

Image courtesy Pexels: Tima Miroshnichenko

By Tessa Dodson

Special to Financial Independence Hub

Not every high-paying job accelerates your journey to Financial Independence (FI). The real difference lies in spotting a company with a modern, FI-friendly career path that combines strong compensation with flexibility, autonomy and genuine growth opportunities. These organizations pay well while creating conditions that allow you to build wealth faster and on your terms.

What a FIRE-Friendly Career Path really means

A Financial Independence, Retire Early (FIRE) career path demands more than raw earning power. In addition to high compensation, you need a strong work-life balance that leaves room for side income and a culture that values autonomy over micromanagement. A balanced lifestyle supports job satisfaction and engagement, keeping work sustainable and fulfilling.

The most FI-friendly companies offer predictable schedules, remote flexibility and trust-based management. These conditions allow you to maintain side projects, develop new skills and preserve the mental energy that strategic financial planning requires. Companies with healthy work hours allow daily recovery time that supports individual well-being and job performance.

Look for Cultures that prioritize Results and Flexibility

The clearest signal of a positive company culture is a focus on results and deliverables. Organisations that measure success by output rather than desk time create environments in which high performers work efficiently and reclaim hours for wealth-building activities.

Look for flexible scheduling policies, outcome-based performance metrics and leadership that respects boundaries. Presenteeism cultures do the opposite, rewarding visible activity over actual productivity and forcing you to trade time for appearance. The cost is measurable in hours you could allocate to wealth-building.

Decode a company’s commitment to Real Growth

How a company approaches development reveals whether it will support or stifle your trajectory. Surveys show that 60 to 70% of HR professionals express dissatisfaction with performance management systems. This signals a majority of rigid, outdated cultures that hinder both growth and flexibility.

Modern employers invest in career development programs that include mentorship, skill-building opportunities and clear advancement paths. These green flags indicate an organization that prioritizes meaningful employee development. During your research, examine whether the employer offers structured learning, cross-functional projects and visible promotion patterns that reward performance.

Seek Radical Transparency in Pay and Promotions

You can’t map a route without coordinates, and compensation transparency provides them. Companies that publish pay bands and promotion criteria let you project your earning potential with precision, which is critical when you’re calculating your FI timeline. Continue Reading…

Your Best Investment could become a Huge Tax Problem

How American and Canadian investors can reduce capital gains taxes after decades of buying and holding.

AlainGuilot.com via Grok


By Alain Guillot

Special to Financial Independence Hub

Buying a broad-market ETF and holding it for decades is one of the simplest ways to build wealth.

You buy an ETF like the Vanguard S&P 500 ETF (VOO) for U.S. investors or the iShares S&P/TSX 60 Index ETF (XIU) for Canadian investors. You reinvest the dividends, ignore the daily market noise and continue adding money whenever you can.

Twenty years later, the strategy has worked beautifully.

But now you have a new problem: how do you reduce capital gains tax when selling an ETF that has increased enormously in value?

This is the strange punishment for being a successful long-term investor.

You followed the advice to buy and hold. You resisted panic selling. You avoided speculation and unnecessary trading.

Now your portfolio may contain hundreds of thousands of dollars in unrealized gains.

Selling a large amount in one year could create a substantial tax bill. It could also push your income into a higher tax bracket and affect income-tested benefits.

This is not merely a theoretical question for me. I have accumulated VOO and XIU for many years, and I know that selling a large portion at once could create a painful tax expense.

Fortunately, selling everything in one year is not the only option.

First, Understand the Capital Gains Problem

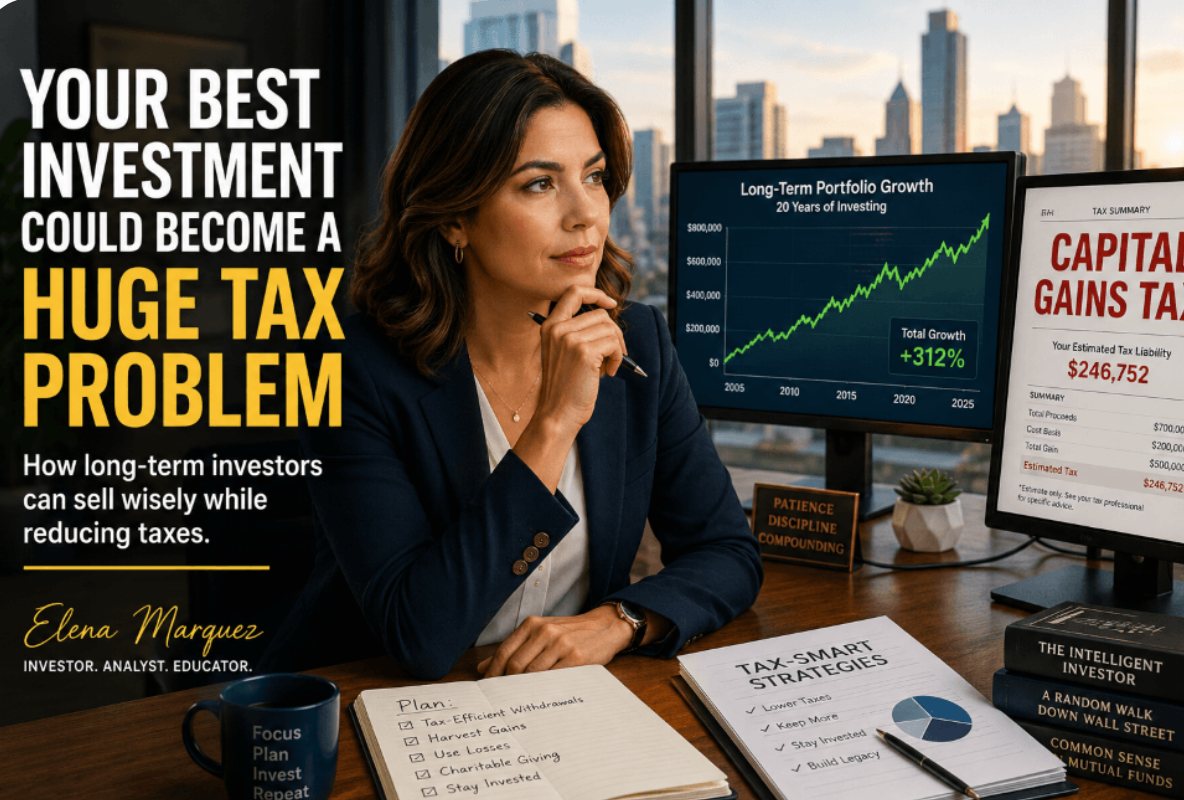
Suppose you invested $200,000 in VOO over many years.

Your investment is now worth $700,000.

Your unrealized capital gain is approximately:

$700,000 market value − $200,000 cost = $500,000 gain

You do not owe capital gains tax simply because VOO increased in value.

The tax is generally triggered when you sell or otherwise dispose of the investment.

That means you have some control over when the gain is realized.

The central question is not:

How can I avoid paying any tax?

A better question is:

How can I realize this gain gradually and pay the lowest reasonable amount of tax over my lifetime?

That change in perspective is important.

Reduce Capital Gains Tax by Avoiding One Giant Sale

The worst approach may be to sell the entire position without first calculating the consequences.

A large sale could concentrate decades of gains into a single tax year.

In both Canada and the United States, capital gains interact with the investor’s other income. Realizing more gains can bump you up to a higher tax braket and thus you will pay a higher tax rate.

A more efficient strategy is often to sell your ETF gradually.

For example, an investor could sell enough each year to cover:

  • Annual living expenses
  • Planned travel
  • Major purchases
  • Charitable donations
  • Portfolio rebalancing

Instead of realizing a $500,000 gain in one year, the investor might spread the gain over 10, 15 or 20 years.

This does not eliminate the tax.

It gives the investor more control over the rate and timing and hi might be taxed in a lower tax bracket.

Strategy 1: Sell more during Low-income Years

Some years are naturally better than others for realizing capital gains.

Good opportunities may arise:

  • After retirement but before pensions begin
  • Before collecting Social Security or government benefits
  • Before mandatory retirement-account withdrawals
  • During a sabbatical or period of reduced employment
  • In a year with large deductions
  • In a year when business income is unusually low

These lower-income years can create room to realize gains at a more favourable rate.

For American investors

The United States applies special federal tax rates to long-term capital gains.

Depending on taxable income, some long-term capital gains may fall into the 0% federal capital gains bracket. Higher-income investors generally face 15% or 20% federal rates, and some may also owe the 3.8% net investment income tax. State taxes may apply as well.

This creates a powerful planning opportunity.

An American investor with unusually low taxable income may sell some VOO, realize a long-term gain and potentially pay no federal capital gains tax on part of that gain.

The investor can then buy VOO again.

The newly purchased shares receive a higher cost basis, reducing a future taxable gain.

For Canadian investors

Canada does not have a special 0% capital gains bracket comparable to the American system.

Instead, only a portion of a capital gain is included in taxable income. The proposed increase in Canada’s capital gains inclusion rate was cancelled, leaving the one-half inclusion system in place.

If a Canadian investor realizes a $20,000 capital gain, $10,000 is generally included in taxable income under the one-half inclusion rate.

The final tax depends on the investor’s federal and provincial marginal tax rates.

A Canadian investor with little other income may therefore realize gains at a relatively modest tax cost. The investor can repurchase their ETF immediately, increasing the adjusted cost base.

This practice is known as capital gain harvesting.

Strategy 2: Harvest Capital Gains every year

Most investors have heard about tax-loss harvesting.

Capital gain harvesting receives far less attention.

Here is how it works:

  1. Estimate your taxable income for the year.
  2. Calculate how much additional capital gain you can realize without entering an undesirable tax bracket.
  3. Sell enough of your ETF to realize that gain.
  4. Repurchase the same ETF inmediately after selling it.
  5. Record the transaction and update the cost basis.

The investor remains invested while gradually increasing the tax cost of the portfolio.

Over many years, this can reduce the unrealized gain that remains in the account. I use this strategy every year. I sell a portion of my investments, realize some capital gains, and buy the same investment inmediately after selling it.

Can you buy the same ETF back immediately?

Yes, when you sold it for a gain.

The American wash-sale rule and the Canadian superficial-loss rule are designed to restrict the recognition of losses when substantially identical securities are quickly repurchased.

They do not generally prevent an investor from repurchasing an investment immediately after realizing a gain.

Capital gain harvesting can therefore be completed without remaining out of the market for 30 days.

The disadvantage is that you are paying some tax earlier than necessary. As a citizen of this wonderful country, I don’t mind paying some taxes on my gains, as long as those taxes are not exessive and feel as a punishment for my success.

Money paid in tax today can no longer remain invested and compound.

The strategy is most attractive when the current tax rate is lower than the rate you reasonably expect to face later.

Strategy 3: Use Capital Losses to Offset your ETF Gains

A diversified portfolio may contain investments that have declined in value.

Selling one of those investments creates a capital loss that may offset part of the gain realized from selling your ETF. This strategy is called Tax-loss harvesting.

For example:

  • Gain from selling VOO: $30,000
  • Loss from selling another investment: $12,000
  • Net capital gain: $18,000

This allows the investor to reduce the VOO position while limiting the immediate tax bill.

United States

American investors can use capital losses against capital gains.

When losses exceed gains, a limited amount may generally be deducted against other income, with unused losses carried forward to later years.

The wash-sale rule must be considered before repurchasing the losing investment.

Canada

Canadian net capital losses can generally be used against taxable capital gains.

Unused net capital losses may normally be carried back as far as three years or carried forward to future years.

Canada’s superficial-loss rule may deny an immediate loss when the investor—or an affiliated person—buys the same or identical property during the restricted period and still owns it 30 days after the sale.

Again, this rule matters for losses, not gains.

Strategy 4: Donate your ETF instead of Cash

Investors who regularly support charities should consider donating appreciated ETF shares directly.

This can be much more tax-efficient than selling your ETF and donating cash.

For American investors

An American investor who donates qualifying appreciated securities held for more than one year may generally avoid recognizing the embedded capital gain.

The investor may also qualify for a charitable deduction, subject to deduction limits, documentation requirements and whether the investor itemizes deductions.

The charity receives the shares and can sell them without creating a capital gains tax bill for the donor.

Instead of donating $10,000 in cash, the investor could transfer $10,000 of his long held ETF containing a large unrealized gain.

The investor keeps the cash and removes some of the portfolio’s oldest, lowest-cost shares.

For Canadian investors

Canada also offers favourable treatment for direct donations of publicly traded securities to registered charities.

Qualifying donations can receive a zero capital-gains inclusion rate, while the donor may also receive a charitable donation tax credit.

The important word is directly.

Selling your ETF first and donating the cash may trigger the capital gain. Transferring the ETF shares directly to the charity may avoid it.

This is one of the few strategies that can genuinely eliminate the tax on part of an appreciated ETF position.

Of course, it only makes financial sense for money that the investor already intends to give to charity.

Strategy 5: Choose which Shares to Sell

This is one area where the American and Canadian systems differ significantly.

American investors may identify specific shares

An American investor may have purchased his favorite ETF at many different prices.

Some shares may have a cost basis of $150, while newer shares may have a basis of $500.

When selling, the investor may be able to instruct the broker to sell specific shares.

Selling the highest-cost shares first produces a smaller taxable gain.

For example:

  • Sale price: $600
  • Old share cost: $150
  • Gain: $450

Compared with:

  • Sale price: $600
  • Newer share cost: $500
  • Gain: $100

Specific-share identification can help American investors control which gains are realized. Proper instructions and records are essential. IRS guidance requires investors to maintain records supporting the basis of their investments.

Canadian investors use an average adjusted cost base

Canadian investors generally cannot select the highest-cost ETF shares and pretend those were the only units sold.

Identical securities are pooled together.

The investor must calculate the average adjusted cost base of all identical ETF units held in non-registered accounts. The gain on a sale is based on that average cost.

This makes accurate recordkeeping especially important.

Broker records may not always correctly combine ETF held across multiple Canadian taxable accounts.

Honestly I prefer the Canadian systeme of average adjusted cost much better. I have been making many different purchases during more than 10 years. It’s a headache to keep record of that small purchase I did of the XIU ETF 10 years ago.

Strategy 6: Keep Accurate Records

Before worrying about how to reduce capital gains tax, make sure the gain has been calculated correctly.

An incorrect cost basis can produce an unnecessarily large tax bill.

The records should include:

  • Every purchase
  • Reinvested distributions
  • Brokerage commissions
  • Stock splits
  • Transfers between brokers
  • Return-of-capital distributions
  • Previous sales
  • Currency conversions, when applicable

Special issue for Canadians holding U.S ETFs in U.S. dollars

U.S. ETF trades in U.S. dollars, but Canadian taxes must generally be calculated in Canadian dollars.

The purchase cost must be translated into Canadian dollars using the appropriate exchange rate at the time of purchase. The sale proceeds must also be translated using the relevant exchange rate at the time of sale.

A gain that appears to be modest in U.S. dollars may be larger in Canadian dollars if the Canadian dollar weakened during the holding period.

The CRA calculates gains by subtracting the adjusted cost base and selling expenses from the proceeds of disposition.

Investors who accumulated a U.S. ETF over 20 years may need to reconstruct many transactions.

That effort can be worthwhile.

Finding forgotten purchases, commissions or reinvested distributions may increase the adjusted cost base and reduce the taxable gain.

Strategy 7: Stop Reinvesting Dividends

An investor who is approaching retirement may not need to continue reinvesting every dividend from their ETF.

Instead, the cash distributions can be used for living expenses.

Continue Reading…