General

Tax season is over: or is it?

To reduce future tax bills, now is the time to start planning

By Rob Cordasco

Special to the Financial Independence Hub (American Content)

With this year’s income-tax-filing deadline finally past, you may have sat back with a sigh of relief, happy to forget about taxes for another year. But that’s a mistake because it’s already time to start thinking about taxes for next year if you hope to lower the amount you ultimately will owe, says Rob Cordasco (www.cordasco.cpa), a CPA and author of A Framework for Growth: Smart Financial and Tax Planning Strategies Throughout the Entrepreneurial Life Cycle.

“People often make the error of only worrying about taxes when it’s time to file,” Cordasco says. “By then, your taxes are pretty much locked in. Although you can’t avoid taxes, you can take steps to minimize them. But this requires proactive planning – estimating your tax liability, looking for ways to reduce it and taking timely action.”

And timely, he says, isn’t waiting until the week before the filing deadline. The real deadline for taxes in the United States – at least for taking action that could save you money – is Dec. 31 of the tax year, he says. (One exception is that you may be able to make a tax-deductible IRA contribution right up to the filing deadline if you meet certain criteria.)

Cordasco says some things to consider that can help you reduce the tax bill you will owe come April 2023, include:

“Bunch” charitable donations

Many people take the standard deduction when they file their taxes because that’s higher than their total itemized deductions. But Cordasco says you might benefit from “bunching” your charitable donations in alternating years, raising the amount you could itemize every other year. Here’s how that would work: If you make a large donation on Jan. 1 and another on Dec. 31, those donations are essentially a year apart, but they fall within the same tax year for itemizing purposes. In effect, you make two years worth of charitable donations in one tax year. Continue Reading…
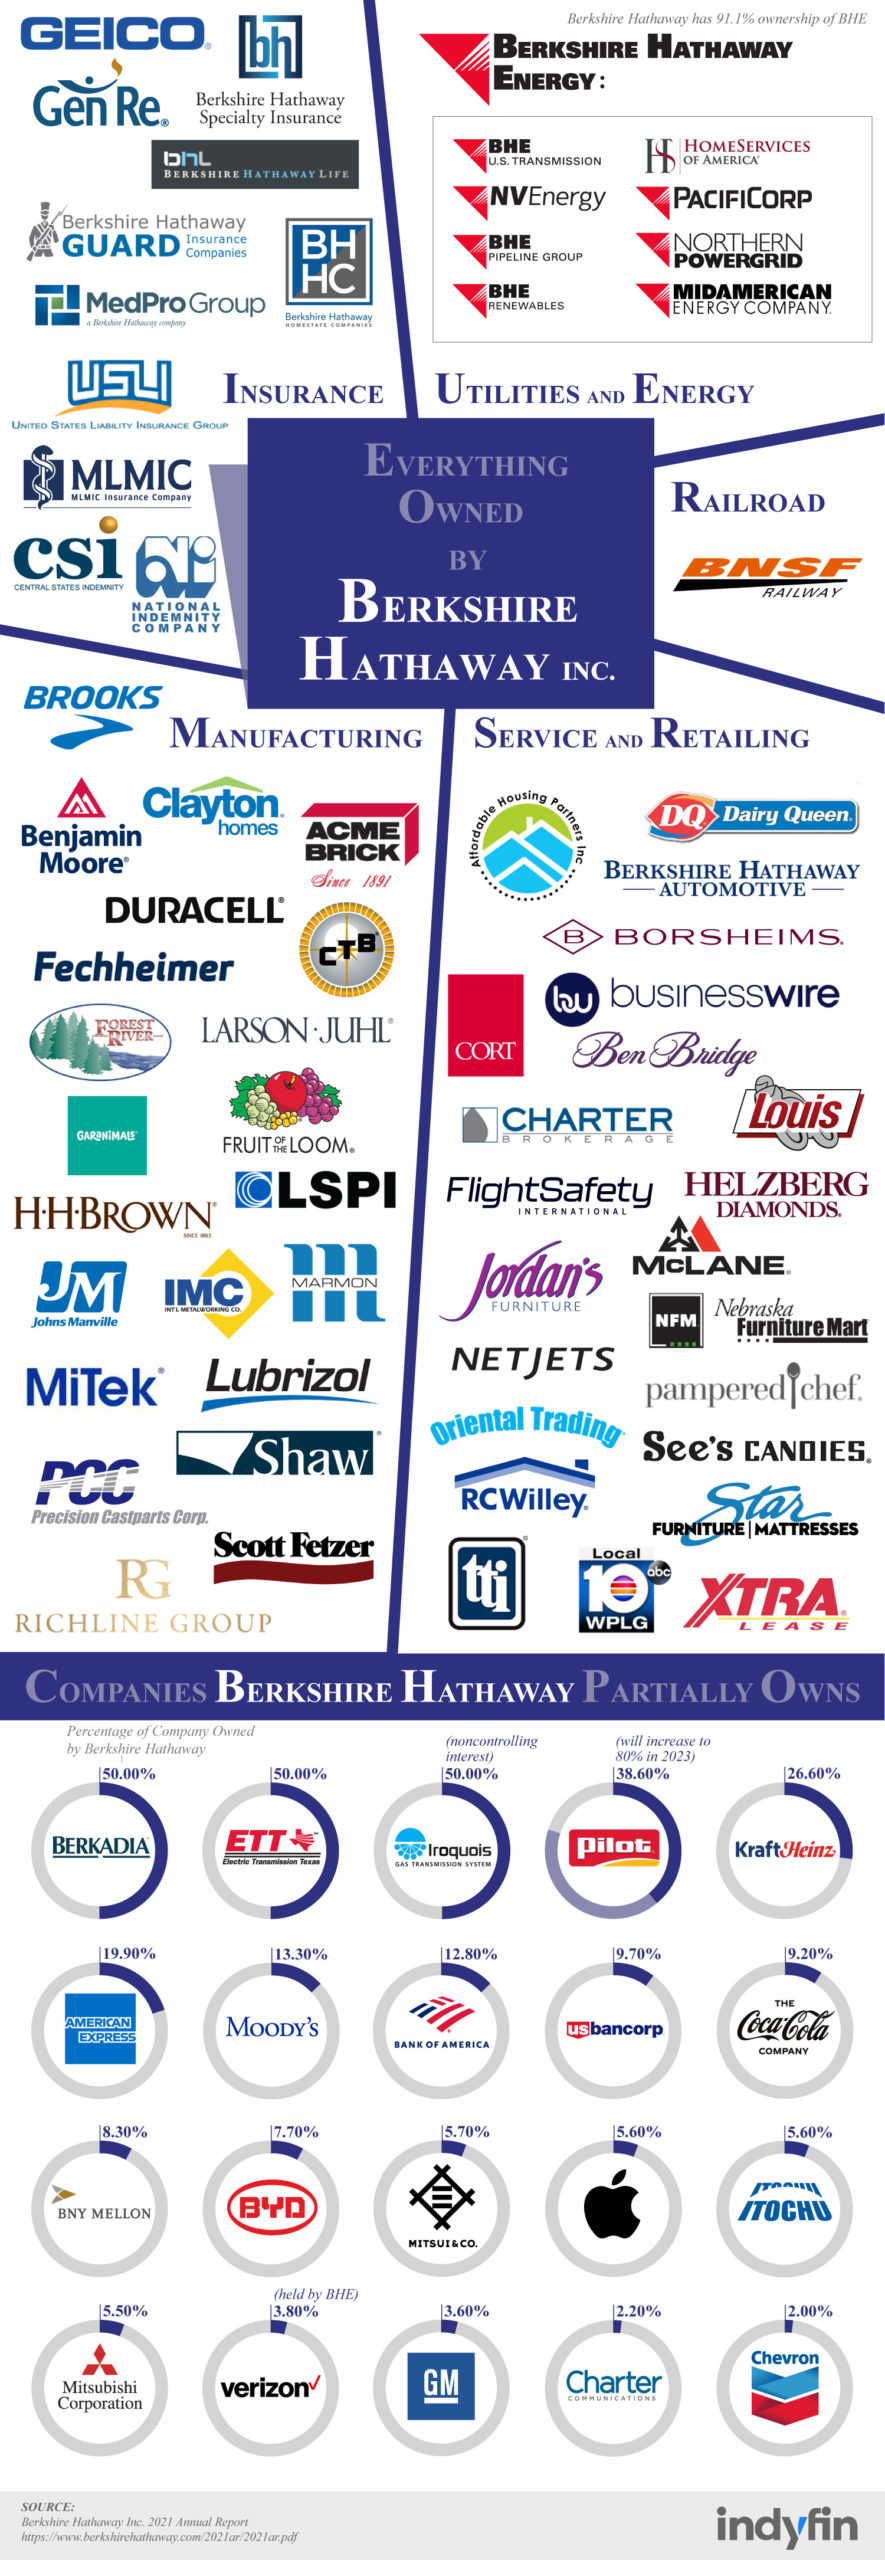
Everything owned by Warren Buffett’s Berkshire Hathaway

Warren Buffett of Berkshire Hathaway, which just held its first live annual meeting since Covid hit.

By Akshay Singh

Special to the Financial Independence Hub

You’ve probably heard of the multi-billion dollar company Berkshire Hathaway, owned by mega-billionaire and philanthropist Warren Buffett, but what does Berkshire Hathaway do exactly?

Berkshire Hathaway Inc. is a conglomerate holding company, meaning it does not produce goods or services and instead has a controlling interest in and owns shares of other companies to form a single corporate group.

That leads us to our next question: What companies does Berkshire Hathaway own to make it one of the most valuable companies on the planet? The team at Indyfin turned to the 2021 Berkshire Hathaway annual report to create this compendium of all of the Berkshire Hathaway companies. The holding company has a controlling interest in more than 60 companies and partially owns another 20 on top of that. You’ll recognize a lot of brand names from a wide variety of industries that make up the impressive Berkshire Hathaway portfolio.

Does Berkshire Hathaway own one of your favorite or most-used brands? Check out this roundup of Berkshire Hathaway companies from Indyfin to find out.

What Is Berkshire Hathaway?

Berkshire Hathaway is an American conglomerate holding company with a market cap of US$774.24 billion, making it the seventh most valuable company in the world. What is a conglomerate? A conglomerate is a combination of businesses from a variety of different industries that operate as a single economic entity under one corporate group. Conglomerates are usually large and multinational and generally include a parent company and many subsidiaries. The “conglomerate fad” was big in the 1960s due to low interest rates, rising prices, and a decline in the stock market, which led to large corporate conglomerates like Berkshire Hathaway forming. The parent company in this scenario is also referred to as the holding company, as it holds a controlling interest in the securities of all of the other companies. Holding companies do not produce goods or services; instead, they own shares of other companies to form a single corporate group. Holding companies are beneficial because they reduce risk for shareholders and can hold and protect assets like trade secrets or intellectual property.

What Does Berkshire Hathaway own? Continue Reading…

Why it might be time to rebalance the 60/40 Rule


Investors follow the 60/40 rule because they are told bonds will protect capital while equities grow it. Why recent drops in bond prices should make us reconsider that rule. 


By Paul MacDonald, CIO, Harvest ETFs

(Sponsor Content)

From the moment they start putting money in the market, investors are told to follow the 60/40 rule. It is the broadly accepted wisdom that, for an average retail investor, a 60% allocation to equities and a 40% allocation to bonds will result in a robust portfolio. Equities should deliver growth prospects in the long term while bonds will offset downsides in equities by delivering uncorrelated returns. Bonds preserve capital, and equities grow capital. That’s the accepted wisdom. 

Countless investment fund issuers have packaged this logic into their balanced funds. These funds offer a specific allocation to equities and bonds, usually in line with the 60/40 rule, forming the core of a retail investor’s portfolio.

The problem with accepted wisdom is sometimes circumstances turn it upside down. In the past months we have seen volatility in equity markets and a significant drop in bond prices. That is because the investment landscape has changed. 

Why are bond prices dropping? 

After over a decade of historically low interest rates, followed by massive rate cuts by central banks at the onset of the COVID-19 pandemic, inflation has begun to set in. With rising inflation comes pressure on central banks to raise rates and market expectation that rates will rise, which is itself pushing interest rates higher.  Continue Reading…

Why Canadian Small Caps should be a small part of your portfolio

We think that small caps should not make up the bulk of your diversified portfolio — but you can benefit from making the best Canadian small cap stocks a smaller part of your holdings.

We generally feel that most investors should hold the bulk of their investment portfolios in conservative securities from well-established companies. This means holding a total of 15 to 25 well-established, dividend-paying stocks, chosen mainly from our “Average” or higher ratings, and spreading your holdings out across most if not all, of the five main economic sectors.

However, some investors choose to add more aggressive or speculative stocks to their holdings in their pursuit of bigger, faster gains. That can involve holding some of the best Canadian small stocks.

Understanding how we look at the best Canadian small cap stocks

We recommend a number of small-cap stocks in our Power Growth Investor newsletter, and we comment on others in our Inner Circle mailings, in response to questions by members. We also recommend some higher-risk investments in our Spinoffs & Takeovers publication.

Our Aggressive Growth Portfolio selections in The Successful Investor and Wall Street Stock Forecaster tend to be more highly leveraged and more volatile than our Conservative recommendations, and they can give you bigger gains and bigger losses. Their higher risk may be due to financial leverage, or to the risks facing their industry or particular situation. Still, our Aggressive Growth stocks are typically less aggressive than the picks in, say, our Power Growth Investor newsletter.

We can be wrong on any of our stock recommendations, of course. When we’re wrong on an aggressive stock, losses are likely to be larger than on a well-established stock.

Ultimately, the percentage of your portfolio that you should hold in either conservative or aggressive investments depends on your personal circumstances. An investor with a longer-time horizon or without the need for current income from a portfolio can afford to invest some money in aggressive stocks.

We look at many stocks before singling out our aggressive favourites, and we try to choose those with as much underlying value and as many hidden assets as possible. This is the best way to cut risk for conservative and aggressive investors, alike. Continue Reading…

4 strategies for coping with rising Taxes

By Elke Rubach    

Special to the Financial Independence Hub    

While various government programs have helped many individuals and
businesses during the pandemic, the looming tax filing deadline of April
30th has Canadians facing the harsh truth about how much income they really generate, how much they spend and how much they owe in taxes in a year.

If you are concerned about the prospects of a rising tax bill and want to stay ahead of the curve, we highlight some tax strategies that may help.


4 Strategies for optimizing your taxes

Effective tax planning is highly dependent on your personal situation, so there is no one-size-fits-all solution. However, here are four strategies that may be useful in optimizing your tax situation:

Estate freeze

An estate freeze can be used to defer the realization of taxable capital gains in the value of a family business. After a properly structured freeze, any further growth in the company’s value will accrue not to the owner, but rather to their successors or to a discretionary trust set up as part of the freeze.

Estate freezes have many potential benefits, including locking in probate tax liabilities, locking in a purchase price for a business, providing retirement income and strengthening creditor protection.

Capital losses

Stock markets around the world have plunged during the pandemic, and despite some strong rebounds, many investors have stock portfolios with unrealized losses. In some situations, it can be beneficial from a tax perspective to sell holdings and trigger capital losses to offset capital gains.

Capital losses can be applied retroactively up to three years and carried forward indefinitely. However, there are restrictions on how such losses can be applied, so any decisions should be made with advice from a tax professional.

Prescribed rate loan

A prescribed rate loan allows individuals with high marginal tax rates to transfer investment income to family members with low marginal tax rates. Under this strategy, the high-income earner makes a loan to a family member or a family trust, which invests the money and earns investment income. The high-income earner receives interest payments at a rate prescribed by CRA (currently 1%) while the remaining investment income can be distributed to the family member(s) and will be taxed at their lower tax rate.

Spreading corporate losses

Owners with multiple businesses are not allowed to directly consolidate their profits and losses across their corporate group to minimize their overall tax bill. However, there are permissible tax strategies that can be used to spread at least some corporate losses and achieve similar outcomes. Management fees are one example, although there are restrictions on how this strategy can be applied. Continue Reading…