General

5 financial benefits of having a healthy lifestyle

By Morgen Henderson

Special to the Financial Independence Hub

Most of us have been given medical advice to eat healthier and get regular exercise, and there are certainly daily benefits to these choices, like feeling more energetic, having a better mood, and experiencing less pain. But we don’t always consider the financial benefits of a healthier lifestyle.

Although spending more money upfront on things like organic food and gym memberships or other fitness activities might seem like it doesn’t fit into a frugal financial lifestyle, the money you’ll save both in your monthly spending and in the long run makes the initial costs well worth it.

1.) Cheaper insurance later in life

When you get older, you may need life or burial insurance (if you don’t have it already), and being healthy will help you get better rates for your policy. Living in an unhealthy way may lead to health problems down the line. Although it’s still possible to get it, it can be more difficult to get funeral insurance for pre-existing conditions (also known as “final expense” and “burial” insurance). For instance, if smokers need insurance, but they now have lung cancer, it may be hard for them to find a policy, and if they do, it may cost them more.

2.) Lower health care costs

Health care companies often charge higher premiums for people with pre-existing conditions or chronic health problems such as hypertension and diabetes, and sometimes also for smokers. Beyond that, if you have a chronic health condition, you’ll need to pay more out of pocket for prescriptions, doctor visits, and medical treatments. While not all such conditions are preventable through healthy living, many common ones — diabetes, heart disease, certain types of cancers, and osteoporotic hip fractures, to name a few — are.

The World Health Organization found that “physically active individuals in the USA save an estimated $500 per year in health care costs.” That’s based on data from 20 years ago, so savings are even higher today.
unsplash

3.) Less spending on filler foods

Choosing whole foods over packaged, processed foods like chips and other snacks means you’re getting more nutrition for your dollars. Changing your snacking habits can help you do this. And adjusting portion sizes to meet what your own body needs will also help shave down your spending on food.

What’s more, cutting out other indulgences many people regularly consume, such as tobacco and alcohol, will save money each year that you can redirect to retirement savings or other investments. Healthier eating habits and reduced substance use will affect your budget now, and your health care costs later. Continue Reading…
Coping with the Costs of Covid-19

By Carrie Hunter
Special to the Financial Independence Hub

Our world, as we’ve known it, has changed dramatically over the last few weeks. Likely, forever.

If you have children, and like me live in Alberta, you can now add homeschooling to your c.v. You and your spouse are now living and working in this same space 24/7 practising the soon-to-be-normalized cultural rite of social isolation.

When you do step outside, gratefully breathing in fresh air, looking up as a neighbour passes and takes a step back, yet still cheerfully waving, you’re reminded again of the new normal: social distancing.

Back in your home, you open up your laptop only to be inundated with Covid-19 news headlines, across every possible platform, and overwhelmed by the inconceivable number of people being felled by the novel coronavirus.

The Zombie Apocalypse

Unsurprisingly, global financial markets, reflecting the fear, anxiety and uncertainty of investors, are in free fall — the TSX and S&P were down 34% and 32% respectively the week of March 20th — cliff-diving off record highs of just a month ago. Reporting of these numbers is closely followed with economists’ dire predictions of a recession once the Covid-19 crisis subsides. It’s surreal. I can’t shake the feeling I’m an extra in a Zombie apocalypse movie. If only.

How do we cope as the once relatively reliable world we knew, just a few short weeks ago, continues to experience seismic shifts that shake and loosen the very foundation supporting our lives?

Keep calm, Carry on

We can only control what’s within our reach. This is my mantra; only now, I repeat it several times a day. Here are  some tips to help cope with day-to-day changes:

Emergency Fund

Practically speaking, ensure you have an emergency fund. Typically, you’re looking to sock away three to six months of living expenses for the “just in case” scenario. Don’t have it now? Don’t panic. Take a good hard look at your monthly expenses and incorporate this savings target into your budget. Anticipating an income tax refund? Earmark a portion of these dollars and deposit them into a high-interest savings account. Preferably one that’s CDIC insured.

Resist the temptation to save for your rainy day with extra monthly dollars. There’s rarely spare change at the end of the month; be intentional, add this line item to your budget. Even a few dollars to kickstart the account will make a difference in the long run.

Budgets

Do you have one? If not, this is a great time to put one together. Track ALL of your expenses for a month or two. Do you see any trends? Any obvious places you can trim expenses? Make it happen.

One of my favourite hacks is around groceries and meal planning. Each week, I shop in my freezer and pantry compiling a list of recipes for the week. Not only does it take the stress out of meal planning (and save money on takeout), but it limits trips to the grocery store.

Financial Support

More than one million Canadians have now applied for Employment Insurance. You may find yourself without work; caring for a loved one battling Covid-19 or staying home with your children due to school or daycare closures. The federal government will be offering financial support for 16 weeks, beginning in April (the online portal is scheduled to launch on April 6th) and payments will be retroactive to March 15th, through its COVID-19 Economic Response Plan.

Managing your portfolio performance

I review our portfolio on a daily basis. It’s not really something I should do, and given the performance of the last month, it may be a habit I soon break.

The last month has been startling; I’ve watched our collective portfolios steeply decline, briefly ascend only to decline again. It’s unbelievably tempting to hop off the rollercoaster, almost primal, really, sell what remains and seek shelter on the sidelines. Continue Reading…

7 timeless strategies investors need to remember in this time of market turmoil

The world as we knew it suddenly changed. What a surprise beyond belief for all of us.

There was no announcement six months ago. There was no new or updated playbook for any of this upheaval.

A harsh pandemic is a sure way of turning lives upside down. Treacherous times are firmly entrenched as the new roadway.

Stock and bond markets march at will in both directions. Investors wonder whether they are closer to a market bottom or to a top. All sorts of fears and worries are sprouting everywhere.

This is a reminder for all to go slow: younger and older, novices and seasoned. Try your utmost to use all the investing common sense you can muster. Sitting on your hands is often a worthy move.

My strategies:

Accordingly, I have selected seven timeless strategies that every investor ought to be familiar with in detail. They form a solid foundation for guiding the family nest egg.

I’ve kept them brief and to the point for the sake of simplicity. Here is my summary of critical strategies:

1). Short term trading is best suited for your “speculative” money. Conversely, long term investing is the best fit for your “serious” money, such as funding retirement. These two portfolios are constructed differently, so don’t mix them.

2). Chasing returns has been far from a consistent winner. Instead, pay attention to acquiring broadly diversified “quality” investments. These portfolios typically fare better during bouts of market turmoil.

3). Set aside the could’ve, should’ve and would’ve schools of hindsight. Make your decisions based on available information and move forward. Looking back in your rear view only creates distractions you can’t do anything about.

4). Becoming attached to your stocks is akin to making emotional decisions. Instead, I recommend pursuing logical moves designed to embrace your best interests. Your investing success should improve.

5). Don’t make investment decision out of fears. Rather, wait until the coast begins to clear. You have absolutely no control over what happens to market fears.

6). Decide whether you seek the return “of” your money, or the return “on” your money. That strategy sheds light on the fit of your desired portfolio. It also keeps you better invested within a more comfortable asset mix.

7). Investing your money all at once is usually not a preferred strategy. Studies show that asset mix delivers the biggest impact on portfolio outcomes. Neither superior stock selection, nor timing of purchases are close seconds.

My premise:

My premise is that investing strategy need not be complicated. I recommend that the main ingredient is always plenty of patience combined with common sense. Focus on logical and sensible approaches that contribute to your discipline. Continue Reading…

Where are you parking your cash these days? GICs vs. High-interest savings accounts

Cash is king during times of economic trouble. Working families need emergency savings to pay the bills in case of job loss or a reduction in wages. Retirees or near retirees need a cash cushion to avoid selling stocks at a loss. But should you park your cash in a high interest savings account or a GIC?

For a short time, not too long ago, we lived in the golden age of high interest savings. The competition was lively, as online banks and credit unions pushed interest rates well above 2 per cent (LBC Digital briefly paid 3.3 per cent).

Rising interest rates on savings deposits made GICs look less attractive. GICs paid the same rates or lower, yet savers had to lock-in their deposits for 1-5 years. Where did the liquidity premium go?

High Interest Savings Account rates

The situation quickly changed when the coronavirus pandemic forced central banks to take emergency action and cut interest rates. The Bank of Canada lowered its key interest rates by 50 basis points on two occasions. The ripple effect caused high interest savings account rates to plummet.

LBC Digital had already lowered its rate to 2.8 per cent – now it sits at a still respectable 2.25 per cent. Wealthsimple Cash had arguably the worst-timed launch when it came out with a 2.4 per cent interest rate for its chequing/savings account hybrid. That rate was quickly dropped to 1.9 per cent, and then lowered again to 1.4 per cent.

EQ Bank lowered the interest rate on its Savings Plus account to 2 per cent, while motusbank dropped its rate to 1.75 per cent. What a difference a month makes!

Here are the top high interest savings account rates today (March 25, 2020):

Bank Interest rate
LBC Digital 2.25%
Motive Financial 2.20%
Implicity Financial 2.10%
Outlook Financial 2.10%
EQ Bank 2.00%
Oaken Financial 2.00%


As always, savers need to look beyond the big banks to maximize the interest earned on their deposits. If inflation averages 2 per cent, then you need to earn at least 2 per cent on your savings to maintain purchasing power. Even still, at best you’re treading water.

Despite the recent drop in rates, a high interest savings account is still the best place to park your emergency savings. You never know when you’ll need to access cash for an unexpected bill, or to pay for your living expenses during a period of unemployment.

A high interest savings account is also a must-have for retirees and near-retirees to stash one year’s worth of spending – the first bucket in the three-bucket approach to retirement income planning.

What this current rate crisis has highlighted is the fact that high interest savings account rates are not guaranteed. Those who eschewed GICs to chase higher yielding savings accounts now find their savings account paying 0.50 – 1.00 per cent less than it was a month ago. Not ideal.

GIC rates

One of my clients recently alerted me to an email sent by Oaken Financial advertising an increase in GIC rates. Its one-year GIC now pays 2.5 per cent, which is a full 25 basis points more than the top-paying high interest savings account. Oaken’s five-year GIC now pays 2.95 per cent interest. It looks like the liquidity premium is back.

You’ll easily find one-year GIC rates paying at or above the best high interest savings account rate.

Bank Interest rate
Oaken Financial 2.50%
Canadian Tire Bank 2.50%
EQ Bank 2.40%
Wealth One Bank of Canada 2.40%
Peoples Trust 2.30%


Longer-term rates vary widely so be sure to shop around for promotions. Here are the top five-year GIC rates as of this writing:

Bank Interest rate
Oaken Financial 2.95%
Wealth One Bank of Canada 2.60%
Canadian Tire Bank 2.55%
EQ Bank 2.55%
Peoples Trust 2.55%


Readers should know that GICs are typically non-redeemable, so you should be absolutely certain that you won’t need the money when you lock it in for 1-5 years.

That means GICs are ill-suited for an emergency fund, but ideal for a goal with a specific time period.

Using High Interest Savings Accounts and GICs for Retirement Income

For retirees and near-retirees, GICs are best-suited for “bucket two” in your three-bucket approach to retirement income. Bucket two is where you build a GIC ladder with three to five years of annual retirement spending. Continue Reading…

Aman Raina’s 5-year Robo advisor review — and how Robos are holding up in the bear market

By Aman Raina, SageInvestors.ca

Special to the Financial Independence Hub

NOTE: This review was initially undertaken using data compiled as of January 30, 2020, which marked the 5-year anniversary during which the portfolio was active but prior to the severe market turbulence that occurred in February and March 2020.  As it became apparent that the market pullback was becoming an epic meltdown, additional data was compiled and included into the review.

Five years ago I embarked on a personal experiment. I was having a hard time getting any insights on the effectiveness of a new investment services that was shaking the ground at the time in 2015.

Known or labeled as Robo Advisors, these new wealth management companies offered services to invest on behalf of others using an online platform and a combination of algorithms and computer coding to buy and sell specific investments and manage portfolios. Five years ago these firms were just stepping into the investing consciousness, but since then they have mushroomed and even traditional investment companies are now offering some flavor of online investment management services.

It all seemed quite appealing; however, there was one thing that many marketing materials, blogs, and mainstream media were avoiding … do these types of services make money for investors? Is this the type of service that would successfully bring more people, who naturally feel intimidated and frustrated by the whole investing concept into the investing domain?

Since no robo advisor company back then was interested in disclosing their performance (they still avoid it) other than citing research that their low cost/passive oriented strategy is superior, I decided five years ago to try an experiment to get some more insights that did not involve boilerplate marketing speak. I set up an account with one of the “large” Robo Adviser firms and invested $5000 of my own money into it.

My goal was to go through the process and blog about my experience using the service, how the ROBO went about making decisions and how it managed my portfolio, and more importantly, the results. I’ve always said that we need a good five years to really get a handle on how effective these services are compared to traditional wealth management services. Well, I just crossed the five-year mark of my ROBO journey, so let’s check back in and take a look at how it’s been doing. I’ve also said that I would reserve my opinions about this service until we reached that five-year threshold. Well here we are and I’m ready to unload my takes.


2019 was an epic year for stocks. US major stock indexes were up just over 30 per cent on the year. Fantastic returns. Hopefully my ROBO got a good piece of that action.

Performance

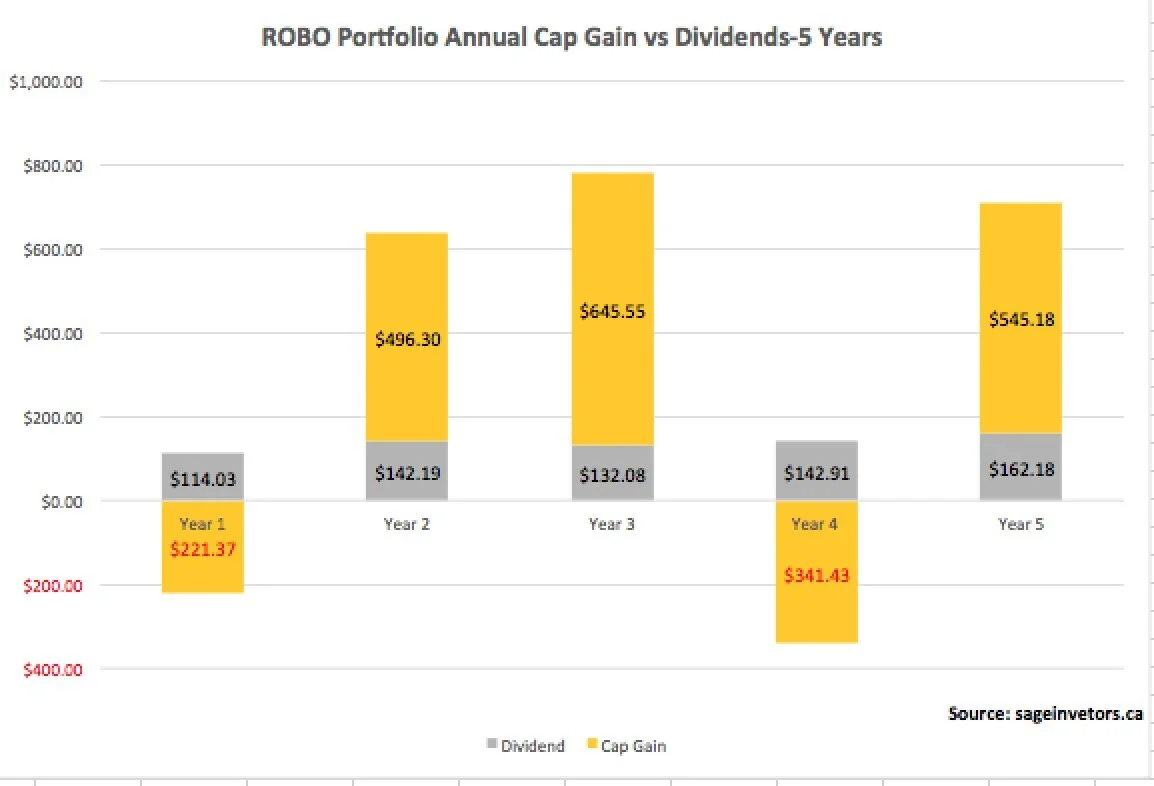
Overall, my ROBO portfolio posted a solid year. The portfolio was up 11.6 per cent year over year, a nice rebound from the previous year where it lost 2.1 per cent. Over the 5 years, the portfolio generated positive returns in three of the 5 years, and posted double-digit returns in those three years. The portfolio increased by $707, of which $162 came from dividend income while the remaining $545 came from capital gains. Over the year period, the ROBO portfolio increased from my initial $5000 to $6817, a cumulative return of 36 per cent. Of the $1817 increase, 1/3 was from dividends while the remainders was from capital gains. The portfolio continued to benefit from higher concentration of US and Canadian equities, which again hit it out of the park the past year.

ROBO Annual Return Chart.jpg
ROBO Cap Gain vs Dividend Chart.jpg

Below is the breakdown of the portfolio. Five years ago when I set up the account I answered a series of questions about my financial literacy and risk tolerance. ROBO took my responses and crafted a portfolio that it felt was compatible with my profile. Continue Reading…