General

Retired Money: What to do about falling GIC rates

PWL Capital’s Ben Felix

My latest MoneySense Retired Money column has just been published. It looks at the reversal the past year in interest rates, which impacts seniors who had started to look forward to at least half-decent GIC rates near 3%. You can find the full piece by clicking on the highlighted headline: Are GICs right for retirees looking for Fixed Income? 

Short of embracing high-yielding dividend paying stocks, the more palatable alternative for conservative retirees might be fixed-income ETFs. The article focuses on a recent video by CFA Charterholder Benjamin Felix, an Ottawa-based portfolio manager for PWL Capital. Felix argues that at a minimum such investors should have a mix of both fixed-income ETFs and GIC ladders.

The latter let you sleep at night because they are invariably “in the green” in investment accounts. But while in the short term fixed-income ETFs can be in the red — just like equity ETFs — Felix makes a compelling argument for the higher potential returns of bond ETFs.

Felix believes that what really matters for investors is total return: “Holding a lower-rate GIC after a rate increase still results in an economic loss.” Bond returns consist of principal, interest payments and reinvested interest, so focusing only on return of principal misses the point. Individual bonds are not ideal for individual investors, as they require extensive research, are relatively expensive and tricky to trade.

Short-term GICs miss out on the term premium
But short-term GICs miss out on the term premium, which is substantial over time. Going back to 1985, Felix says short-term bonds returned 6.51% annualized versus 7.97% for the aggregate bond universe (which includes some short-term bonds).  This shows how much mid- and long-term bonds bring up the overall return. To be clear, this period captures one of the greatest bond markets in history but Felix says it is still reasonable to expect a relationship between riskier longer-term bonds and higher expected bond returns. Risk and return should be related.

GICs are also illiquid, so even if an investor chooses to include GICs in a portfolio, they will generally also include bond ETFs, which – like stock ETFs – can be sold any trading day. Nor do GICs provide exposure to global bonds.

Of course, a nice alternative are those asset allocation ETFs we have often discussed on this site. See for example this excellent overview by CutthecrapInvesting’s Dale Roberts: Which All-in-One, One-Ticket Portfolio is right for you? 

The Felix video can be found at his Common Sense Investing YouTube series here.
 

No surprise: the best retirement investments are the same as for everyone else

We recommend that you base your investing for retirement on a sound financial plan relying on the best retirement investments.

One thing investors of all ages fear is not having a good financial plan in place so they have enough retirement income to live on once they’ve stopped working. Looking for the best retirement investments, addressing this concern is usually a high priority for many of our Successful Investor Portfolio Management clients.

Four key factors to consider when investing for retirement

  1. How much you expect to save prior to retirement;
  2. The return you expect on your savings;
  3. How much of that return you’ll have left after taxes;
  4. How much retirement income you’ll need once you’ve left the workforce.

Our portfolio diversification approach gives you strong potential for long-term gains  

If you diversify as we advise, you improve your chances of making money over long periods, no matter what happens in the market.

For example, manufacturing stocks may suffer if raw-material prices rise, but in that case your Resources stocks will gain. Rising wages can put pressure on manufacturers, but your Consumer stocks should do better as workers spend more.

If borrowers can’t pay back their loans, your Finance stocks will suffer. But high default rates usually lead to lower interest rates, which push up the value of your Utilities stocks.

As part of their portfolio diversification strategy, most investors should have investments in most, if not all, of these five sectors. The proper proportions for you depend on your temperament and circumstances.

For example, conservative or income-seeking investors may want to emphasize utilities and Canadian banks in their portfolio diversification, because of these stocks’ high and generally secure dividends.

More aggressive investors might want to increase their portfolio weightings in Resources or Manufacturing stocks. For example, more aggressive investors could consider holding as much as, say, 25% to 30% of their portfolios in Resources.

However, you’ll want to spread your Resource holdings out among oil and gas, metals and other Resources stocks for diversification and exposure to a number of areas.

Stick with conservative estimates to account for unforeseen setbacks

As for the return you expect from investing for retirement, it’s best to aim low. If you invest in bonds, assume you will earn the current yield; don’t assume you can make money trading in bonds.

Over long periods, the total return on a well-diversified portfolio of high-quality stocks runs to as much as 10%, or around 7.5% after inflation. Aim lower in your retirement planning — 5% a year, say — to allow for unforeseeable problems and setbacks.

Above all, it’s important to remember that while finances are important, the happiest retirees are those who stay busy. You can do that with travel, golf or sailing. But volunteering, or working part-time at something you enjoy, can work just as well. Continue Reading…

7 tips for speeding up the day you burn your mortgage

By Barry White

Special to the Financial Independence Hub

Mortgage payments can be a huge drain on your budget, particularly if it accounts for a significant part of your income. Apart from the interest you will be paying on the principal, mortgage repayments can be a hindrance to your other long-term financial goals. Not only can paying off a home mortgage early help you save thousands of dollars but it will also help you to gain your financial freedom earlier. If you have made up your mind and eager to pay off your mortgage early, here are seven helpful tips you can implement.

1.) Pay extra on your repayment each month

Making extra payments each month is the easiest way to help lower your debt on the property. Whenever you make your monthly mortgage repayment, most lenders allow borrowers to make an extra payment and mark it as “principal only.”  This implies that the extra payment pays down only the principal instead of both the mortgage principal and the loan interest.

Assuming you have a monthly loan repayment amount of $1,346, you can decide to round it up to $1,400. The extra $54 is dedicated as a repayment on the principal. This simple act of extra payment can save you lots of interest charges as well as helping you clear your loan ahead of schedule (since the principal payments will add up faster than you’d think). Therefore, plan to add as much as possible to these payments to help with the principal plus lower the amount of total payments owed. Looking for ways to find extra cash to put on your mortgage? You can use bonuses or apply raises from your job.

2.) Pay more than Monthly, bi-weekly

A bi-weekly mortgage is when you make a payment that equals exactly half of the total monthly repayment every two weeks. This consequently shortens the time to pay off. For instance, if your normal mortgage repayment per month is $1,000, you would instead pay $500 every two weeks. This has almost a similar impact on your budget as one monthly payment. But with the 52 weeks in one year, a bi-weekly payment schedule will bring about a grand total of 13 full monthly payments each year instead of the usual 12. You’ll conveniently be making an extra payment yearly without scrounging around for the extra money.

3.) Make one big extra payment each year

Another great way to repay your mortgage early is to deliberately make an extra payment in a month every year. This helps you settle your mortgage faster, and chances are you wouldn’t miss it.  You can schedule the payment for a month when you hardly have any larger expenses, like during holidays. Of course, this technique requires extra discipline from you since you will need to save that payment. To be on the safe side, you can automatically transfer a little amount every month into a dedicated account for an extra mortgage payment.

4.) Divert “free” money towards your mortgage

Did you receive a tax refund or Christmas bonus from work? Divert that extra money that cannot be accounted for in your budget to your mortgage pay-off fund. Continue Reading…

How Property Investment can help you reach Findependence (Financial Independence)

By Rebecca Lee

Special to the Financial Independence Hub

Financial Freedom is a way for anyone to escape the grind of the 9-5 work life to live the life they desire without relying on anyone else for money. Almost all of us trade our time for money to pay our bills, eat, travel and live in general. Without trading our time, it would be impossible to pay for the things we need and want. Many of us are stuck doing this until we have just enough to retire late in life.

Those who find financial freedom, AKA Findependence, do so by acquiring assets that generate wealth on their own. As the saying goes, “don’t work for your money, make it work for you.” One of the most popular types of these assets is real estate. Here’s how you can achieve financial freedom through real estate investment.

Have a strategy

Financial freedom, what it is and how to achieve it is different for everyone. Everybody has their own needs and wants and will require a different amount of cash flow to live on. Therefore, you must have a personalised strategy based on your income, savings and liabilities.

Without a plan, you won’t know what opportunities to take advantage of and what ones to pass up on. A strategy that’s designed for you will help take the emotions out of your decisions, avoid making mistakes and minimise risk.

Get the mindset

Wealth creation and investing requires a certain mindset to be successful. A lot of people are selling “Get rich quick” schemes but unless you get super lucky, this is not a realistic approach. Real estate in particular is a long-term investment game.

Real estate investors understand that their wealth will grow not overnight, but over years of gradual growth. Understanding this and knowing yourself enough to be able to commit to such a long-term plan is key to reaching financial independence. Investing in real estate isn’t as simple as buying property and waiting for its value to grow. Continue Reading…

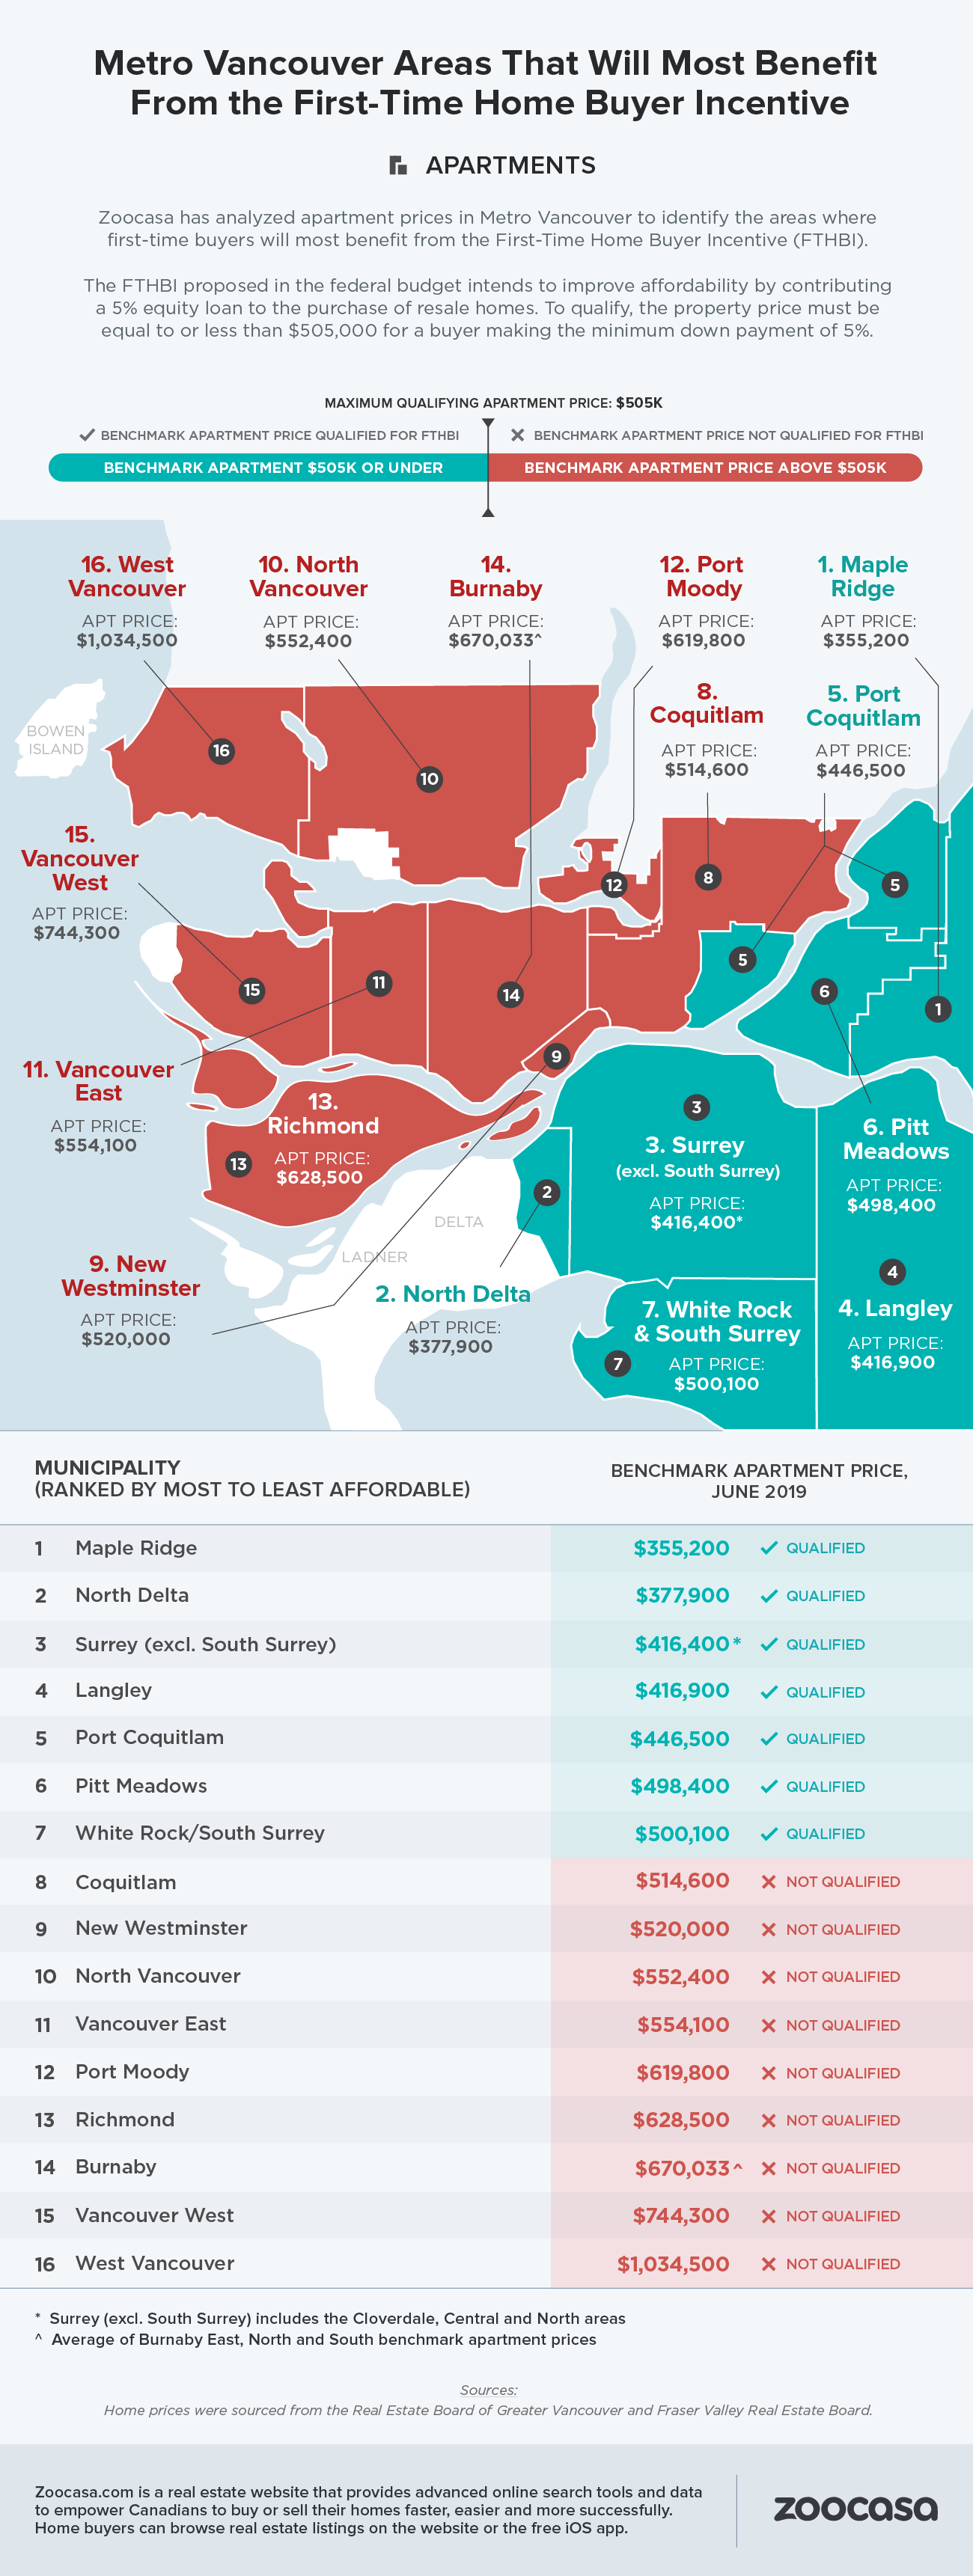
Could the First-time Home Buyer Incentive be used in Canada’s largest markets?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

When the federal government announced in March that it would be wading into the shared equity mortgage market in efforts to improve home buyer affordability, it stirred up some controversy.

The program, called the First-Time Home Buyer Incentive (FTHBI), was teased in the budget as a ground-breaking approach to helping buyers get into the market by providing interest-free down payment loans of 5% for resale homes, and up to 10% on brand-new builds.

In exchange for the upfront funds, which are designed to reduce the overall size of the mortgage and monthly payments, the Canada Mortgage and Housing Corporation (CMHC) will take an equity percentage the homes’ value, which must be paid off when either the mortgage matures, or the home is sold.

This paid-back amount fluctuates along with appreciation and depreciation in the market. For example, let’s say the CMHC provides a 5% loan of $25,000 for a home purchase of $500,000. The homeowner sells the home several years later, and its value has increased to $550,000. The homeowner would then need to pay the CMHC back $27,500 to reflect 5% of the increased value of the home.

Critics say FTHBI too restrictive to be effective

Mortgage analysts have called the effectiveness of this equity sharing program into question, as the total amount owed to the government could be significantly more than what was loaned in the first place, especially in a market that experiences rapid price growth.

However, the most contested features of the FTHBI are its mortgage and purchase price restrictions, which critics say render the program useless in markets like Toronto and Vancouver where home buyers arguably need the most help. Continue Reading…