General

Small Business: 5 tips to help protect your customers’ data and keep their trust

Photo Credit: Unsplash

By Gloria Martinez

Special to the Financial Independence Hub

When it comes to running a business, trust is key. If a customer cannot trust your company with the information they provide, they will eventually stop coming back, and your reputation will suffer.

Data protection is one of the most essential qualities of any successful company, whether it’s a small online clothing boutique or a Fortune 500 company. Though keeping data safe can be challenging in a time where cyber crime is rampant, there are practices you can implement in your business that will decrease the likelihood of an attack. If you’re a small business owner, these 5 tips will help you protect your customers’ data while ultimately benefiting your profits:

1.) Understand your obligations

While keeping your customers’ data safe is a key element of building and maintaining your company’s success, there’s another important reason you should prioritize it: you could be legally obligated to do so. Take the NYDFS Cybersecurity Regulation, for instance, to which many companies in New York must adhere. One of the requirements of the regulation is that certain businesses operate with an infrastructure that protects customers from cyber security threats. If you’re not sure whether or not your state has regulations like this, this article may provide you with more information.

2.) Use encryption

A lot of cyber attacks happen through emails. This is because a company’s email account is a prime target for hackers, and you need to make sure that any emails that are exchanged between your company and another party (including promotional ads) are protected from these attacks. That’s where encryption comes in. Using a modern email encryption service should work seamlessly into your email platform, and will help keep the business information contained in your emails (including customer data) from getting to anyone but the intended recipient.

3.) Develop a security policy

While software is indispensable in the battle against cyber crime, your efforts can’t stop there. Your business also needs a data security policy in place, whether you have one employee or 1,500. It’s critical that employees become familiar with the policy, as well as the roles played by all people and systems involved. Also, ensure that each employee completes any necessary training with software and/or security professionals. That way, everyone will understand how to adequately handle company data. Continue Reading…

Challenging conventional investment wisdom

By Noah Solomon

Special to the Financial Independence Hub

Many investment professionals tell their clients:

  • That markets tend to rise over the long-term.
  • To “hang in there” and “sit tight” during bear markets because they will eventually recover their losses.

While we agree with the first assertion, we wholeheartedly disagree that investors should sit idly through bear markets based on the notion that they will eventually live to see a better day. Rather, we strongly believe that a dynamic approach that adjusts to changing markets can provide superior long-term results.

The table below illustrates this by showing what happens to $1M invested in two different portfolios:

Portfolio A Portfolio B
Year 1 -30% -5%
Year 2 +30% +5%
Year 3 -30% -5%
Year 4 +30% +5%
Sum of returns 0% 0%
Value at end of year 4 $828,100 $995,006


Since the returns over four years add up to 0% for both portfolios, many people assume that the final value of each portfolio at the end of year 4 should be $1 million. However, as the last line in the table indicates, this is far from true.

Portfolio A, which is more volatile, declines in value by $171,900, while portfolio B, which is less volatile, suffers a decline of only $4,994.

The observation that two portfolios can have the same sum of returns over 4 years yet have significantly different values at the end of the period can be explained by the mechanics of compounding. After experiencing a 30% loss, a $1 million portfolio is worth only $700,000. Unfortunately, a subsequent 30% gain will only bring the value of the portfolio back to $910,000, which is still $90,000 less that its starting value. However, when a $1 million portfolio experiences a 5% loss, its value is $950,000, and a subsequent gain of 5% will bring its value up to $997,500, which is only $2,500 less than its starting point. Continue Reading…

An Investor’s playbook for Bitcoin’s resurgence

By Mauricio Di Bartolomeo

Special to the Financial Independence Hub

Bitcoin’s price has more than doubled over the last four months: from approximately USD $3,400 in February to a current price of USD $10,700 at the time of writing. While it is unreasonable to attribute the recent price increase to any particular news or headline, there are growing narratives and investment thesis that support making an investment in Bitcoin as a digital and apolitical store of value.

As some of us in the industry have come to expect, the runup in price has unsurprisingly led to renewed media coverage which, in turn, leads to thousands of new people looking to learn about Bitcoin and a desire to participate in the market.

For those currently invested in Bitcoin, or those interested in getting involved, here are five tips on navigating the “Bitcoin craze” with ease:

1.) Know where to buy your Bitcoin

When making your first Bitcoin purchase, make sure you use a trusted and compliant exchange. Avoid using exchanges registered in foreign jurisdictions or exchanges that don’t comply with your local jurisdiction. Bitcoin prices can differ between exchanges, they can also have different fee structures. Exchanges like Bull Bitcoin provide simple and fast platforms to buy Bitcoin. They are a non-custodial exchange so you will need to have your own wallet or a savings account to send the bitcoins to once you make the purchase. The next tip will guide you on how to get one.

2.) Know how to store your Bitcoin

In the past, some exchanges have been the target of hack and theft due to the need to keep Bitcoin ‘online’ for trading purposes.  After purchasing your Bitcoin, make sure you know how to keep it safe. You can use a hardware device such as a Ledger or Trezor that you can manage yourself: be sure to read the instructions carefully when setting up your device. If you want a simpler approach to keeping your bitcoin safe, you can use a third party custodian like BitGo that keeps your bitcoin safe through insured custody, or deposit your bitcoins in a savings account to earn interest. More on that below.

3.) Do more with your Bitcoin

The best way to make more out of your Bitcoin is to use a Bitcoin Savings account that pays interest on your Bitcoin deposits. Earning interest helps you grow your bitcoin position:  which can appreciate in dollar terms over time. There are only a few compliant companies worldwide offering this type of service: when searching for options, look for the compliant companies offering these services in your jurisdiction. Continue Reading…

Franklin Templeton adds pair of actively managed Fixed Income ETFs

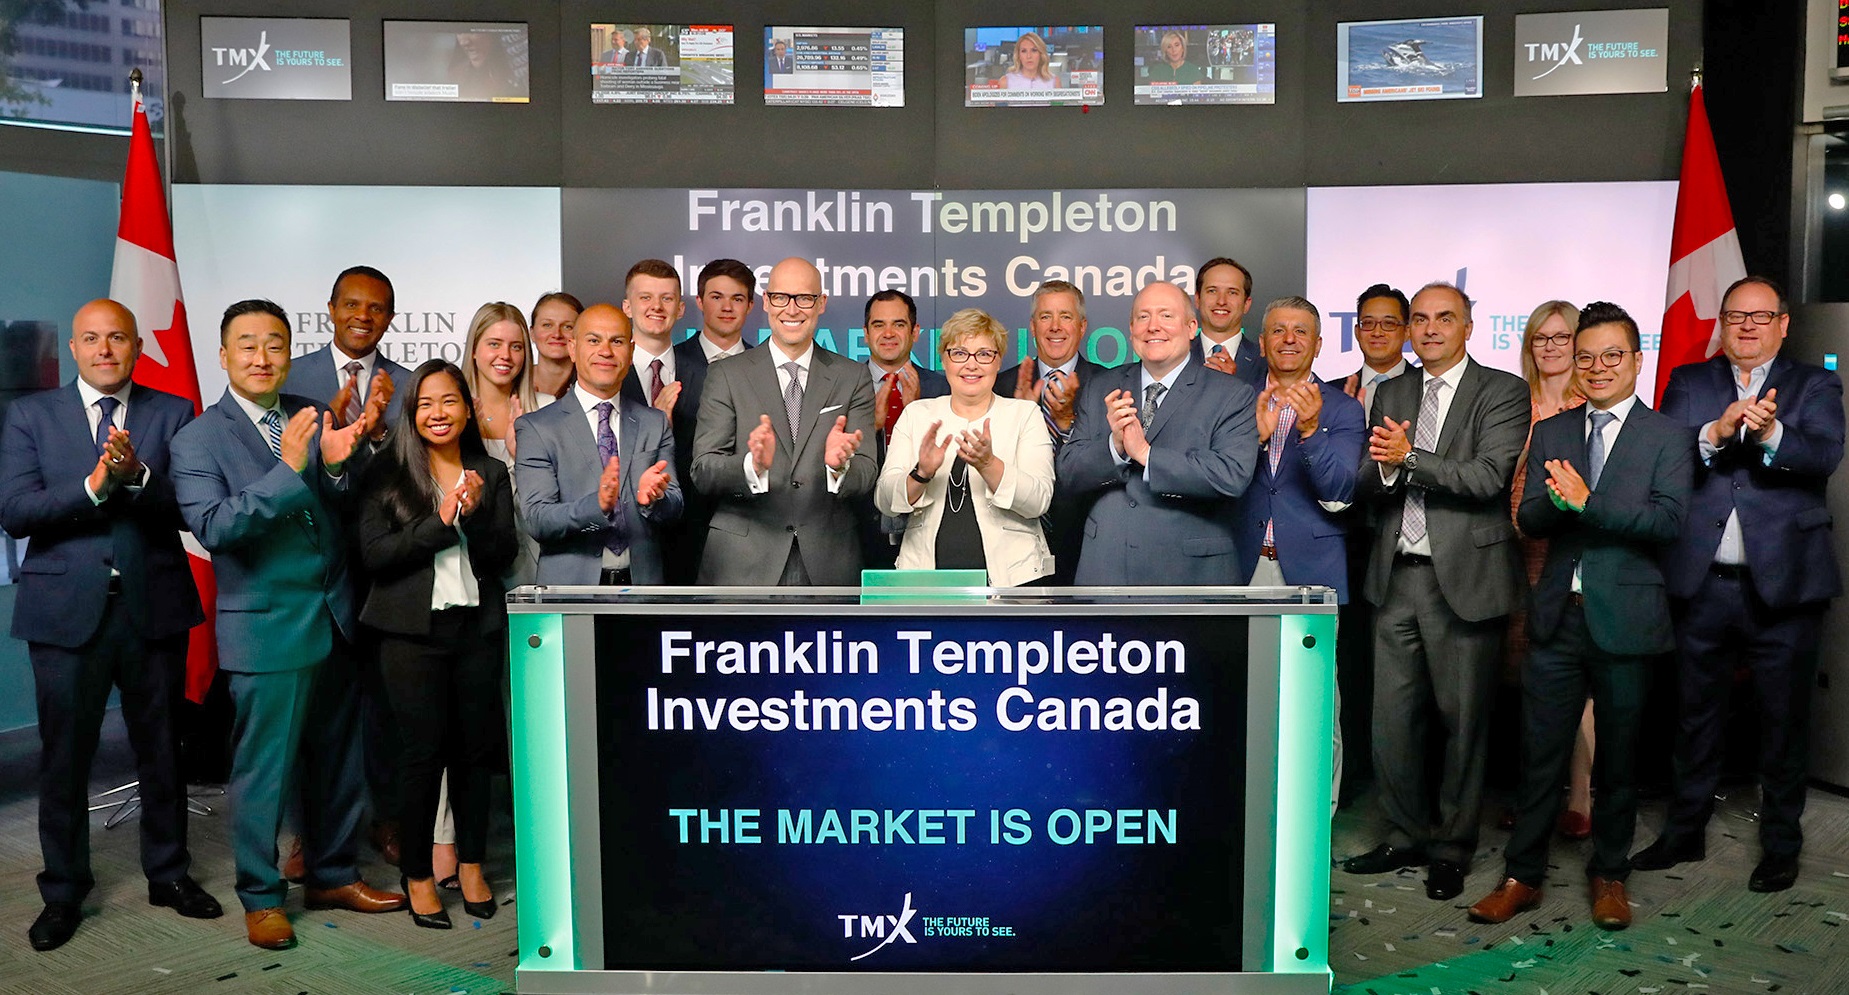
Franklin Templeton staff at opening bell of TSX Monday to launch two more actively managed bond ETFs

Franklin Templeton Canada has announced the launch of two new actively managed fixed income ETFs that will invest directly in two Franklin Bissett mutual funds. Franklin Templeton’s employees rang the Toronto Stock Exchange’s opening bell on Monday morning (July 8) to celebrate the listings of the new funds.

“Investors are looking for actively managed fixed income to provide stability in their portfolios,” said Duane Green, president and CEO, Franklin Templeton Canada in a press release. “Now they can access the compelling, risk-adjusted returns of our Franklin Bissett fixed income mutual funds in either an ETF or mutual fund structure depending on what works best for their portfolio.”

Franklin Liberty Core Plus Bond ETF (FLCP) invests in series O of Franklin Bissett Core Plus Bond Fund, with a management and administration fees totalling 55 bps. It seeks to provide high current income and some long-term capital appreciation through exposure to primarily Canadian fixed income securities, including federal and provincial government and corporate bonds, debentures and short-term notes. The fund is co-managed by Tom O’Gorman, SVP and director of fixed income, Franklin Bissett, and Darcy Briggs, SVP and portfolio manager, Franklin Bissett. They have 29 and 25 years of industry experience, and eight and 14 years with the firm, respectively.

Franklin Liberty Short Duration Bond ETF (FLSD) invests in series O of Franklin Bissett Short Duration Bond Fund.The management and administration fees total 40 bps. The fund seeks to provide income and preservation of capital through exposure to primarily Canadian fixed-income securities, including federal and provincial government and corporate bonds, debentures and short-term notes. The fund is co-managed by Darcy Briggs and Adrienne Young, VP and director of credit research, Franklin Bissett.

You can find more information on the new bond ETFs at Franklin Templeton’s website, here.

Banking shouldn’t be complicated

By Rick Lunny, Manulife Bank

Special to the Financial Independence Hub

 As a father of five with two 20-something daughters who recently moved out, I often hear how the sheer amount of information in this digital age overwhelms those who are entering the workforce and starting their adult lives. Somehow by default, I have become an unofficial mentor for both my kids, and their broad circle of friends, as they regularly seek my advice when facing important financial and career decisions that will shape their future.

They frequently comment how there’s always new, conflicting advice on how best to live life. Especially when it comes to money and how to make the most of it: save more, live for the moment, pay down debt, and yes, even plan for retirement at age 24.

It’s a struggle to find time to break through the noise and choose the best financial options that truly fits their needs.

And it’s not just the younger generation who struggle to make decisions and take control of their finances.

As the head of Manulife Bank, a subsidiary of Manulife which serves seven million Canadians, I know customers of all ages are looking to develop better financial habits and improve their financial wellbeing.

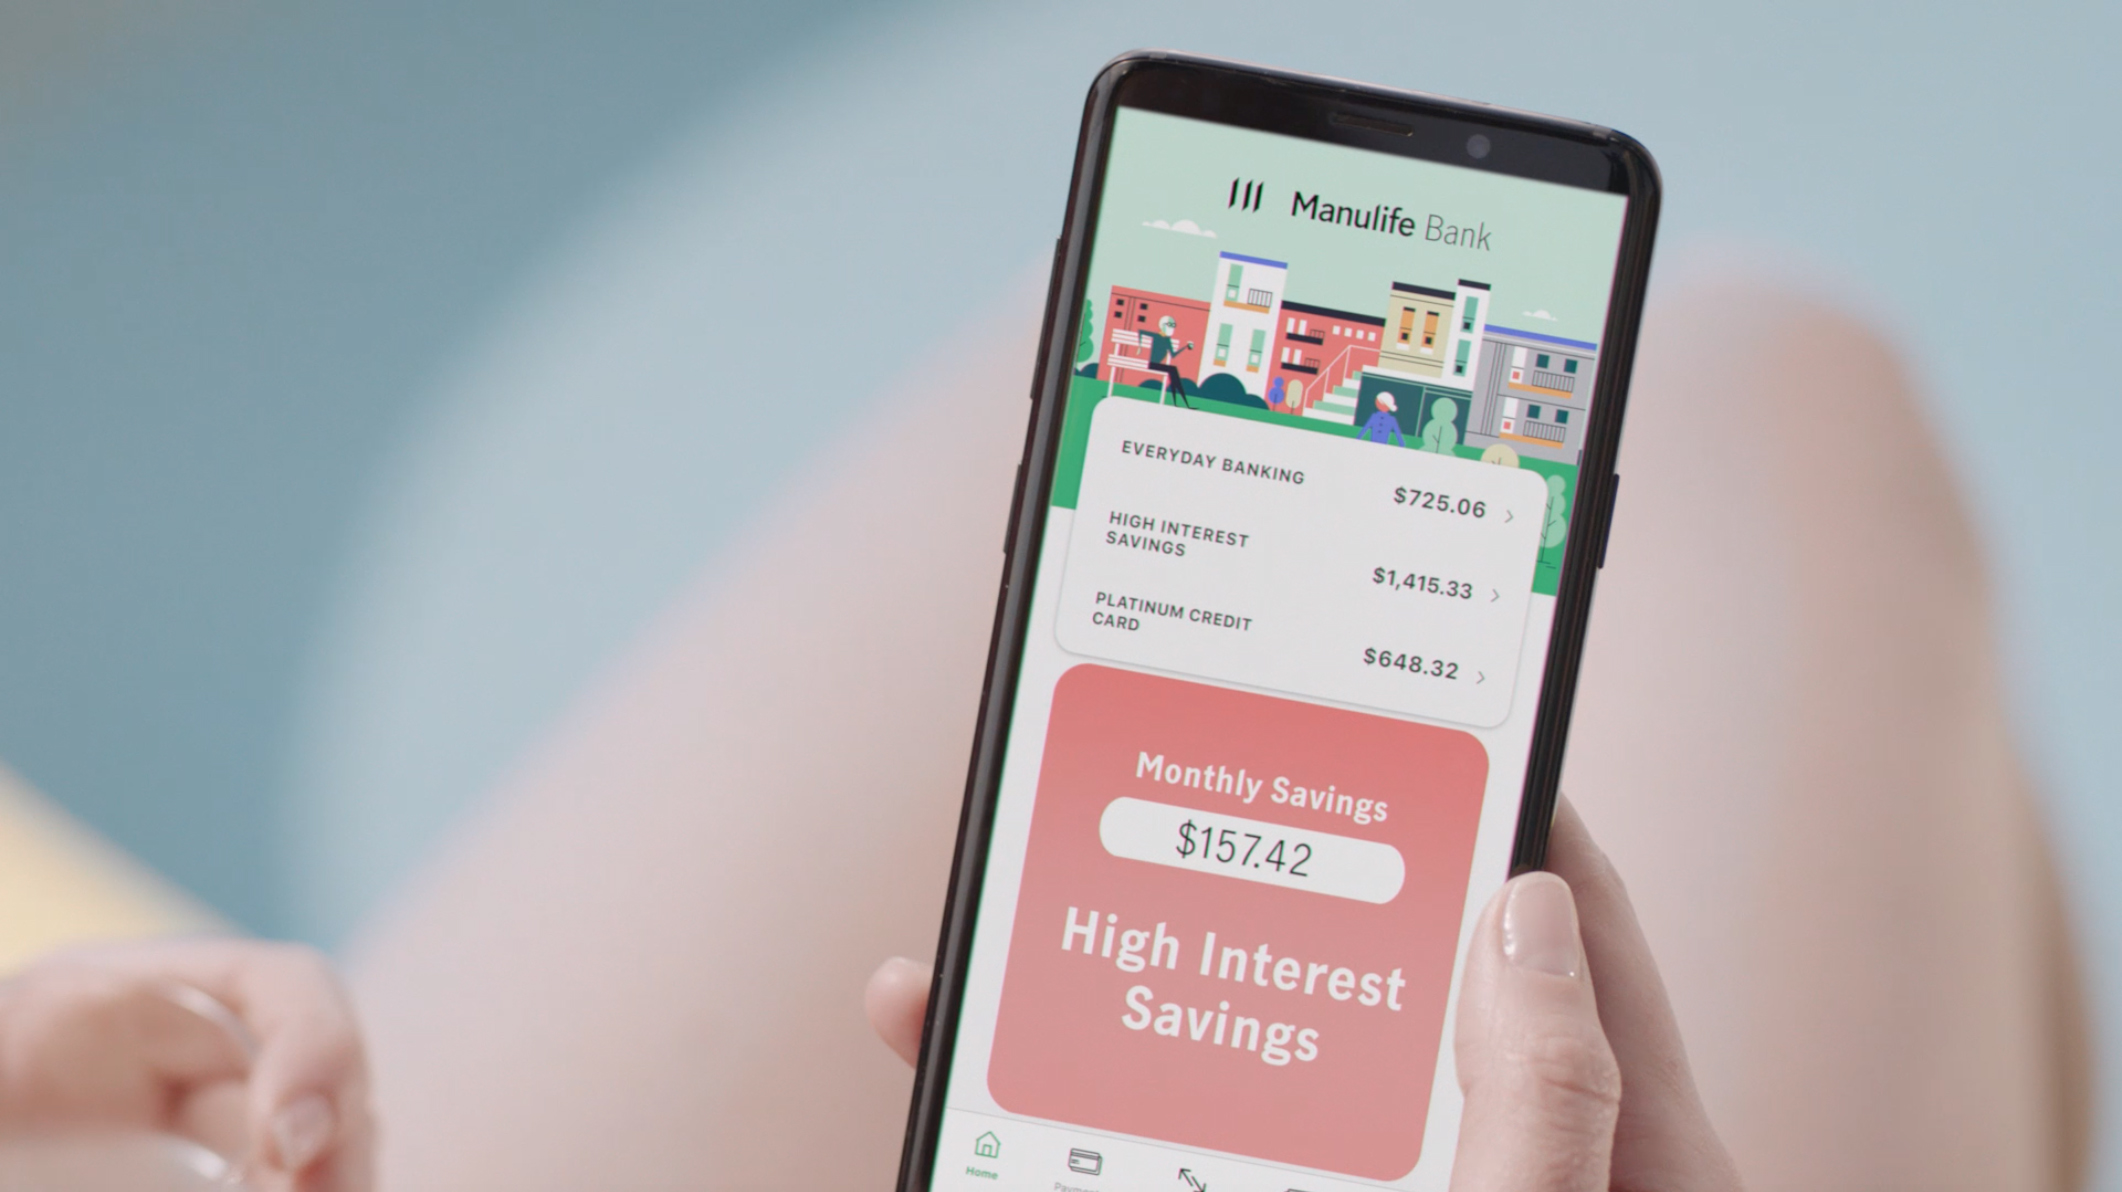
Canadians are looking for clarity, simplicity and value from their bank. This applies equally to technology interfaces. They expect – and deserve – from initial application to ongoing experience, products that have a human-centric design, with intuitive and easy to use interfaces.

That’s what I love about Manulife Bank. I joined five years ago because it was different from other Canadian banks. It had an entrepreneurial reputation for going beyond the status quo with innovative banking products designed in the best interest of Canadians.   Continue Reading…