General

Retirees can sell most of their stocks as they approach Retirement

By Dale Roberts, for Boomer & Echo

Special to the Financial Independence Hub

Retirement can be a scary time for retirees who have considerable and even modest portfolios. We want to protect those assets. And certainly the risk tolerance level for most retirees will drop considerably. And that risk tolerance level will often drive the bus with respect to your allocation to bonds and cash and other risk management techniques you might put to work.

While the order of returns does not matter considerably in the accumulation stage, when we enter retirement we face that sequence-of-returns risk. Years of poor stock market returns early in the retirement funding stage can permanently impair your portfolio and your retirement. And in fact the risk to retirees begins well before that retirement start date. On Cut The Crap Investing I wrote on that with You Should Protect Your Retirement Portfolio Long Before Your Retirement Start Date. [This also ran subsequently here on the Hub.] Have a read of that article and you’ll see that the Retirement Risk Zone is typically qualified as 5 years before retirement and your first 5 years in retirement. We have to be careful as we approach retirement and in those first few years.

Can a near retiree almost completely de-risk the portfolio and sell a large percentage of their stocks? Sure, it may be emotionally pleasing, but with less stocks in hand it may slightly compromise late accumulation stage portfolio growth. That said, the most important part of it all might be that comfort level and that stress reduction event that comes with greatly lessening that stock component. And let’s face it, some near retirees who’ve planned well and who are lucky enough to have a generous defined pension plan might not need much or any inflation-beating portfolio growth. We’re all snowflakes when it comes to retirement funding, we are all entirely unique in our needs and our situation.

But let’s look at a scenario where a retiree does need their personal portfolio to work very hard; they are counting on that portfolio to deliver a generous component of their ongoing retirement funding needs. It’s time for those hard-earned monies to work for them. On the ‘rule of thumb’ spend rate for portfolios see my Boomer and Echo guest post:  The 4% Rule: Is There A New Normal for Retirees?You’ll read that historically a retiree with a sensible mix of stocks and bonds can spend at the rate 4%-4.5% of the portfolio value each year, with an adjustment or increase each year to compensate for inflation.

Given that we want some growth in the later stages of accumulation and we need that growth component to potentially earn returns above that 5% range, we do not want to abandon that Balanced Portfolio model, we still need those stocks.

To manage the risks, we want to keep that nice mix of Canadian, US and perhaps International stocks to work in concert with that bond component. And the most conservative range that we might move to is 80% to 70% fixed income. That’s a very conservative mix of course.

The returns might be muted but you might be able to eek out 3% income from your fixed income component (a mix of bonds and GICs) and perhaps if stock markets continue to deliver 9-10% annual you must see a returns breakdown such as this:

  • 70% of portfolio @ 3% = 2.1%
  • 30% of portfolio  @ 10% = 3%

That might give you a return in the 5% annual range if the stock market ‘rally’ continues and the bond market does not come under pressure.

Now it’s time to dollar cost average back into stocks

OK, so you’ve largely de-risked but you want and need your portfolio to work as hard as possible. When you hit that retirement date you can begin to increase your stock exposure over time. You might become a retiree stock ‘dollar cost averager’. Yup, you’ll employ the tried and true technique that many of us employ in the accumulation stage: you’re going to add to your stocks on a regular schedule.

You’ve de-risked and then you begin and continue to add risk. They call this an equity glide path. And this has been described and studied in detail by retirement funding rockstars Wade Pfau and Michael Kitces. Here’s their White Paper on the strategy. Continue Reading…
Q&A: Understanding Liquid Alternatives

By Brooks Ritchey

(Sponsor Content)

Alternative investment funds are an exciting new strategy class that were previously unavailable to retail investors in Canada. Since they are new to the scene, many advisors and investors are interested, but don’t quite know where to begin. Since I have worked in the alternative investment space for years, I thought I could help explain how investors could benefit from these hedging strategies.

Demystifying Liquid Alternatives for investors

Some advisors feel that these strategies are too volatile or complicated to explain to their clients. We spend a lot of our time trying to explain that these are not complicated mysterious investments. The irony is that many alternative investments, liquid alternatives, especially with regulatory oversight, are about the same risk level as fixed-income products.

Others also worry about the fees on hedge funds, but they have come down a lot. Since I’ve been involved in the hedge fund industry, fees have come down from 2% management and 20% performance fees to 75 basis points management fees and no performance fees for some products.

How would you explain Liquid Alternatives to investors?

It’s an investment that has different characteristics than traditional equity and fixed income. Equity markets depend on the trend in economic growth and bonds depend on a different set of macroeconomic factors, but they’re both dependent on a trend. If you’re trying to find a strategy that’s looking for winners in the equity or in the bond market when the trends aren’t positive, you want to consider liquid alternatives. Continue Reading…

Searching for yield without reaching for risk


By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

What do almost all major global bond markets have in common thus far in 2019? You guessed it: lower rates. As a result, investors have returned to an environment that could be characterized as “yield challenged” and one that had become all too familiar before last year’s run-up in rates.

Typically, the search for yield comes with added risks as investors either move too far out in duration or lower their credit quality constraints. But what if an investor could enhance yield in their fixed income portfolio while maintaining familiar risk profiles?

Before we focus on a solution, let’s first garner some insights into the Canadian bond market. Similar to the situation south of the border, the Canadian rate outlook going into 2019 was not geared toward a lower rate setting. From a policy perspective, the Bank of Canada (BOC) was projected to continue on its rate hiking path. Prior to the December 2018 U.S. Federal Reserve meeting (the point when expectations began to reveal some change), the implied probability for a BOC rate hike by April was placed around 75% (for those interested, the figure for a rate cut was under 2%). Fast-forward to May 23, and the readings for a rate hike or cut by the end of October are almost split evenly at a little more than 20% each.

CAD 10-Year

CAD 10 Year

How about the Canadian government bond market? As the adjacent graph clearly illustrates, after the 10-Year yield peaked at 2.60% in early October last year, the trend to the downside has been unmistakable. Continue Reading…

How much does it cost to Retire?

By Steve Lowrie, CFA

I’ll start with one good question posed, because it probably crosses everyone’s mind with increased frequency over time:  How much money do I need to retire?

Since I’ve been a financial professional now for more than two decades, I feel well qualified to answer that question.  The answer is:  It depends.

Okay, I realize that isn’t a very helpful answer, even if it’s the truth.  Let’s dig a little deeper.

From a purely quantitative perspective, there are several rules of thumb in common use.  For example, some say if you’ve got 20 or 25 times your annual income in reserve that should do it. Others suggest you’re ready to retire if you can withdraw no more than 4% of your investment portfolio each year.  So, if you have $1 million in your investment accounts, you should plan to withdraw no more than $40,000 annually in a “successful” retirement.

These and similar guidelines offer a decent starting point.  But bad luck happens.  Even if you’ve diligently saved up 20 times your income, if you happened to retire on the eve of a bear market or if you encounter large unexpected expenses, your handy rule of thumb could end up poking you in the eye. Continue Reading…

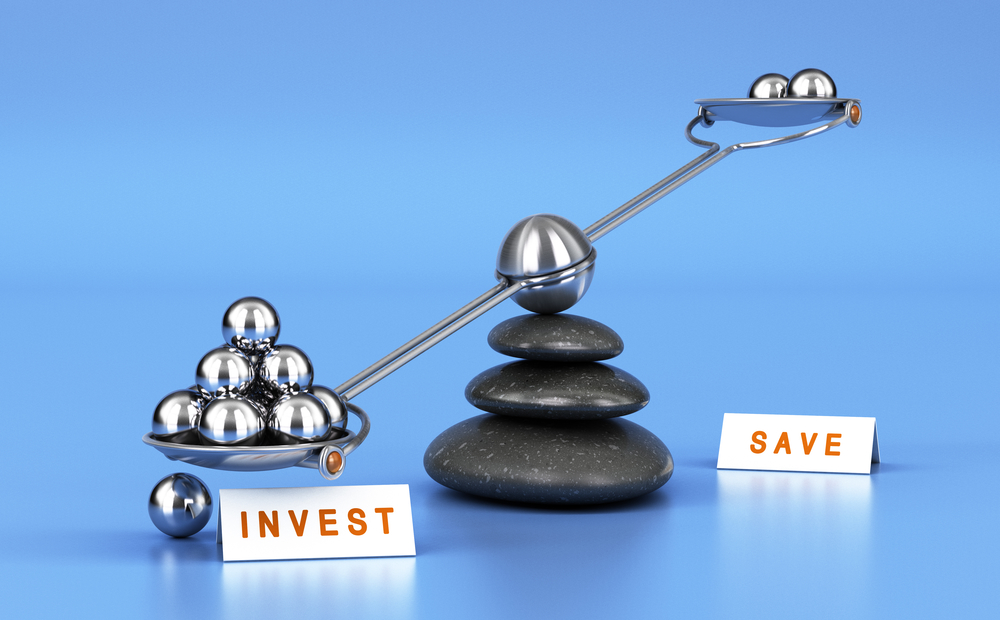
Motley Fool: How to move from Saving to Investing

What’s the difference between Saving and Investing and how do you move smoothly from the one to the other?  Motley Fool Canada has just published the second in a new series of articles by me about the basic steps towards Financial Independence, or what I call “Findependence.” You can find the first one, which ran early in June, here; and the new one by clicking on the highlighted text here: 2 critical steps toward Financial Independence.

The first article discussed how the journey to Findependence hasn’t even begun while you’re still in debt. To paraphrase one of the characters in my book Findependence Day, you can’t even begin to climb the tower of Wealth until you get out of the basement of debt.

It’s nice to be free of debt, whether high-interest credit card debt, student loans or even a mortgage. It’s a big step moving from negative net worth to being merely broke, where your assets and liabilities cancel themselves out. Being free of all debt is certainly a nice place to be if you’ve been anxious over being hounded by creditors. But it’s not financial independence either, which is the stage of life when all sources of income more than meet your monthly financial needs.

As the followup article summarizes, you want to move from Debt elimination to the intermediate step of Saving, and then from Saving to true investing. Saving is being a loaner — you lend money to a bank or other institution and receive a small amount of interest back as well as your principal upon maturity. But to be an investor you want to be an owner: a business owner, through stocks or equities, or more broadly through a diversified basket of equity ETFs.

The end of the piece references a piece by Investopedia about the difference between investing and saving. You can find their explanation here. It says saving is for emergencies and purchases, by which they mean immediate needs. Investing is about a longer-term horizon (defined as seven or more years) and entails more risk than saving. That’s why they refer to the “risk free” return of investing in cash, treasury bills and the like.

Investing is about Money begetting Money

The beauty about saving is that, once the process is begun, it sets the stage for when  money begins to beget still more money, a process that will ultimately happen even while you’re sleeping. So does investing: the difference is that saving is a kind of junior partner to investing: it works a bit for you, but nothing so hard as true investing for the long term. Saving begets small amounts of money; ultimately, investing begets huge amounts of money: eventually enough to live on whether or not you choose to work another day in your life. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.