General

You should protect your retirement portfolio assets long before your actual retirement date.

By Dale Roberts

Special to the Financial Independence Hub

We often think of wealth building and retirement as static dates. We have that accumulation stage when we are building our assets and net worth, and then we have that decumulation stage (retirement or semi retirement) when we are spending our assets. We tend to think of those periods in static terms, with hard stop and start dates. But that could be dangerous thinking thanks to what Dr. Moshe Milevsky of York University describes as the Retirement Risk Zone. That period is typically 5 years before your retirement date and the first 5 years of retirement. That is when the risks are greatest for a retiree.

We need to prepare our investment portfolios well in advance of our planned retirement date. We need to protect our ASSets. And certainly we build wealth in many ways or by many channels. We have our cash and investment portfolios, and we may also have workplace pensions that are building future retirement payments. And of course we have our real estate and perhaps we are also building value and net worth in business ventures. We may have inheritances that we know are likely to come our way. On that front, we don’t want to count those chickens before they hatch.

In this post we’ll discuss protecting the assets that potentially hold the greatest risk: the stocks in your investment portfolios. Of course the funds could be in an RRSP, RRIF, a locked-in plan of sorts, your TFSA or in taxable accounts. And the risk comes from holding those stocks that can be more than volatile at times.

As a refresher, imagine if you had picked January 2008 as your retirement date. In 2007 things are looking rosy and then the Financial Crisis hits and the US stock markets fall by more than 50%. The chart is courtesy of portfoliovisualizer.com

Retirement 2008 start dateYour handsome $350,000 RRSP portfolio gets clipped to fall below $200,000. If a retiree was spending down in typical fashion on the above portfolio they would have seen that $350,000 drop to the $170,000 range. If one entered retirement with an aggressive all-stock stance, they might have their retirement permanently impaired. The Retirement Risk Zone is more about the retirement funding math compared to your tolerance for risk.

Related post: How Retirees Made It Through The Last Two Recessions

When should you prepare your portfolio for retirement?

Again, Dr. Milevsky suggests the risks are great even 5 years before retirement. I’ll give an example using perhaps the most dangerous start date for a retiree over the last 50 years: the year 2000. This was the beginning of a stock market correction that simply would not let up. US stocks were down for 3 successive years in 2000, 2001 and 2002. That has only happened twice in US stock market history, you’ll have to go back to the Great Depression of the 1920s and 1930s to find the other event. Canadian stocks were down for 2 years in a row and did not suffer the same level of meltdown (though it was certainly a troubling bear market).

As you can imagine if a retiree had the year 2000 as a retirement start date and they entered retirement with an all stock portfolio that asset bucket would have been permanently impaired. Of course, I’m assuming that they need to spend from that account type. If you need to spend from that plan or retirement bucket, you need to protect those assets at least 5 years in advance.

Here’s an example of failure in the last years of portfolio accumulation for a retiree. The year is 1998, the stock markets are one the greatest kicks in stock market history and our retiree is smiling from ear to ear with those incredible portfolio gains and a planned 2003 retirement date.

In 1998 our future retiree has $350,000 in her RRSP account, she is still adding $700 monthly, or $8,400 annual. Once again, we’ll use the US stock market for demonstration purposes. Of course you hold a more diversified asset mix.

Retirement 2003 No ProtectionThe retiree has been adding monies on a regular schedule for 5 years and has a negative rate of return. The real rate of return when we factor in inflation is even less favourable. The retiree started 1998 with $350,000, added $42,000 and ended the period with just over $369,000.

In Scenario 2 our retiree moves to a Balanced Growth model in 1998. She is now 70% stocks and 30% bonds (I’ve used 10 year treasuries). She enters 2003 with modest but positive returns for the period, and with a portfolio value of $438,000.
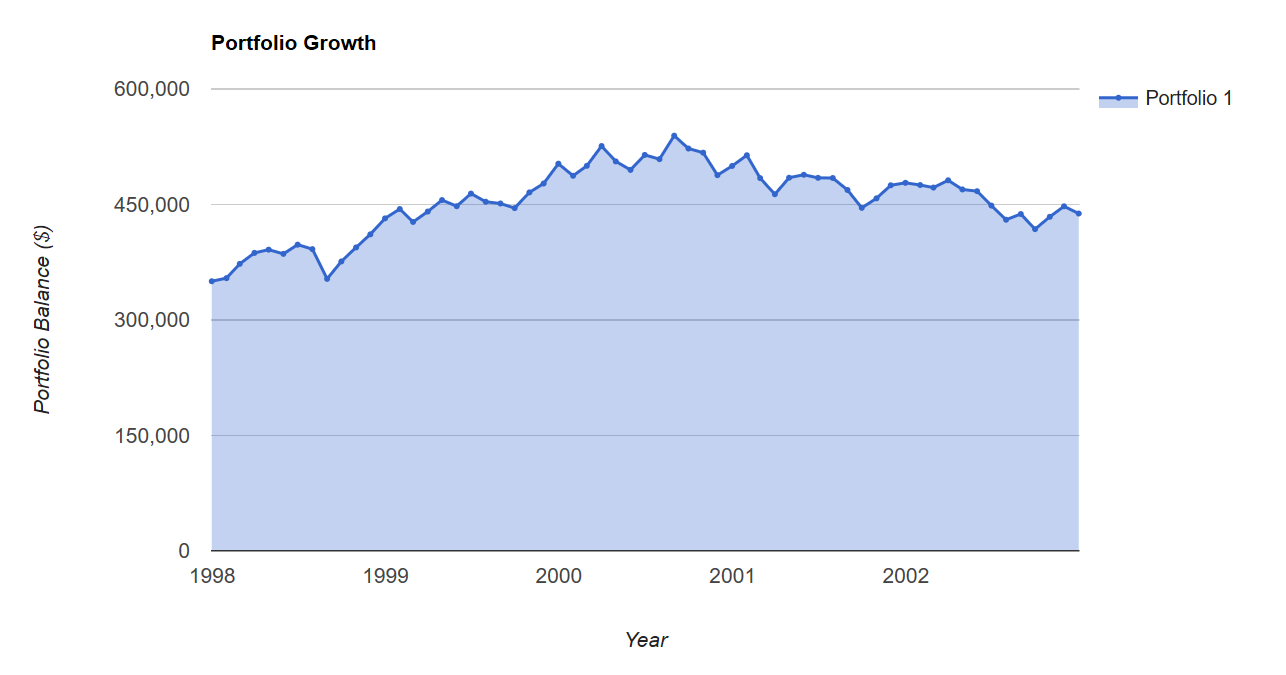
Retirement 2003 with ProtectionAnd of course, to a point, the more conservative a portfolio (more bonds) the better for the test. But hey, that’s all certainly hindsight as we’ve picked the worst possible retirement start date. Right? Not so fast. Even if we look at the 2008 market correction protecting the assets well in advance works much better, and the more conservative the balanced portfolio, the better. You might at least keep your equity allocation in the 30%-40% area.

*And certainly, one can use other assets beyond bonds to manage risks.

We are on the same last few years accumulation strategy with a 2010 retirement start date. In this example we are ‘protecting’ the funds 6 years in advance.

Portfolio 1 is all US 100% equity.

Portfolio 2 is 60% stocks and 40% bonds.

Portfolio 3 is 40% stocks and 60% bonds.
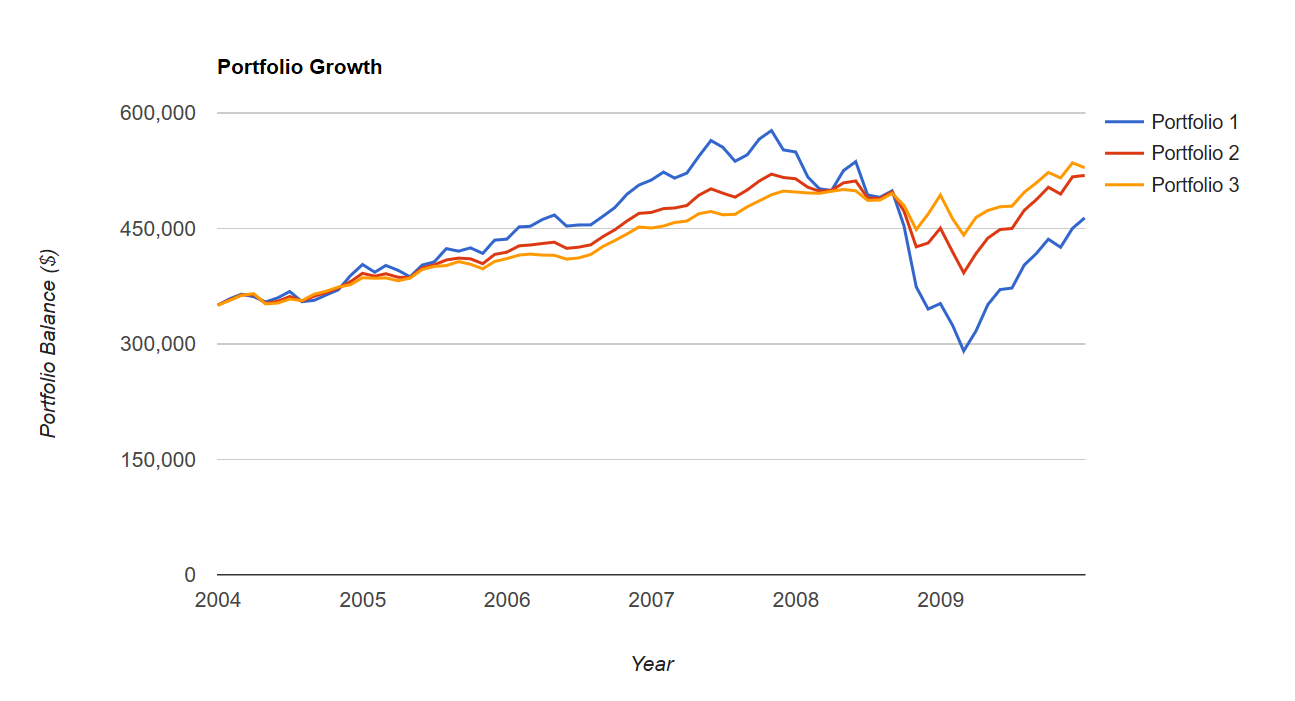
Retirement 2010 start date various allocationsThe only time this strategy will fail, that is deliver opportunity cost, is when we take out a severe market correction and invest only in a period of mostly rising markets (bull markets). Of course as an investor or advisor that is not a risk that you want to take. You do not want to guess that a stock market correction is not in the near future. Stock market corrections historically come along with regularity. We are currently in an abnormal period of an extended (mostly) bull market run.

A more conservative accumulation stage

As we approach the final turn toward the retirement ‘finish line’ we obviously want to increase our portfolio value. Continue Reading…

Boomer & Echo guest blog: What I’ve learned so far in Semi-Retirement

Regular Hub guest blogger Robb Engen returned the favour earlier this week by inviting me to write a blog for his site Boomer & Echo. You can find that version by clicking on the highlighted headline: What I’ve learned so far in Retirement.

For convenience, it also appears below, including original links, with a Hub headline and a few subheadings that better reflect the central point that I personally don’t consider myself fully retired yet. This version has a few extra points added, plus two links to FIRE pieces that didn’t appear in the original B&E version. And as a bonus, it includes near the end an update on some of our recent travels, which hopefully reinforce some of the broader themes described in this blog.

Which begins as follows:

Through most of the five years the Financial Independence Hub has existed, Boomer & Echo’s Robb Engen has been kind enough to allow the “Hub” to republish some of his blogs that first appeared on his own site.

He recently suggested we turn the tables and invited me to write a guest blog for Boomer & Echo recounting some of the lessons I’ve learned in my decades as a financial writer and what I’ve learned so far in Retirement. Here it is.

For starters, my age alone qualifies me as a Boomer: I recently turned 66, but do not consider myself retired: at most, I consider myself semi-retired. As Robb would know, running a website is no trivial undertaking and I aim for new content 5 days a week, 52 weeks a year. That and writing for a handful of media outlets keeps me fairly occupied, although the privilege of doing this from home means I gain a couple of hours that would formerly have been expended on commuting.

Indeed my last full-time salaried staff job that involved commuting and bosses ended five years ago, when I stepped down from the editorship of MoneySensemagazine. That two-year stint followed 19 years at the National Post/Financial Post, most of which time I was the paper’s personal finance columnist.

Those familiar with my books or blogs would not expect me to describe myself as Retired, since my shtick has long been Financial Independence, or my contraction for it: Findependence. That’s as in Findependence Day, a financial novel I wrote in 2008 (Canadian edition) and 2013 (US edition.)

As I have often written, I do not regard the terms Retirement and Findependence as synonyms. You can be Findependent but not Retired, as I am; but it’s hard to be Retired if you’re not Findependent.

In the old days, the traditional “full-stop” retirement was considered to happen at age 65, which even today is when you can first start receiving Old Age Security benefits. (And yes, I do now collect OAS, for reasons I’ve explained elsewhere). But “Findependence Day” can be years or even decades earlier: you may still choose to work for money but on your terms: the magic day is when you’re completely free of debt and have enough saved (and properly invested) that even if you never earned another dime you could meet all your major living expenses, assuming some variant of the 4% Rule.

Even if I considered myself as having “retired” at age 61, that’s relatively old by the standards of the so-called FIRE movement, which of course stands for Financial Independence Retire Early. True FIRE people aspire to “retire” in their 30s or 40s, sometimes even in their 20s, typically by saving like demons for a decade or so: in the most extreme cases they may save      something like 50% of their income.

I’m more like Robb, where he described in his blog why he wasn’t yet paying down his mortgage because he first wanted to maximize RRSP and TFSA savings. Mind you, my books do argue that “the foundation of financial independence is a paid-for home” but I’m old school and we bought our first home (of only two) back in the 1980s, when Toronto real estate was pricey but hardly at the lofty levels of today. Of course, interest rates were much higher then: close to 12% in our case, so we were motivated to pay off the mortgage as quickly as possible.

I don’t see myself as an early retiree or a “FIRE” blogger

There have been some interesting critiques of FIRE, nicely summarized by Fritz Gilbert in a guest blog for the Hub: Is the Fire community full of hypocrites? Fritz is an American Pluto award winning blogger for RetirementManifesto.com, who I’ve come to know through our joint membership in the Younger Next Year 2019 Facebook group, which I helped found and have helped moderate (along with the site’s prime mover Vicki Peuckert Cook) since late 2017. Fritz “retired” himself at age 55 about this time last year. But as we would both argue, he’s hardly retired in the classical sense of the term. Continue Reading…

My biggest retirement planning mistakes

Looking back, my biggest retirement-planning mistakes had nothing to do with money. Rather, they resulted from not thinking things through and not having a good retirement lifestyle plan in place, for when I did retire.

Because of that, it took me a couple of years to figure things out and get things right after retiring. Unfortunately, I will never get that time back. If I could do things differently, here are some of the mistakes that I would avoid making:

Mistake #1

Deciding to turtle, play safe and hang on for another 7 years

The opportunity cost of staying in a career that you no longer like just so you can max out your pension is high, especially if you have already achieved financial independence. You end up losing precious time and become sour. But there is something about that pension statement with the pre-determined retirement date that keeps us coming back for more. I can’t tell you how much time I spent running the numbers over and over again trying to figure out the right combination that would allow me to move on to something better.

Few people quit a marathon at mile 25 and most people late in their careers will choose to hang in there until the bitter end. But they need to ask themselves: Is it really worth it?

Why continue to waste valuable time putting off something that you are truly passionate about?

Although switching to part-time work means taking a pay cut, finding great work increases the odds of you working longer. Instead of retiring at age 62 feeling tired and worn out, you are thriving and excited by the work you do. By finally making the choice to leave and start your Victory Lap (VL), you no longer go to bed at night dreading the next morning’s work, trying to hang on until another weekend. Making a little less for a little longer while dramatically increasing your daily personal fulfillment is a total win.

Mistake #2

Not knowing my values and what would make me happy in retirement

I’ve learned that a great retirement is not about how much money I have; rather, it’s about an attitude, a way of living, filled with searching and discovery. To have a great retirement, you need to have a good sense of who you are, what you are, what you value and what will make you happy.

Unfortunately, because we are so busy taking care of our families and just trying to survive, we lose touch with our values.

In order to be happy in retirement, you need to get a good feel for who you are. This can be done through self-analysis to identify your abilities, values, drivers and interests. After going through this process, you will know what you are good at, and what you want/need to do with the rest of your life.

Mistake #3

Not starting work on my side gig before I left my corporate job

Working on what I planned on doing in my VL would have been a far better use of my time, instead of wasting it de-stressing in front of the TV for hours at night. Continue Reading…

Using Canadian Dividend ETFs as your core Canadian holding

As warm and cuddly and comforting as are dividends, the subject or investment approach can lead to some lively debates. Many will write (or build podcasts on the subject) that dividends simply don’t matter.

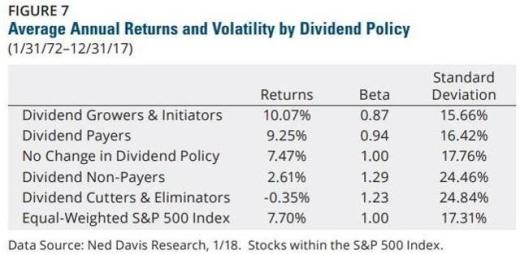
On that, here’s a measured response from Mike at The Dividend Guy blog. Please have a read of Should I Go With Dividend Growth Investing or ETFs. An Answer To Ben Felix. Of course many dividend and dividend growth investors will simply reference or pull out the Ned Davis research on S&P 500 constituents.

I like the evidence from the Dividend Aristocrats (NOBL) in the US and Canada (CDZ) that both have greater total returns compared to broad market funds through the last market cycle. There is a longer history of outperformance to observe in the US market with those Aristocrats that insist on at least 25 years of annual dividend increases. The threshold for a Canadian Aristocrat is 5 years of dividend increases.

All said, I will leave it to you to decide if dividends matter: to you. Given that nothing is more important than investor behaviour, if watching the dividends is a very useful distraction and those dividend payments allow you to stick to your plan, then they are more than worth the dollar value that shows up in your discount brokerage account.

And for the record I do think or know that the benefits of dividend growth investing do move beyond the emotional and behavioural and into the math and the types of companies that can be found by way of a meaningful dividend growth history. Even Ben Felix will admit that it can help us find certain types of companies and investment factors.

Canadian investors need help!

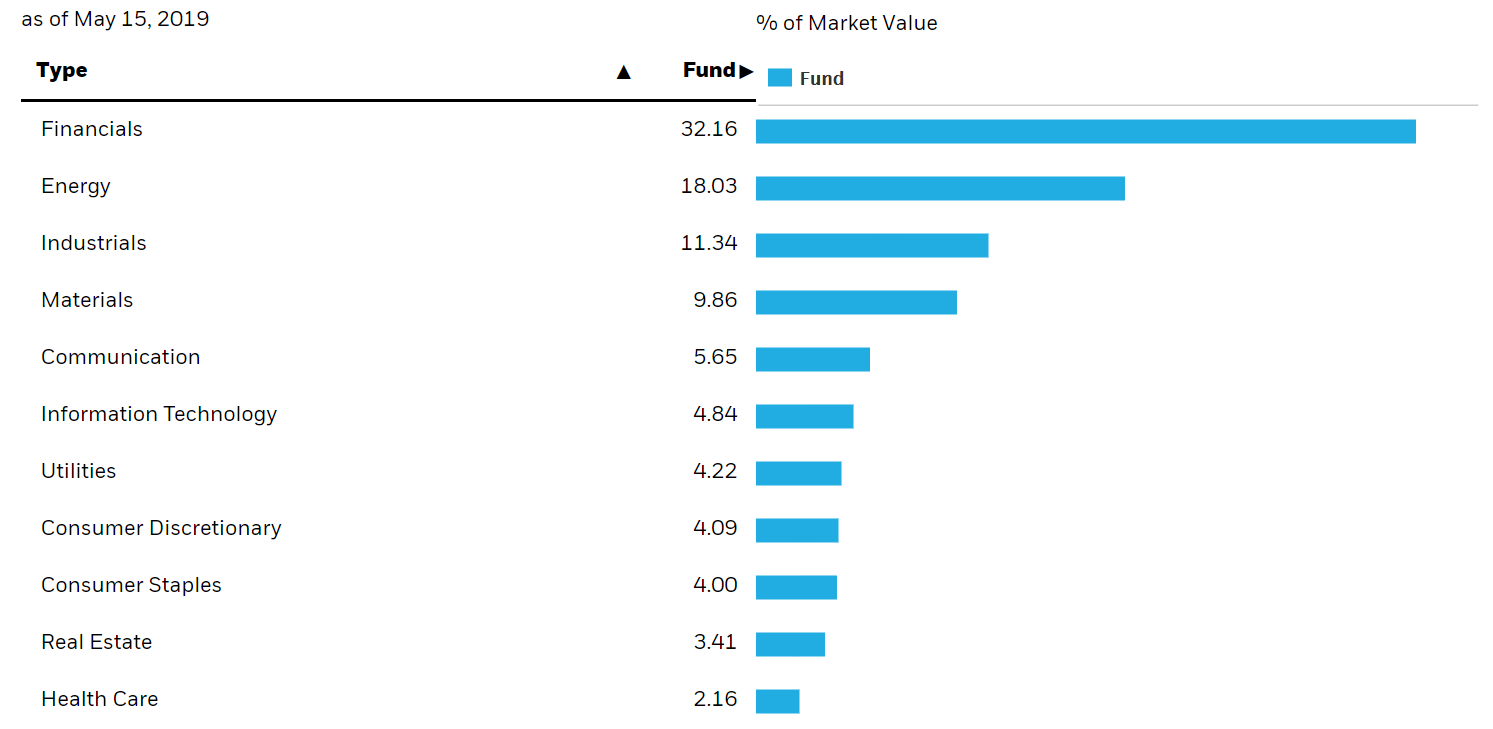
Let’s face it, the Canadian market is not well diversified. I would often state to clients that Canada makes for a terrible investment. The Canadian market is concentrated in financials and energy and commodity related sectors.

From iShares XIC, TSX capped composite.

TSX Composite Sector BreakdownThe Canadian investor needs the sector and geographic diversification offered by the US and perhaps International markets. Here’s the sector breakdown of the S&P 500, by way of iShares IVV.
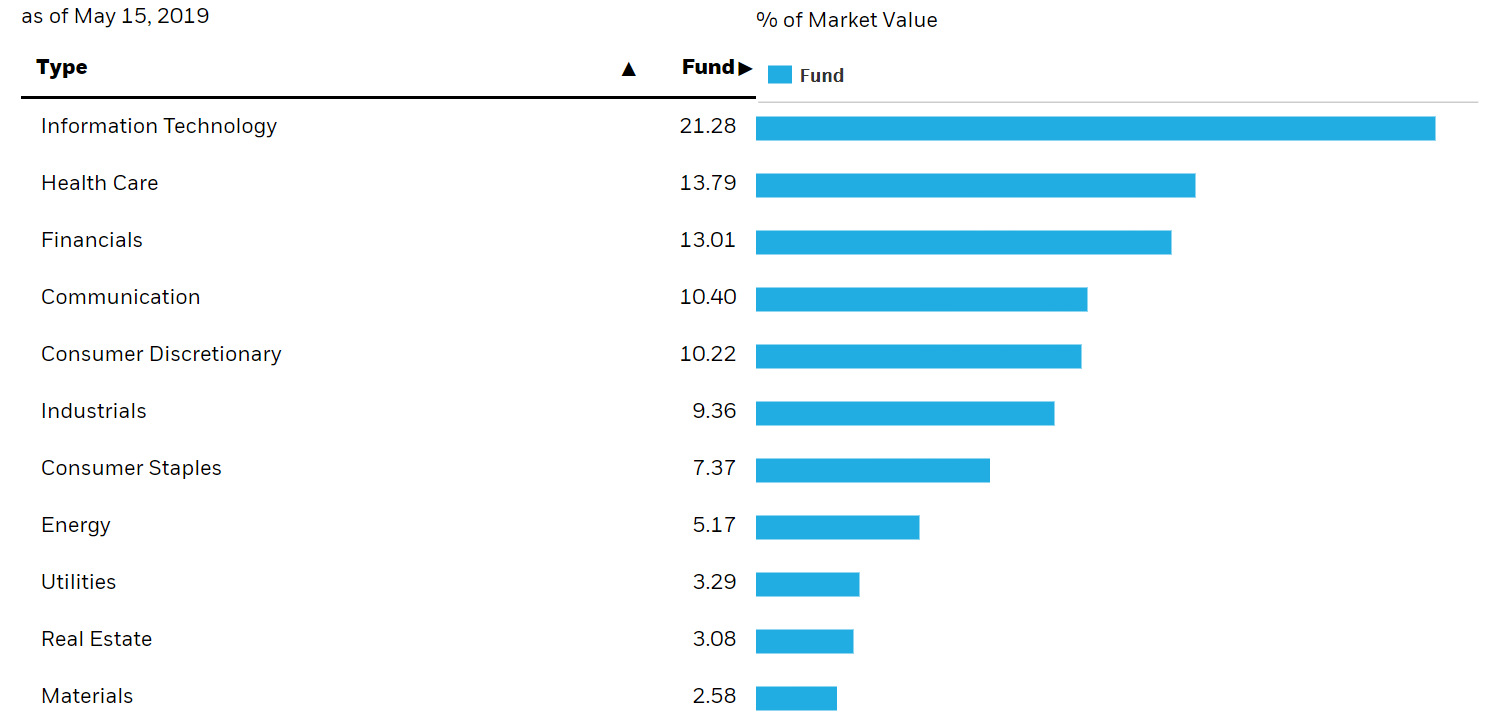
S&P 500 Sector BreakdownThe basic principle of the need for added diversification holds true whether a Canadian investor embraces core index funds or dividend focused funds. How much you add by way of International exposure is certainly a personal decision. I am of the opinion that you might go light on that front given that the large and mega cap US companies earn a considerable percentage of their profits overseas. That said, in a recent CTCI investing post I suggested you might also look to developing markets where there is greater growth and growth potential.
Canadian Dividend ETFs

For my Canadian allocation in my personal RRSP account I hold a concentrated portfolio of individual bank stocks, plus pipelines and telcos. I do not expose my wife’s personal RRSP account to that concentration risk: we hold Vanguard’s High Dividend Yield ETF, ticker VDY. That is the core holding. Here is the sector breakdown for the VDY fund. Continue Reading…

Building your financial stop-doing list: Stop chasing dividends

By Steve Lowrie, CFA

Special to the Financial Independence Hub

During the 20+ years I’ve been a financial advisor, I’ve noticed how often the market keeps playing the same devilish tricks, each time in a guise that differs just enough to fool us all over again.

Today’s “Stop Doing” post exposes one of these more common tricks of the trade: Investors who are seeking a reliable income stream for retirement should STOP building their investment strategy around dividend-paying stocks (or higher-interest-yielding bonds) in isolation, without considering them in the context of their total wealth management.

Speaking of devilish acts, let’s revisit The Wall Street Journal columnist Jason Zweig’s “The Devil’s Financial Dictionary” (emphasis is ours):

DIVIDEND YIELD, n. A company’s annual DIVIDEND divided by its current share price. “You buy a cow for its milk and a stock for its yield,” says an old Wall Street proverb. But when a company gets into financial trouble and has to cut its dividend to hoard cash for its own survival, the yield will shrink or disappear. Investors who buy a stock only for its yield may suddenly find themselves owning a cow that gives no milk and is too scrawny to butcher for the meat.

Clearly, I am not alone in my skepticism when I see investors investing in a stock because “it pays a good dividend.”

What is a Dividend?

Sweep away all the complexities about corporate profits, and you’re left with this truth: When a public corporation makes a profit, it has two choices on what to do with that cash:

  1. Re-invest it back into the business, or
  2. Return it to shareholders through cash dividends or share repurchase plans.

These concepts aren’t new. Nobel laureate Merton Miller and Franco Modigliani published a paper back in the 1960s, explaining why profits are profits, whether they’re “packaged” as dividends or share value. So, let’s take a look at why chasing dividend-paying stocks may not be all it’s cracked up to be. Continue Reading…

Powered by the Financial Independence Hub.
© 2013-2026 All Rights Reserved.
Financial Independence Hub Logo

Sign up for our Daily Digest E-Mail!

Get daily updates from the FindependenceHub.com straight to your inbox.