General

Alternative assets in ETFs and mutual funds, including a new one from Franklin Templeton


Alternative asset classes like private equity and real estate have long been in vogue with pension funds, institutional investors and some high-net-worth individual investors but the pickings have been slim for retail mutual fund investors. Now, Franklin Templeton Investments Canada has introduced the Franklin K2 Alternatives Fund.

The company says its new mutual fund, announced on Monday, March 11, uses “a multi-strategy approach in seeking to dampen volatility and offer downside protection, while providing added diversification and low-correlation to asset classes typically held in a traditional portfolio.

Franklin Templeton Canada Duane Green pointed to the unpredictable market environment of the past year and said “investors are looking to reduce volatility and protect capital … Our alternatives fund addresses these investor needs and combines the benefits of a sophisticated solution with the liquidity, convenience and fee transparency of a mutual fund.”

In a piece this weekend in the Financial Post, which mentioned the new Templeton fund among others, investing reporter Victor Ferreira said Canadian retail investors looking for exposure to hedge-fund like strategies that can involve leverage and short-selling are being inundated with new options, following a rule change in January. At least six firms have brought so-called “liquid alternative” products (some of them ETFs and some of them mutual funds from firms like Mackenzie and C.I. Funds) to market since regulations barring them from doing so were lifted at the beginning of 2019. Prior to the regulations being altered, he said, only a few firms were able to offer such products after applying for exclusions.

As the Post pointed out, some alternative assets — notably real estate and private equity — are seldom easily liquidated if you need some cash. It cited a 2018 Scotiabank report that projects the Canadian market for these kind of products could grow to be worth $20 billion.

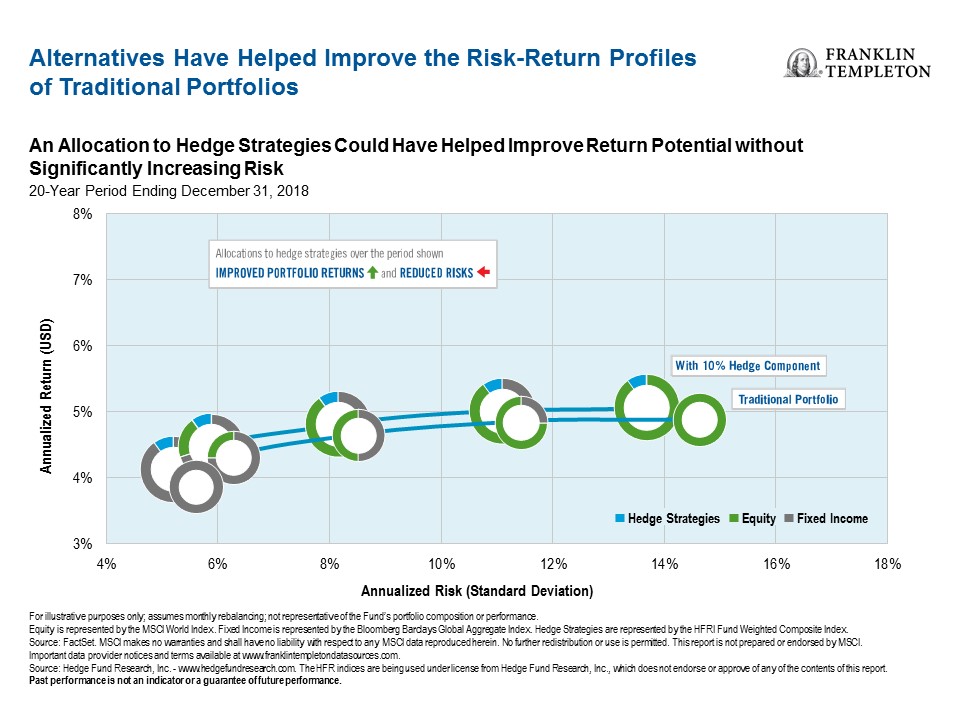
According to Franklin Templeton marketing documents, alternative asset classes or hedging products can improve return potential without significantly increasing risk. It describes three possible “buckets” investors can choose from: traditional Equity Beta or “Risk On,” traditional Bond Beta or “Risk Off” and Alpha Alternatives, or “Risk Uncertain.” It said Alternative Assets can also protect client assets during declining equity markets. In addition, Alternatives have “held up well in weak bond markets.”

Green told the Post that the new Franklin Templeton fund gives investors access to three different strategies: the fund will index 50 hedge funds and aim to replicate their returns. On the long/short side, the fund will also identify the most popular stocks that alternative asset managers are buying and take long positions in them while shorting S&P 500 or futures contracts and any individual names it deems unattractive. Thirdly, the fund will target risk premia.

Or, in the language used in the Franklin Templeton press release: Continue Reading…

Tax hacks: Top 5 tax filing tips to get the most out of this tax season


By Clayton Brown (Sponsor Content)

Are you leaving money on the table when it comes time to file your taxes? Lots of people do. They don’t bother applying for grants. They leave that ratty pile of expense receipts in the drawer (where they left it last year, too). And they don’t take full advantage of the deductions to which they are entitled.

Let’s get your taxes done right and get the biggest possible tax refund. Here are some tips about pitfalls to avoid, and easy things you can do to make that happen.

Tip 1. Don’t forget to deduct your deductions!

Remember, that tax refund you want isn’t a freebie from the government. It’s your money! They’re just holding it for you. So get it back, by claiming allowable deductions!

Hold on a second. What’s a deduction? It’s an amount you can deduct from your taxable income, thereby paying tax on a lower income.

We’ve noted a few common deductions here to save you some time.

RRSP contributions. You’ll need all of your RRSP slips … right? Actually, not so much! All you need is the dollar amount. Look at the transaction history for your RRSP contributions (which might just be a few lump sum contributions, or from an automatic savings plan) and add up all the contributions you’ve made. It’s a good idea to hang on to the receipts in case you’re audited but you don’t actually need them!

(You should have received them by now: see the timeline of forms below). Lower your taxable income by contributing to your retirement savings.)

Your annual contribution is limited to 18% of your previous tax year’s earned income, plus any unused carry forward room from previous years.

Child care costs. Did you pay someone else to look after your little ones while you went off to work or advanced your education?

The government lets you deduct up to $8,000 per child, for kids under 7. You can deduct up to $5,000 per child for those aged 7 to 16 (just guessing, but maybe there’s a government ratio in there that accounts for cuteness, which declines precipitously after age 6). For disabled or dependent children of any age, the maximum claim is $11,000.

Tip 2. Don’t forget to claim your credits!

A credit is an expense you can claim to reduce your taxes payable. It’s not the same as a deduction, which comes off the top of your income. But a credit is not a 1-to-1 deduction. A $500 credit is not the same as $500 off your tax bill. Check out this list of all available deductions and credits.

One example: interest paid on student loans. This is a pretty sweet deal. You can claim any interest on your student loans as a non-refundable credit. For student loans, the tax credit (federal and provincial) is calculated by multiplying the lowest federal/provincial/territorial tax rate by the amount of the loan interest.

Medical credits are another one that people forget about. You can apply credits to certain medical expenses. Charitable donations are also popular credits.

Credits can be non-refundable or refundable. A refundable tax credit means you’ll get the value for that credit, even if the tax bill is zero. But a non-refundable tax credit will only reduce your tax bill to zero.

Tip 3. Don’t file your taxes before you have all of the information you need

This is a super-common mistake. But filing too early could cost you extra time and money later, if you need to file all over again. Better to wait a bit and do it right the first time. Continue Reading…

Solving the home country bias in Canadian portfolios

Canadian investors tend to suffer from home bias – a preference to hold more domestic stocks over foreign equities. This is actually true of investors in most countries, but it’s particularly troubling in Canada where our stock markets are highly concentrated in the financial and energy sectors.

The federal government could be partially to blame for our home bias tendencies. As recently as 2005 the government imposed a limit on the amount of foreign content allowed in RRSPs and pension plans. This cap was introduced in 1971 to help support the development of Canada’s financial markets but was scrapped in the 2005 federal budget, freeing Canadians up to invest abroad.

Sizes of World Stock Markets

It’s well known that Canada makes up less than 4 per cent of global equity markets (2.7 per cent, to be exact), yet 60 per cent of the equities in Canadian investors’ portfolios are in domestic securities.

Even most model ETF and index fund portfolios have Canadian investors overweighting domestic equities, holding anywhere from 20 to 40 per cent Canadian content.

Canadian home country bias

The result is a portfolio that is more volatile and less efficient than one with international equity diversification. Indeed, investors with a Canadian home bias are taking risks they could have diversified away by increasing their allocation to global equities.

My two-ETF portfolio

So how does my portfolio stack up? When I switched to my two-ETF solution, made up of Vanguard’s VCN (Canadian) and VXC (All World, ex-Canada), I chose to have an allocation 20-25 per cent Canadian stocks and 75-80 per cent international stocks.

That allocation would be relatively easy to monitor and rebalance if it was simply held in my RRSP. Whenever I added new money to my RRSP, I’d simply buy the ETF that was lagging behind its initial target allocation.

But I complicated things recently when I started contributing again to my TFSA. I wanted to treat my TFSA and RRSP as one total portfolio and keep the same asset mix in place. Since my RRSP was much larger than my TFSA, I decided to hold mostly foreign content (VXC) in my RRSP while putting Canadian stocks (VCN) in my TFSA.

This worked out great for several years but now I’ve run into a second problem; I’m contributing to my TFSA at a much faster pace than my RRSP. That’s because I’ve maxed out all of my unused RRSP contribution room and, due to the pension adjustment, I get a measly $3,600 per year in new contribution room.

Meanwhile I still have loads of unused TFSA contribution room and so I’ve been socking away $12,000 per year for the past two-and-a-half years. I hope to continue at that pace for many more years until I’ve completely caught up on all that available contribution room.

The result is a portfolio that is becoming increasingly more tilted to Canadian equities. At this rate, if I continue filling my TFSA with VCN, my portfolio will have more than 30 per cent Canadian content in five years, and nearly 40 per cent Canadian content in 10 years.

My Home Bias Solution

I’m considering a change to my two-fund portfolio. With the introduction of Vanguard’s new all-equity asset allocation ETF – VEQT – I could turn my two-fund solution into a true one-fund solution and make investing even more simple. Continue Reading…

Aman Raina’s 4-year Robo Advisor review


By Aman Raina, SageInvestors

Special to the Financial Independence Hub

Four years ago, Obama was President of the United States and Stephen Harper was Prime Minister of Canada. A Liberal was running America and a Conservative was running Canada. The New England Patriots were still making it to the Super Bowl, even winning a few…

…and I had opened my Robo Advisor account.

Yes it been a full 4 years since I opened up my Robo Advisor account. For those new to investing, a Robo Advisor is a new wave of wealth management companies that invest on behalf of others using an online platform and a combination of algorithms and computer coding to buy and sell specific investments and manage portfolios. Four years ago these firms were just stepping into the investing conciousness, but since then they have mushroomed and even traditional investment companies are now offering some flavor of online investment management services. It all seemed quite appealing however there was one thing that many marketing materials, blogs, and mainstream media was avoiding (and still are I might add)…do these types of services make money for investors?

Since no robo advisor company back then was interested in disclosing their performance (they still avoid it) other than citing research that their strategy is superior, I decided four years ago to try an experiment and find out for myself. I setup an account with one of the big Robo Adviser firms. My goal was to go through the process and blog about my experience and more importantly, the results. I’ve always said that we need a good five years to really get a handle on how effective these services are compared to traditional wealth management services. Well, we’re at the 80% mark of my ROBO journey, so let’s check back in and take a look at how it’s doing now and see if we can squeeze any conclusions about the service.

In previous years, I have stated that for us to get a real handle on their effectiveness, we need to see these robo-portfolios experience some stress. Up until 2018, the markets have been quite tame. We’ve seen how these portfolios operate in a period of rising stock prices. In 2018 we finally hit some periods where there were major swings in stock prices around the world. In February we saw the Dow Jones on several days drop more than 1000 points and in December we had the Christmas Eve Massacre where stock prices fell off a cliff creating a lot of hand wringing over the Christmas break. Finally meaningful, although short-term stress points for the ROBO portfolio.

Performance

Below is the current status of my ROBO portfolio as of January 30, 2019 and below that is the chart of annual returns over the past four years.

My ROBO Advisor portfolio as of January 30, 2019

My ROBO Advisor portfolio as of January 30, 2019

ROBO Portfolio Annual Return

(annual returns)

 The first year was a rough one for ROBO as it had lost 2.15 per cent. In the second year and third year, ROBO picked up its game. The portfolio generated a 13.2 per cent return in Year 2 and in Year 3 it posted another solid year with a 14.2 per cent return. In 2018, the portfolio pulled back going down a total of 2.1 per cent. The loss was tempered by dividends, where the portfolio generated $142.91 in dividend income. The ROBO was also saved a bit by a strong rebound in stock prices in January coming off the correction in December. The losses could have been much worse. Considering the largest component of the ROBO portfolio was concentrated in US and Canadian stocks and where the S&P500 and TSX/S&P Composite were down 6.3 and 11.7 per cent respectively in 2018, a 2.1 per cent drop is very reasonable. I lost money but not as much. Since January 2015, the portfolio is up 22 per cent over the last 4 years.

Asset Allocation

When I set up the account I answered a series of questions about my financial literacy and risk tolerance. ROBO took my responses and crafted a portfolio that it felt was compatible with my profile. As I am pretty experienced with investing and have a long-term investment horizon, ROBO determined that a portfolio mix of 85 per cent stocks and 15 per cent bonds would work for me. It has since then retained the same stocks/bonds ratio.   Continue Reading…

How federal housing policies could impact first-time homebuyers

By Jordan Lavin, Ratehub.ca

Special to the Financial Independence Hub

For a little more than a decade, the Federal Government has been making policies that make it harder to buy your first home in Canada.

It’s hard to blame them. The great recession of 2008-09 was principally caused by a crash in the U.S. housing market which, in turn, had been caused by lax mortgage lending standards. Hundreds of thousands of people bought homes they couldn’t really afford, and were later foreclosed on or forced to sell. Left behind was a glut of housing inventory and an equal glut of people who had lost everything. The ripple effect was felt throughout the world, including here in Canada.

Fortunately, the mortgage problem was isolated to the United States. But the repercussions hit Canada hard, and interest rates fell to unprecedented lows as a response to the worsening economic situation. During the recovery, mortgage rates in Canada continued to fall and house prices quickly rose. In hot markets like Vancouver and Toronto, the average price of a home nearly doubled between 2010 and 2016.

All this left government officials on this side of the border wondering if it was possible for the mortgage and housing market to fail here. With the compounding worry of a housing market crash – what if prices went back down as quickly as they had gone up? – they began making new policies with the goal of making it more difficult for Canadians to qualify for a mortgage, especially if that mortgage were to be insured by the Canada Mortgage and Housing Corporation (CMHC).

Among the changes: Limiting amortization length for insured mortgages to 25 years; Limiting CHMC insurance to homes purchased for under $1-million only; Establishing a minimum down payment of 5% and then increasing the minimum for homes over $500,000; and expanding a “stress test” to eventually force all mortgage borrowers to qualify at a higher interest rate than they would actually pay.

This cocktail proved poisonous for first-time homebuyers. High house prices, harder qualification criteria and lower earning potential forced first-time homebuyers to get creative, finding new ways to afford homes.

Today, the government is looking at two new policy changes that could have an impact on first-time homebuyers.

A return to 30-year insured mortgages for first-time homebuyers

Currently, the longest you can take to pay back an insured mortgage (mortgage insurance is usually required when you have a down payment of less than 20%) is 25 years. But one policy change the government says they’re looking at is increasing that limit to 30 years.

This is a boon to affordability, at least at the qualification level. Ratehub’s mortgage payment calculator shows that the monthly payment on a $500,000 mortgage at today’s best rate of 3.29% will be $2,441 when amortized over 25 years, or $2,181 when amortized over 30 years. Since mortgage affordability is based on a fraction of your income, a lower payment equals a higher purchase price you can qualify for.

But there’s a significant downside. The obvious is the additional 5 years of mortgage payments later in life. If you’re over 35, signing a new 30-year mortgage could keep you making payments into retirement. Continue Reading…