General

Is Renting throwing away money?

Most people tackle the rent vs. buy problem incorrectly by framing it as the cost of monthly rent versus the cost of a monthly mortgage payment. The argument goes something like, “if your monthly rent costs as much as a mortgage payment on the same or similar property, then it’s a no-brainer to buy the home and build equity rather than flushing your rent money down the drain.”

Others argue that a better comparison looks at the true cost of home ownership, which not only includes the mortgage payment but also things like property taxes, insurance, and maintenance.

However, as PWL Capital’s Ben Felix pointed out in the latest Rational Reminder podcast, neither argument paints a truly fair comparison of rent vs. buy. What you need to look at, he explains, is the total unrecoverable costsin each scenario.

For example, a monthly rent payment is a total unrecoverable cost: an expense that does nothing to improve the renter’s net worth. A mortgage payment, on the other hand, only has partial unrecoverable costs: the interest paid on the mortgage. The other portion reduces your mortgage amount and therefore increases your net worth.

A winning point for home ownership, right? Not so fast.

We need to add up all of those additional costs that a home owner bears (property taxes, insurance, maintenance), plus any upfront money spent on a down payment, land transfer tax, title insurance, home inspection, etc. to close on the home.

There’s also an opportunity cost on the down payment and other closing costs. That money could have been invested instead of put towards buying a home.

Rent vs. Buy: Let’s Do The Math

Let’s look at an example of a renter in Toronto who’s paying $2,000 a month to rent a 575-square foot condo. The same condo is listed for $449,000.

To purchase the condo our renter would need to put down 5 per cent, or $23,450, plus add another $17,062 to the mortgage due to CMHC insurance (required on all mortgages with down payments of less than 20 percent), for a total mortgage amount of $443,612.

Our upfront costs are not done, however, as we need to add in land transfer taxes of $10,910, lawyers fees of $1,000, title insurance of $449, plus a home inspection for $500.

Total upfront costs = $36,309. The opportunity cost of this amount in 25 years at 6 per cent a year = $155,834.

Now let’s look at the unrecoverable monthly costs. The mortgage is amortized over 25 years and has an interest rate of 3.50 per cent. The monthly mortgage payment is $2,215. Of that payment, $1,200 goes towards interest and $1,015 goes towards paying down the mortgage principal.

Then we have property taxes coming in at $375 per month, and we’ll also add the difference between home insurance and tenant insurance, which is $40 per month. We also need to add expected maintenance costs, which we’ll estimate at 1 per cent of the property value per year, or $375 per month.

Total unrecoverable monthly costs (interest, plus property tax, plus insurance, plus maintenance) = $1,990

The unrecoverable costs for the renter and homeowner are nearly identical. The total monthly payment for the homeowner, including property taxes, insurance, and maintenance, is $3,005. Just $1,015 of that is building equity in the home. So, back to the rent vs. buy argument.

Rent and Invest the Difference

We have to assume our renter has an extra $1,015 available in their cash flow each month to invest. What are the expected returns for a 60/40 balanced investment portfolio over 25 years: maybe 6 per cent? Continue Reading…

Retired Money: Getting real about Retirement planning with Viviplan

My latest MoneySense Retired Money column looks at a financial planning software platform called Viviplan. You can find the full article by clicking on the highlighted text:  What I learned by putting Viviplan to the test.

Viviplan is the third retirement planning package I’ve tested this year, perhaps — as the MoneySense article reveals — the topic is getting all too real for me now that my wife, Ruth, has told her employer she plans to retire when she turns 65 next summer. I’m a year older and have been somewhere between self-employed and semi-retired for most of my 60s.

Previously we have looked at a couple of packages created by Emeritus Financial Strategy‘s Doug Dahmer — who is a frequent contributor to the Hub — as well as Ian Moyer’s Cascades, which you can read about in an earlier column by me here. Dahmer offers a choice of two packages: Retirement Navigator and BetterMoney Choices.com.

All these packages deserve consideration and work in more or less similar fashion. To do the job justice, you need to have handy — or at least summary information — such documents as your latest tax returns, brokerage statements, Service Canada CPP and/or OAS projections, as well as having a good grasp of your regular and occasional monthly expenses.

Having most recently performed this exercise with Viviplan — and as one of the users we interviewed for MoneySense relates — it can be a bit scary to see in black and white just how expensive daily living can be. The package won’t let you forget any tiny expense, from pet food to boarding your pet when you’re on vacation (or arranging to hire a neighbour’s teenager, which is what we do if we go away and must leave our cat behind.)

Viviplan calls itself a Robo Planner

Viviplan — which has been dubbed “Canada’s Robo Planner” — is the brainchild of financial planner Rona Birenbaum. Birenbaum also runs a separate fee-for-service financial planning firm called Caring for Clients. I have consulted her for various pieces in the past, particularly about annuities.

Indeed, when I was putting Viviplan through its paces, one of the big questions I had was whether there was a need for us to partly annuitize, seeing as Ruth has no employer-provided Defined Benefit pension at all (just a hefty RRSP), and I have only two modest DB pensions that are not inflation-indexed.

Viviplan’s Morgan Ulmer

Our main question was whether to make up for this lack of employer pensions by at least partially annuitizing, or what Moshe Milevsky and Alexandra McQueen call in the title of their book Pensionize Your Nest Egg. Another author, Fred Vettese in Retirement Income for Life, was in a similar situation when he reached 65 (the same month as I did) and had suggested annuitizing 30% of his nest egg at 65 and doing another 30% at age 75 (assuming CPP at 70). Our question for Viviplan was whether this would make sense for us too, or just for Ruth.

We went back and forth with Calgary-based certified financial planner and product manager Morgan Ulmer (pictured to the right). As she relates in the MoneySense piece, “it’s certainly not necessary,” since at today’s interest rates, Viviplan told her that for us a pure GIC portfolio could get us to where we want to go, with the virtue of more financial flexibility and higher final estate value. Like the other programs, Viviplan recommends delaying CPP till 70 and OAS too if possible.

Annuitize? No wrong decisions and no rush

Partial annuitization for Ruth along the lines of what Vettese suggests would result in a slightly lower estate for our daughter. “With annuities, you are making a choice between legacy and flexibility versus security and longevity protection,” Ulmer said in the plan’s written recommendations, “There are no wrong decisions here, and there is also no rush.” Continue Reading…

Using bonds for retirement will hurt your retirement income

Senior couple trying to figure out tax declaration

As some investors near retirement, their advisors recommend switching to bonds and other fixed-income investments for their retirement investments instead of holding stocks or ETFs.

To some extent, this is an understandable retirement investing strategy, since bonds can provide steady income and a guarantee to repay their principal at maturity.

Bonds will lower the long-term returns that are key to successful retirement investing

Unfortunately, using bonds for retirement may not be the best strategy. Bond prices will likely fall over the next few years because interest rates are likely to rise. Bond prices and interest rates are inversely linked. When interest rates go up, bond prices go down, when interest rates go down, bond prices for up.

Bonds have been in a period of rising prices (a bull market) more or less since 1981. That year, long-term interest rates reached an historic turning point when long-term U.S. Treasury bond yields peaked near 15%. Ever since, interest rates have gone through wide fluctuations, but they have essentially headed downward.

Today, interest rates just don’t have that much further to fall. But under certain conditions, interest rates could go substantially higher. Remember, as mentioned, when interest rates go up, bond prices drop.

Even so, brokers continue to sell bonds to their clients. That’s partly because most of today’s brokers had not yet entered the investment business when the bull market in bonds began in 1980. All they know is that bonds do tend to reduce the volatility of your portfolio, since they tend to rise when stock prices fall. Of course, bonds also generate more commission fees and income for the broker, compared to stocks, especially if you buy them via bond funds and other investment products.

That’s why we continue to recommend that you invest only a small part of your portfolio—if any—in bonds and fixed-income investments. Instead, you should aim for a diversified portfolio of well-established companies with long histories of dividends, or ETFs that hold these stocks. We recommend a number of stocks and ETFs appropriate for retirement investing in our Canadian Wealth Advisornewsletter.

We recommend this retirement investing strategy because equities are bound to be more profitable than bonds for retirement over long periods. That’s because equity returns are related to business profits, while returns on fixed-return investments are related to business interest costs.

Bonds and other fixed-return investments can add stability

Returns on your stocks are sure to be more volatile than what you earn on fixed-return investments (that includes short-term bonds). That’s because returns on stocks are related to the part of gross profit that’s left over after a company pays its interest costs. Continue Reading…

Federal tax changes and the Individual Pension Plan

By David Miller, CFP, RFP

Special to the Financial Independence Hub

Changes are coming. Small business owners and professionals can feel it like a frosty winter breeze that lets you know winter is here. It’s time to get your winter tires on and prepare for longer hours commuting and shorter daylight hours. It’s time to understand and strategize for some cold Liberal government small business tax changes that may have a significant impact on your retirement plan through the changes to the income splitting and passive investment tax rules that will take effect in 2019.

You’ve worked extremely hard growing your business, for you, your family, and your employees. You’ve taken risks and sunk a lot of money and sweat equity into your company, and in your opinion, there should be a nice reward for taking this entrepreneurial path. And you may be right; but with rising costs, interest rates and tax rule changes, it’s getting harder to remember why you got in the business in the first place.

Maybe you don’t know how the tax changes will affect you and your family. Strategies for your business that have been implemented and worked in the past, may no longer work for you. To help you avoid being left out in the cold, let’s take a quick look at one relatively underutilized strategy that still exists for small business owners and professionals: it’s called an Individual Pension Plan (IPP).

It’s all about a level playing field

You are an incorporated small business owner, top executive, doctor, lawyer, veterinarian, or dentist, over the age of 40, consistently making over $200,000 gross/year and have been paying yourself T4 salary for a few years now.  You likely know about the recent passive investment tax rule changes that make it even less enticing to save money within your corporation for retirement and you wish there was somewhere else you could save. You may be taking a T4 salaried income from your corporation instead of dividends to reduce your corporation’s gross taxable income. In turn you will lean on making RRSP contributions to reduce your annual personal tax bill.

The strategy discussed below can put you on the same playing field as a person with a Defined Benefit pension. If you were an employee of a company or government agency and qualified for a Defined Benefit pension program, you would be in a relatively rare and advantageous position. The IPP has different rules, but it is playing the same game.

A supersized RRSP

The IPP is often referred to as a “Supersized RRSP,” as in the IPP allows for you to contribute more annually than an RRSP. The extra contributions will allow you to save for their retirement like a Defined Benefit pension set up for one person. Establishing an IPP can provide you with greatly enhanced retirement benefits when compared to your regular RRSP contributions.  The company is responsible for making the contributions and is a deductible expense.

What’s in it for you and your business

It is all about how much you can save, tax deferred, for your retirement and how much tax you can save in deductions for your company today. Continue Reading…

The worst markets for the Land Transfer Tax

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

It’s no secret that purchasing a home is the largest financial investment for many households, and having a realistic budget is key to maximizing affordability. However, despite the years of careful saving and planning most prospective buyers undertake, there’s one closing cost that can present considerable sticker shock: land transfer tax.

Charged by the provincial government (as well as at the municipal level in the City of Toronto), this levy is calculated based on the total purchase price of the home. It must be paid in cash before the transaction can be completed, and cannot be covered by a home loan or rolled into a mortgage.

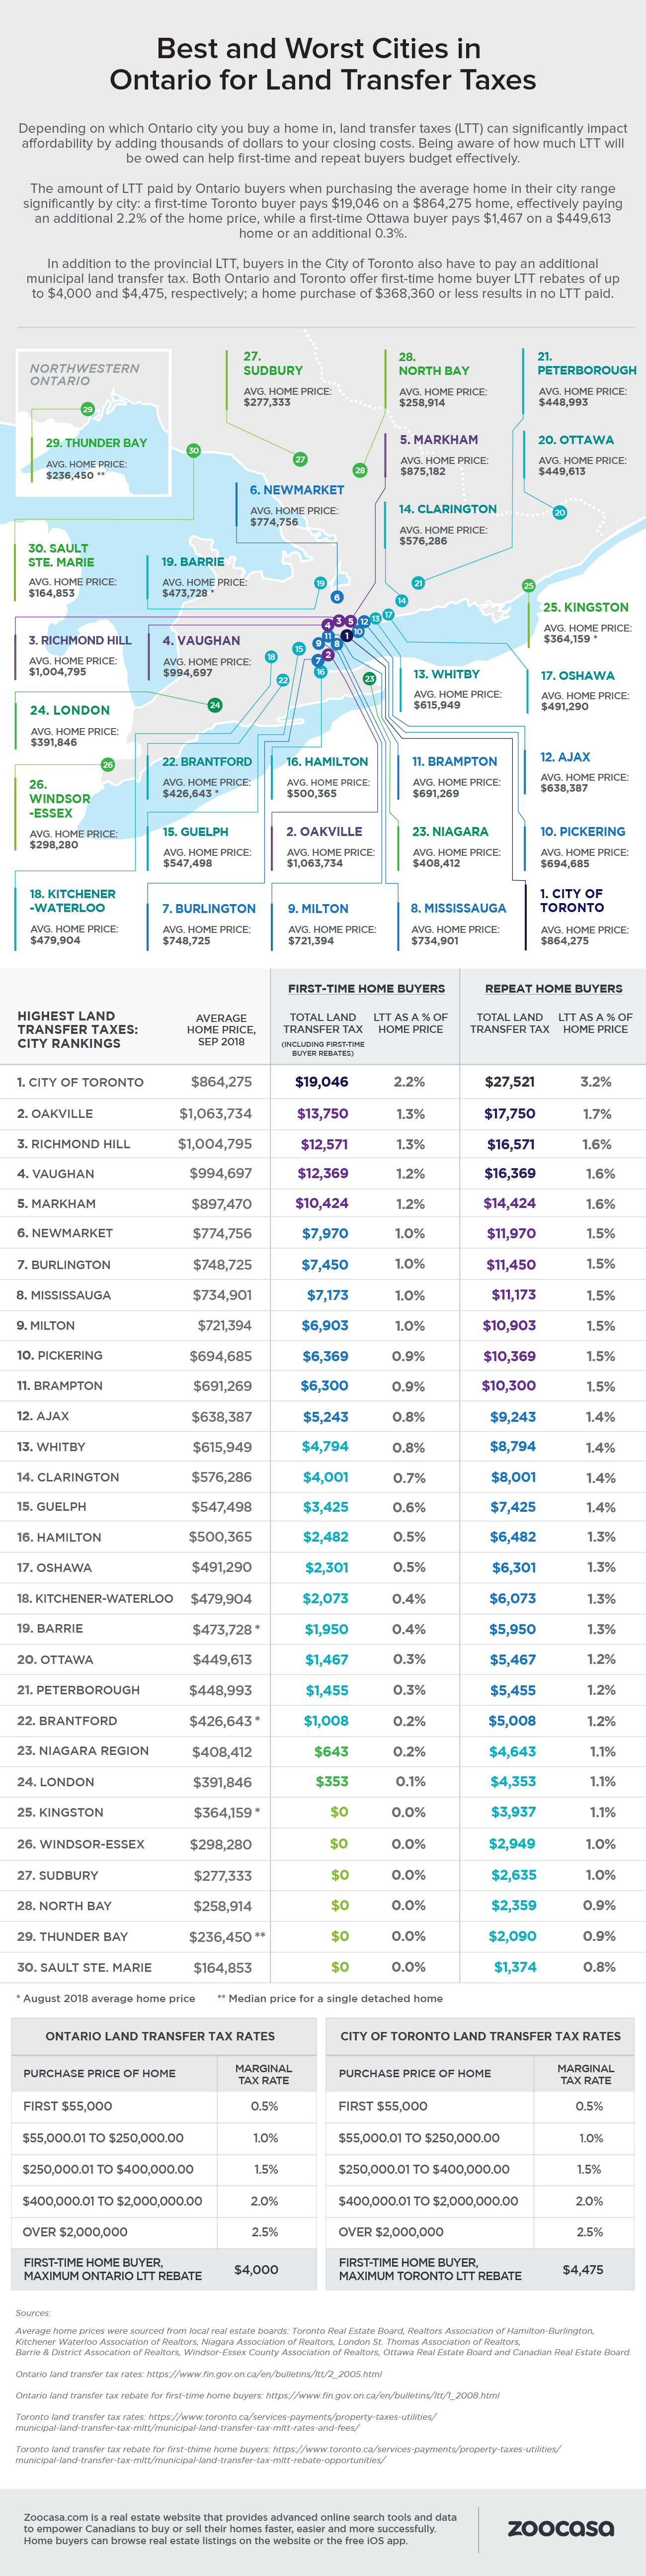
Because LTT is based on home price, this means buyers in Ontario’s priciest markets shell out much more for it than others. In fact, according to a recent cost analysis by Zoocasa, a buyer in Toronto would be taxed $27,521 for a home priced at the September average of $864,275. That’s an additional 3.2% of the total purchase price.

In Sault Ste. Marie, however, where the average home price clocks in at a relatively more affordable $164,853, said buyer would pay only $1,374 in tax, representing just 0.8% of the total home price.

However, buyers in the majority of Ontario’s more moderately-priced markets can expect to pay between $5,000 and $7,000 in LTT; someone perusing Kitchener homes for sale, which come at the average price of $479,904, would pay $6,073 in LTT. A buyer of Hamilton real estate would be taxed $6,482 on the average home price of $500,365.

Check out the infographic to the left to see how LTT can vary in housing markets across Ontario:

LTT rebates available for first-time home buyers

Fortunately for those climbing onto the property ladder for the first time, there is some relief from land transfer tax in the form of rebates: The Ontario government will refund $4,000, while the City of Toronto offers $4,475. As well, first-time home buyers paying less than $368,360 on their home – the provincial threshold for LTT – will avoid paying it altogether, a reality in markets such as Saut Se. Marie, Thunder Bay, North Bay, Sudbury, Windsor-Essex, and Kingston.

Top 5 Ontario cities where you’ll pay the most Land Transfer Tax

1 – City of Toronto: $27,531

2 – Oakville: $17,750

3 – Richmond Hill: $16,571

4 – Vaughan: $16,369

5 – Markham: $14,424 Continue Reading…