General

The Case for Financial Assets over real estate

Billy kicking back on Mexico’s Pacific Coast

By Billy Kaderli

Special to the Financial Independence Hub

When I was a stock broker in California — one of the hottest housing markets in the US — real-estate was my competition. “Everyone” was making money in real-estate, so why would they invest in the stock market?

I needed an angle

I went to the Board of Realtors and got prices for 2-, 3- and 4-bedroom homes in the area, both at the current price and for 10 years prior. I did the math to calculate what annual return these houses were creating for that ten-year span, then compared that to the S&P 500 Index for the same time period.

The index clearly beat all three home styles without the hassles of ownership. Now I had my argument to help people invest in the market.

Ok, that was then and this is now

Using Zillow.com I looked up what the home we used to own was now worth. It was listed at US$862K. Again I did the math and found that over the last 31 years since we bought it, that house has appreciated 6.4% annually. Sounds OK, except that there were property taxes, maintenance and repairs that would need to be deducted lowering that annual return.

Then, I wondered, what if we had put the money to buy our home into the S&P 500? So I calculated that figure also.

Are you ready?

It would be worth 3 million (US) dollars today! Over three times the current value of the home, as the Index produced a 10.46% annual return during those 31 years. Continue Reading…
How dividends are taxed: a close look at the dividend tax credit

Discover what you need to know to answer the question, “How are dividends taxed in Canada?”

Taxpayers who hold Canadian dividend-paying stocks get a tax break. Their dividends can be eligible for the dividend tax credit in Canada. This means that dividend income will be taxed at a lower rate than the same amount of interest income.

Investors in the highest tax bracket pay tax of 29% on dividends, compared to about 50% on interest income. Investors in the highest tax bracket pay tax on capital gains at a rate of roughly 25%.

As mentioned, Canadian taxpayers who hold Canadian dividend stocks get a special bonus. Their dividends can be eligible for the dividend tax credit in Canada. This dividend tax credit — which is available on dividends paid on Canadian stocks held outside of an RRSP, RRIF or TFSA — will cut your effective tax rate.

This means that dividend income will be taxed at a lower rate than the same amount of interest income.

How are dividends taxed in Canada? An example:

If you earn $1,000 in dividend income and are in the top 50% tax bracket, you will pay about $290 in taxes.

That’s a bit more than capital gains, which offer tax-advantaged income as well. On that same $1,000 in income, you will only pay $250 in capital gains taxes.

But it’s a lot better than the roughly $500 in income taxes you’ll pay on the same $1,000 amount of interest income.

The Canadian dividend tax credit is actually split between two tax credits. One is a provincial dividend tax credit and the other is a federal dividend tax credit. The provincial tax credit varies depending on where you live in Canada.

Note that apart from the Canadian dividend tax credit giving you a major tax-deferral opportunity, dividends can supply a big part of your overall long-term portfolio gains.

When you add in the security of stocks with dividends going back many years or decades—plus the potential for tax-advantaged capital gains on top of dividend income: Canadian dividend stocks are an attractive way to increase profit with less risk.

How are dividends taxed in Canada? Savvy investors respect the advantages of dividends

Dividends don’t always get the respect they deserve, especially from beginning investors. Continue Reading…

Why the “T” in TSX should stand for Tokyo

By Jeff Weniger, CFA, WisdomTree Investments

Special to the Financial Independence Hub


Canada’s stock market construction may be more than just a portfolio risk; it is arguably a systemic one.

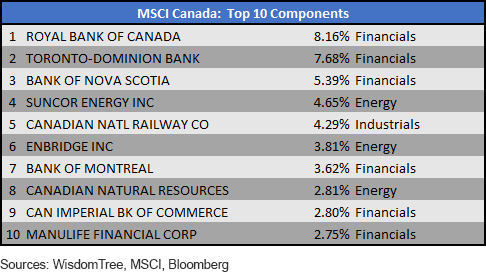
If, for whatever reason, the Canadian financial system were to encounter serious difficulty, investors would be hit by a one-two punch. The attendant economic weakness would hang over the stock market, and it would be the very companies that dominate the stock market that would be battling demons. Canada’s top-heaviness, where more than $2 of every $5 in the MSCI Canada Index is in financial stocks, is not normal or reassuring for a developed economy.1 We should stop making like it is.

In fact, it would be better for the TSX if the “T” stood for Tokyo, at least on the sector diversification side of things, as we show below.

Stuck in the mud

Everywhere you turn, countries that are top heavy are doing something about it. Saudi Arabia, for example, sees the writing on the wall for fossil fuels; either the price mechanism may cause a phase-down in oil demand in the next quarter century, or environmental action groups will crush demand themselves. Either way, the ruling Crown Prince Mohammad bin Salman is keen to avoid state failure if a bleak future for oil comes to pass. That country will soon float an IPO of Aramco, the state-run oil behemoth that may be equal to several ExxonMobils. Proceeds will be diverted into tech, infrastructure—anything that isn’t oil.

China, too, realized it was turning into a one-trick pony. After building its export machine after Mao’s death, the time for middle-class demand eventually arrived. When it joined the WTO at the turn of the century, the country’s household consumption was 46% of GDP. It fell to 36% of GDP in 2007, but it has been rising ever since; sights are set on 40% this year.2

But not Canada. The hat is hung on the same two sectors, as always. Nine of this country’s top 10 corporations by market capitalization fit the bill (figure 1). This, in a country where the average investor has 86% of assets inside these borders.3

That is concentration on top of concentration.

Figure 1: Canada’s Sector Concentrations

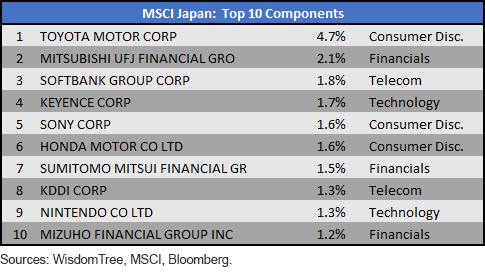
Compare the “T” for Toronto with another T: Tokyo. Figure 2 shows Japan’s national champions. They don’t dominate allocations quite like Canada’s do.

Figure 2: Japan’s Largest Companies

Continue Reading…

Why and how Financial Independence is achievable

By Jade Anderson

Special to the Financial Independence Hub

Financial independence can mean different things to different people, but the widespread definition is to be financially secure and on the right track to a safe retirement.

Sometimes people will still need to work in order to maintain their financial independence (aka “Findependence”), but the main idea is that you are free from any debt or outside help from financial institutions. This may seem like something that is unachievable for anyone outside of retirement age, who isn’t well established; however, because of the different types of financial independence, it may not be so difficult after all. Adjusting your spending habits, creating a budget for your self and several other things can lead you towards Findependence, if you know the right things you need to consider.

Reduce unnecessary expenses

Setting up a budget for the long term is extremely important if you’re wanting to become financially independent. If you can cut down on any unnecessary expenses (such as extra food, clothing, and entertainment) in your weekly spending, then you’ll find it will be a lot easier to save. If you are not used to saving money, starting small is important because it will help you establish a pattern of saving properly, and it will be easier for you when you move up to saving more of your average income.

Plan your savings and spending

Planning not only your savings, but also your spending is crucial for ensuring your financial independence. If you have a few debts, and you can make plans to pay off certain amounts by certain dates, you’ll find that the overall debt is easier to pay off, than if you paid it off in a lump sum. Using one of the financial calculators like those on Brighter Finance can help you calculate your budget and repayment periods for your loans, so you can keep track of your money more easily.

Continue Reading…

FP: A look at three retirement income planning software packages

My latest Financial Post column looks at a few retirement income planning software packages that help would-be retirees and semi-retirees plan how to start drawing down from various income sources: Click on the highlighted text to retrieve the full article: How you draw down your retirement savings could save you thousands: this program proves it.

There may be as many as 26 distinct sources of income a retired couple may encounter, estimates Ian Moyer, a 40-year veteran of the financial industry and creator of the Cascades program described in the article.

When he started to plan for his own decumulation adventure, five years ago, he felt there was very little planning software out there that was both comprehensive and easy to use. So, he hired a computer programmer and created his own package, now called Cascades.

While the main focus of the FP article is on Cascades, (available to financial advisors for $1,000 a year; do it yourself investors can negotiate a price directly), the article also references a couple of other programs we have looked at previously here on the Hub: Doug Dahmer’s Retirement Navigator and BetterMoneyChoices.com, the latter currently nearing the end of beta testing.

Dahmer has been writing guest blogs on decumulation here at the Hub almost since this site’s founding in 2014. See for example his most recent one, or the similar articles flagged at the bottom: Top 10 Rules for Successful Retirement Income Planning.

Dahmer says he’s pleased that others are waking up to the need for tax planning in the drawdown years: “Cascades provides a very good, easy-to-use introduction to these concepts.”

Planning for peaks and valleys in spending

Retirement Navigator’s Doug Dahmer

However, Dahmer would like an approach that doesn’t assume yearly spending remains relatively static: his Better Money Choices(available on line for $108 a year) allows for the “peaks and valleys” of spending as retirees pass through their Go-go to their slow-go and finally their “no-go” years.  Most retirees have to plan for sporadic large purchases like renovations or replacement of roofs or furnaces, plus of course vacations with widely varying price tags. Each spending peak represents a tax challenge, while the valleys are where the tax planning opportunities exist. Dahmer likens Better Money Choices to a gym monthly membership and Retirement Navigator to a personal trainer.

Personally, I found going through both firm’s programs a fascinating exercise, very much like putting together a jig saw puzzle. For me, Better Money Choices helps you visualize the final picture you’re trying to assemble, showing how much money you’ll need and when you’ll need it. Cascades provides vivid yearly snapshots of your year-by-year progress in putting the pieces together.