General

Vanguard Canada unveils low-cost actively managed mutual funds

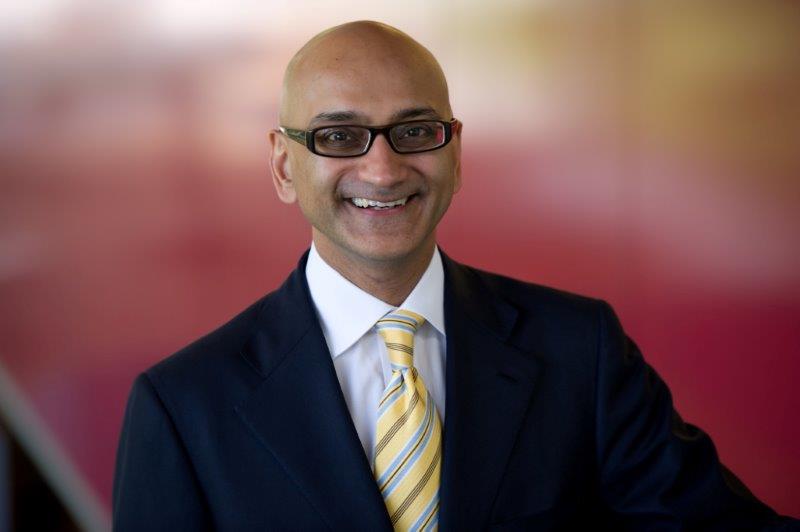
Vanguard Canada’s Atul Tiwari

On the heels of its three asset allocation ETFs that shook up Canada’s investment industry in February, Vanguard Investments Canada Inc. today announced it will be providing four new low-cost actively managed mutual funds to the Canadian market.

The four new mutual funds are its first actively managed products for the domestic market: until now, it has been providing 36 exchange-traded funds (ETFs), with more than C$16 billion in assets. Vanguard says Canadians hold more than C $28 billion in Vanguard investments if you include both its Canadian products and its funds trading on US stock exchanges.

All four of the new active mutual funds are globally diversified: Vanguard says its management fees are about half that of the mutual fund industry average in Canada. (According to the Investment Funds Institute of Canada here, the average total cost of ownership of mutual funds for clients using advice-based distribution channels in Canada at the end of 2016 was 1.96% when taxes are excluded.)

IFIC has said these costs continue to fall and there’s little doubt Vanguard’s entry will accelerate the trend, and not a moment too soon, given last Thursday’s disappointing proposals from the Canadian Securities Administrators. (See the Hub’s roundup here or my Motley Fool Canada blog here).

In a press release distributed at 8 am Monday, Vanguard said the four new funds “feature global investment strategies from some of Vanguard’s longest-tenured sub-advisors” and complement its broad-based lineup of ETFs.

Vanguard Canada managing director Atul Tiwari (pictured) said “Vanguard has a deep 40-year history of active management expertise and we are excited to extend that to mutual fund investors in Canada, at a low cost … These mutual funds reflect our philosophy as an organization with a disciplined long-term approach and world-class investment managers that have worked with Vanguard for decades.”

Despite the fact The Vanguard Group Inc. pioneered index funds and low-cost passively managed investing (with more than US$5 trillion under management), it is also one of the world’s largest active managers, with US$1.2 trillion in global actively managed assets. The key contributing factors to successful active management are low costs, talent and patience, said Tim Huver, Vanguard Canada’s head of product.

Pricing varies with investment performance

Vanguard says it will use a unique pricing structure in the Canadian marketplace that aligns the interests of the sub-advisors with the funds’ investors. The maximum management fee for each mutual fund will be 0.50% and the management fee will vary up or down, up to that maximum amount, based on the investment performance of each fund.


Mutual Fund Maximum Management Fee First Year Management Fee
Vanguard Global Balanced Fund


0.50% 0.38%
Vanguard Global Dividend Fund


0.50% 0.34%
Vanguard Windsor U.S. Value Fund 0.50% 0.35%
Vanguard International Growth Fund 0.50% 0.40%


The first year management fee shown above is effective from June 25, 2018 to June 30, 2019. The funds will be available to financial advisors through Series F units and institutional investors through Series I units.

Canadian investors currently hold $1.5 trillion in mutual funds, according to Tiwari. “Vanguard has a long track record of lowering investment costs in the areas in which we operate, so we see providing greater choice and lower costs to a broader group of investors as very positive.”

More on the four actively managed global mutual funds Continue Reading…

Dear Generation X: Here’s how to fix your Finances

But let’s skip the scaremongering and over-generalizations and get to some common sense advice.

How do you balance paying off debt, saving, and investing with the everyday costs of supporting a family? Let’s start by setting up a simple plan for each of these categories to ensure that you are on the right financial path. Here’s how to fix Generation X finances:

Treat consumer debt like a financial sin

You can’t move the needle forward financially if you’re constantly spending more than you earn. But when your mortgage payment, car payment(s), daycare costs, groceries, and gas take up your entire available budget then you have no wiggle room to plan for unexpected costs.

Not only that, when the “I deserve this” moments come up and you want to treat yourself or your family to dinner, a movie night, or a vacation you end up going into debt (just this one time) to make ends meet.

Start with a list of everything you currently spend over a period of three months. Where does all your money go? Find a way to slash expenses so that you’re no longer going into debt just to get through the month.

Make it a rule: No new debt this year

Now it’s time to tackle your current debt, whether that’s in the form of a lingering line of credit or (gasp!) a high-interest credit card. If it’s the latter, put all savings and extra spending on hold and throw every extra dollar at that debt until it’s paid off.
Continue Reading…

Overhaul of mutual fund fees not as sweeping as some would like

Deferred Sales Charges (DSC) on mutual funds are going to be eliminated in Canada but recommendations released today by securities regulators did not go so far as to implement an outright ban of trailer commissions (aka trailer fees, also referred to as embedded compensation.)

The Canadian Securities Administrators (CSA) also released proposals regarding rules about what advice or products are in the “best interest” of financial consumers.


You can find a full summary in this article that appeared today in the Globe & Mail. (The full link may only be available to G&M subscribers, depending on how many free views readers have previously accessed). Rob Carrick also has a column on the topic titled It just became clear we’ll never see an investment industry where clients must come first. Well, we’ll see. Over at the Financial Post, Barbara Schecter reports OSC drops push for adviser standard.

Big win for industry

For more of an industry perspective, there is a full report here at Advisor.ca. And the industry’s newspaper, Investment Executive, headlined its coverage as “a big win for the industry.”

John De Goey

One of the sources cited in both G&M articles is John De Goey, an investment adviser and author, who also sent this email to the Hub expressing his disappointment in the decisions:

“This is shameful on the part of the CSA.  It has been almost 15 years since Julia Dublin’s Fair Dealing Model drew attention to the concern of bias caused by embedded commissions.”  He also offered these four observations:

  • The primary concern is advisor bias as caused by embedded compensation, and there’s nothing here to address that
  • Does not allow for “product meritocracy”
  • Does not address how the trailing commission on equities is double the trailing commission on income (which creates obvious, massive, self-evident advisor bias)
  • Does nothing to address the discrepancy between ETFs and mutual funds.  Advisor’s preferred business model should never drive product recommendations


Vanguard says industry will organically evolve away from embedded compensation

Vanguard Canada’s Atul Tiwari

However, Vanguard Investments Canada Inc. managing director Atul Tiwari said Vanguard is “encouraged by some of the proposals from the CSA. Although there will not be a ban on embedded commissions, we believe that the Canadian market, like other regions around the world, will organically evolve away from it. The CSA has made clear that suitability determinations will need to be in the best interests of clients. This will likely accelerate the move that we are already seeing in advisors going from commission-based to fee-based models. We support that trend as providing superior fee transparency and enhancing the use of low cost products to give clients better long term returns. Vanguard will continue to champion the interests of Canadian investors with more low-cost and high-quality product options.”

And finally, my take on this at the Motley Fool

(Added on Friday afternoon): You can find my own take on this development in my monthly blog at Motley Fool Canada. Click on the highlighted headline here: New mutual fund advice guidelines underwhelm advocates for Consumer-Investors.


Why starting your own business is better than getting a job

By Savannah Wardle

Special to the Financial Independence Hub

Instead of getting a job, make a job. You can take a large vacant place where a business should have been and fill it with everything you’ve ever dreamed of. If you’re on the verge of a major career change, you have the unique ability to customize that change to your needs. It might be time for you to branch out on your own and do things for yourself: you can wind up better off for having done it.

It’s easier than it used to be

The internet revolutionized the way that people run businesses. It used to be that people were confined to working for someone else because they didn’t have the resources they needed to become fully independent. Now, almost everything you can’t do yourself can easily be outsourced to software, apps, or freelancers who know how to get things done the right way. It doesn’t matter if you need to hire a Twitter expert, have a catering website built, or find specialty garage door software. The internet has it, and you can use it to build your own empire.

You’re free to explore Innovation and Creativity

Think about all the aspects of your old job that were holding you back. Did you have bold new ideas that you were dissuaded from pursuing because they didn’t adhere to the company’s “play it safe” motto? You don’t have to worry about that anymore. You’re the one calling the shots, and if you know you have the potential to shake up your industry, no one is stopping you. You can try and try and try, even if you fail, and you don’t need to worry about the powers that be restricting you from exploration.

You can live the way you want  

If you used to work long hours and weekends, you probably felt like you were missing out on life. If you run your own business, you can be open from 9 to 5 on weekdays. Close up shop for dinner and the weekends and live your life. A lot of people cite work/life balance as being one of the reasons they opt for a career change, and if you’re one of those people, you can easily find the exact balance you want by becoming an entrepreneur or an independent contractor.

You get to build your dream team Continue Reading…

What the first week of Retirement is really like

By Fritz Gilbert, RetirementManifesto.com

Special to the Financial Independence Hub

I have no idea why I’m fascinated by the “First Week Of Retirement,” and I’m curious if others also wonder about it? I suspect many do and dedicate this post to those of you who wonder what the first week of retirement is really like.

Now that I’m living the first week of retirement, how would I describe it? Is it what I thought it’d be, or is it different? Is it a big deal, or just another week? Is it weird, or normal? Is it scary, or exciting?

Yes to all of that. And no to all of that.

What does Retirement taste like?

Have you ever tried to explain what something tastes like? Let’s go with chocolate, as an example. How would you describe it? What words would you use? Describing the first week of retirement is like describing the taste of chocolate. It’s really good, but it’s hard to describe.

Yeah, the first week of retirement is alot like that.

It’s good, but I can’t think of the right words to describe it. Regardless, today we’re going to try.

What the first week of Retirement is really like

Is It Like Taking A Vacation?

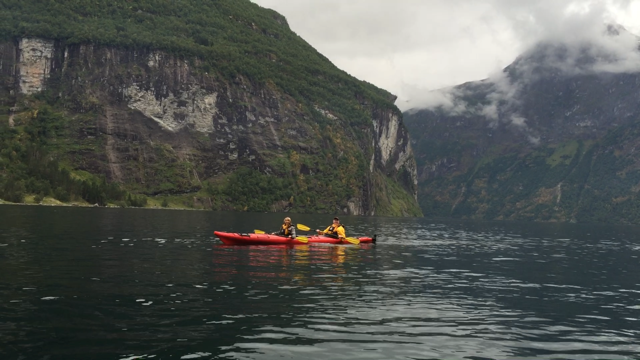
A Vacation In Norway. Is it like that?

As I write these words, I’m 5 days into my retirement (a true rookie). Is the first week of retirement like being on vacation? On one hand, kinda sorta, but that falls far short of describing the reality. It’s similar in that you’re off work for a few days, but it’s very, very different in the knowledge that You’re Never Going Back To Work.is


A Vacation that never ends will always feel different than a two-week vacation. Full Stop. So, imagine the first half of your vacation, where you’re all pumped up and excited. But you know it lasts for the rest of your life. Yeah, it’s more like that.

Only different.

I love swimming in my local mountain lake.

Is it like Saturday every day?

With less than a week of retirement under my belt, the “Saturday” analogy seems to be a better description of what the first week of retirement is really like. Like the Saturday’s you’ve experienced for decades, you’re free to do what you want to do. You’re ok letting your email go unchecked for a day or two. You can stay up later, you can sleep in.

You’ve got time to head up to the lake for that swim.

But it’s different because you know that there’s no Monday looming on the horizon.

What’s chocolate taste like?

Yeah, it’s hard to describe.

Is it scary, or exciting?

I had a friend ask me if I was “scared.” I answered that I was 98% excited and 2% scared. Sure, there’s some apprehension, but it’s a really small piece of my mindset in Week 1. At this stage of the game, I’m just learning my way around this thing called retirement, and enjoying the sensation of the very first Tastes Of Freedom I’ve worked so hard to earn. It’s only scary if you make it scary.

I know we’ll travel through many phases during our retirement journey, and I’m sure some will be more “scary” than others. We’re planning to take it all in stride. One day at a time, with some thoughts on where we want this thing to lead while leaving some freedom to enjoy the Serendipity of the thing.
You can choose what you want your retirement to be. Don’t choose scary. Life’s too short.

Choose the attitude with which you’ll live your life.

I’m choosing excited (and yeah, just a wee bit scared). Continue Reading…