General

How do Canadians feel about the new Real Estate regulations?

By Penelope Graham, Zoocasa

Special to the Financial Independence Hub

The anniversary of the implementation of the Ontario Fair Housing Plan has come and gone, and the playing field is just starting to even in the province’s housing market. Designed to cool demand and price growth in the Greater Golden Horseshoe, the 16-part package of housing regulations has effectively done just that, with sales down double-digit percentages throughout the region, and prices softening for the most expensive housing types.

Housing analysts argue that this result is mainly due to psychological factors, rather than the new regulations – which include a foreign buyer’s tax, and overarching rent controls – themselves.

But what do Ontarians really think about the new regulations? To find out, Zoocasa conducted a survey of 1,400 respondents on their sentiments around the highlights of the plan, and whether they support the government’s intervention in the free housing market.

Following BC’s footsteps

If Ontario’s attempt to tax foreign purchasers of real estate seems familiar, that’s because it closely resembles what occurred in British Columbia; the province initially implemented a 15-per-cent levy on foreign buyers within the Metro Vancouver area in August 2016, before upping the tax to a full 20 per cent, and extending the affected geographical area, in February of this year.

While Ontario’s version, called the Non-Resident Speculation Tax (NRST) still taxes just 15 per cent of a home’s purchase price, it will apply to anyone buying a home within the GGH – including homes for sale in Hamilton, or condos for sale in Mississauga, who is not a Canadian citizen or permanent resident (those who obtain such status, or who are enrolled in a minimum two-year full-time post-secondary program within a year of their home purchase are eligible for a full rebate on the NRST).

At the time of its implementation, former Ontario premier Kathleen Wynne was adamant that the tax was not intended to discourage newcomers to Canada from settling in Ontario.

“The Non-Resident Speculation Tax has nothing to do with new Canadians or people who want to make Ontario their home,” she stated to a media scrum on April 20, 2017. “This is targeting people who are not looking to raise a family, who are just looking for quick profit or a place to park their money.”

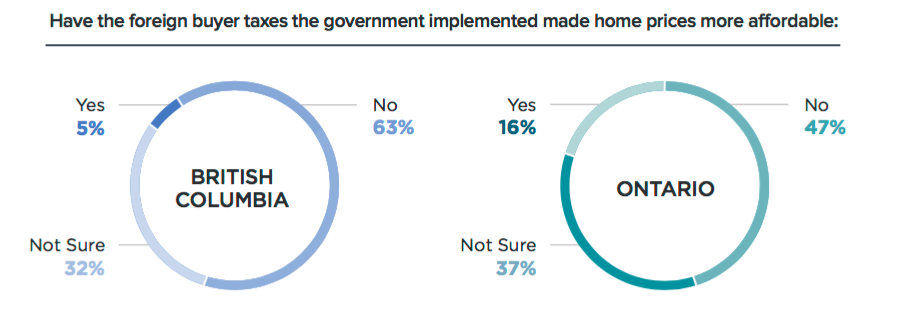
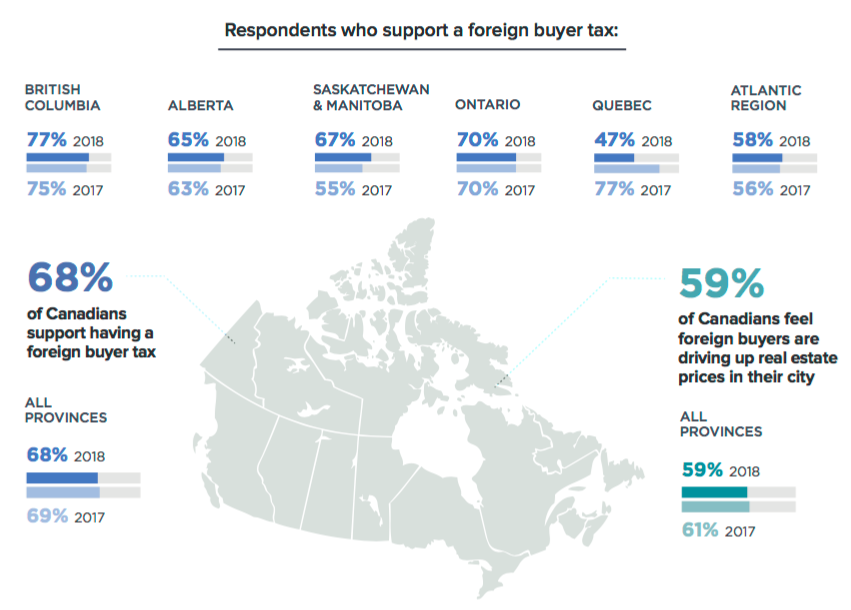
The measure appears to have resonated well with all Canadians; according to survey results, 69 per cent of respondents from all provinces indicated they support the tax, while 61 per cent felt foreign ownership directly impacts prices in the local housing market.

Perhaps not surprisingly, respondents from provinces with the most competitive real estate marketplaces were most likely to support the tax: 77 per cent of British Columbians and 70 per cent of Ontarians indicated they were pro-tax.
Support extends beyond affected Housing markets

However, even respondents from provinces where foreign investment and homeownership is not considered a stressor on the market, indicated support for the tax; 65 per cent of Albertans indicated support, even though only 40 per cent feel out-of-country buyers impact housing prices in their region. Continue Reading…

Investing for people over or under 45

By Tea Nicola

(Sponsor Content)

Your ideal investing strategy when you’re 25 just is not the same as when you’re 52.

That’s because what you earn is partly a function of what you’ve already managed to acquire. In Canada, about 85% of all financial assets are in the hands of people over age 45. Pension assets are held in the same proportions. On the real estate front, just 32% of all real estate value is in the hands of those under age 45. Meanwhile, fewer companies today offer a pension plan of any kind. The defined benefit pension plan is on its way to extinction.

What’s a young person to do? And for older investors who are going to retire earlier, how should their investment strategy change? What are the lessons that need to sink in when it comes to investing for people over or under 45?

What’s the investment strategy for Canadians under 45? Lower your fees!

You’re finished with school (at least for now). You’ve entered the job market and you’re starting to build up some savings. You’re diligently putting between 10 and 20 per cent of your salary into an RRSP. The younger you start to contribute to an RRSP, for instance, the sooner you can take advantage of compound interest.

Regardless, you want a good return on your investment and maybe you’ll get lucky and enjoy a bull market.

You can’t actually control that return, even if you’re investing in your own company … but if you’re using an investment platform like WealthBar or a traditional firm, you definitely can control how much you pay in fees.

For instance, with a WealthBar account, an investor might pay about 0.6% in management fees to WealthBar, versus 2.2% for a mutual fund at a bank. Put another way, an investor might pay $10 a month for WealthBar to manage $25,000, versus nearly $46 per month with a typical bank mutual fund.

Fees add up! While it may seem like the older generation controls the vast majority of assets (OK, they do), young people can at least control how much they pay a firm to manage their account. The right choice can literally save hundreds of thousands of dollars in value that would otherwise pad a financial adviser’s pocketbook.

But, should you race to the bottom? Perhaps not. Ensure that your strategy is still sound and diversified in order to achieve your goals in time. So, do not invest all your money into that 0.05% US Equity ETF. Some fees are ok, if they provide value such as diversification, cash flow, currency alignment and liquidity.

What’s the investment strategy for Canadians over 45? Reduce your risk!

Perhaps you’re one of the lucky Canadian investors over 45 who has had a good run. A pride-inducing chunk of that 85% chunk of financial assets are in your account. Continue Reading…

Retired Money: How to be financially, physically and emotionally fit for Retirement

My latest MoneySense Retired Money column, which has just been published, looks at a self-published book by the semi-retired (at age 64) Howard Pell. His book is titled Retire Fit, Fit & Fit. Click on the highlighted headline to retrieve the full MoneySense column: Retirement fitness involves mind and body, as well as money.

So what does the Fit, Fit & Fit mean? It’s in the headline of this blog as well as the adjacent photo taken from the book cover, which is the book’s subtitle. So it’s referring to being all three of financially fit, physically fit and emotionally fit for Retirement.

There are plenty of books about financial fitness so Pell pays only lip service to that aspect: what he brings to the table is insights on how to integrate finances with physical and emotional fitness. (To some extent, so does the book I co-authored with Mike Drak: Victory Lap Retirement)

Pell, who is based in Waterloo, Ont., does add a few newish terms to the semi-retirement lexicon.  He dubs the lifestyle “voluntary unemployment” but like many at this stage, finds the word “retired” inadequate. He tosses out several alternatives but the best one is his suggestion to simply adopt the Spanish word for “retired,” which is Jubilado (for males) or Jubilada (for females.”) He would use the term to signify anyone who is financially, physically and emotionally fit.

I can certainly relate to his observation of the semi-retired life that  “The big difference is that now all my deadlines and commitments are self-imposed.” Of course, as the old quip goes about driven self-employed business people: “My boss is a slavedriver.”

Pell also went personally through the “glide path” to semi-retirement described in other Retired Money columns and here at the Hub, via working a three-day week for his then employer during the last two years of his time there. This is a good way to test out your financial fitness while also clearing time for more physical fitness and — perhaps the toughest challenge — preparing for emotional fitness for retirement (I’m speaking for myself here.)

Finding the sweet spot

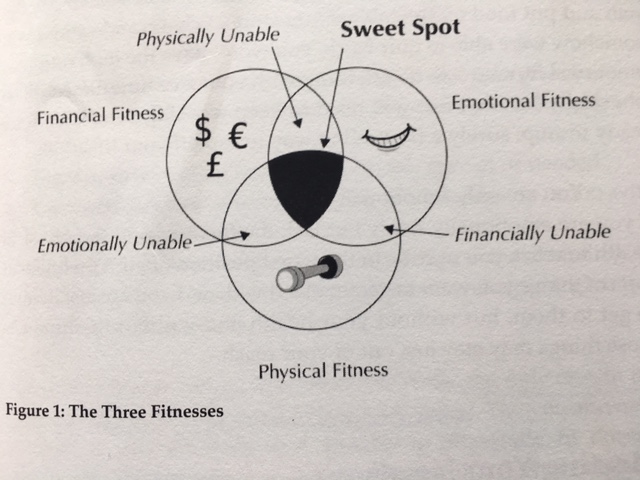
A Venn diagram on page 7 of Pell’s book (shown adjacent) illustrates that the sweet spot is the intersection where financial, emotional and physical fitness all converge.

If they don’t, and you became financially fit by selling out either your physical and/or your emotional health, the retirement your finances make possible may be a very limited and unsatisfying one.

It’s also possible to be only physically fit or only emotionally fit but lack the financial resources for retirement. The need to keep working to pay the bills will be frustrating, especially if all your peers have retired.

Continue Reading…

How in sync are global Central Banks?


By Kevin Flanagan, WisdomTree Investments

Special to the Financial Independence Hub

Without much fanfare, the U.S. Federal Reserve (Fed) provided its policy guidance late in May. Although no rate hike was implemented [it raised its overnight lending rate by 0.25% at 2 pm today, June 13, at 2 pm: Editor]  the money and bond markets fully expect the U.S. central bank to continue on its tightening path for the remainder of 2018, if not beyond. While the lion’s share of the focus has been Fed-centric on this front, it seems like a good exercise to check in on what the expectations are for the developed world’s other key monetary policy makers.

Heading into 2018, optimism for ongoing global growth seemed to be the norm. Indeed, along with the outlook for continued global growth, discussions were arising on whether central banks would soon turn their attention to any potential increase in inflation. While we still have almost seven months to go in this calendar year, recent data appears to be suggesting a plateauing of sorts on the economic front.

One economic indicator that is widely watched for help discerning economic trends on a global basis are the various Purchasing Managers’ Indexes (PMI) on a country or regional basis. While the levels being posted in the developed world still point toward further expansion, they don’t necessarily indicate a pick-up in growth prospects on the immediate horizon. In fact, the readings for April on an aggregate basis were relatively flat, and in some cases — such as the eurozone, the UK and Canada — have actually slipped a bit from their recent peaks.

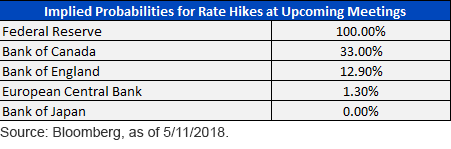
So, what should investors expect in near-term global central bank policy? As illustrated in the table above, expectations for the upcoming policy meetings certainly differ quite a bit. The overarching outlook is for the Fed to raise rates at its convocation on June 13, with the Fed Funds Futures implied probability being 100%, as of this writing. The remaining four developed world central banks — the European Central Bank (ECB), the Bank of England (BOE), the Bank of Canada (BOC) and the Bank of Japan (BOJ)  — all fall in the “no rate hike” camp. Continue Reading…

The reverse mortgage pitfalls you need to know about

Canadian seniors may borrow on their home equity in the form of a reverse mortgage — but should they?

Money lenders are always coming up with innovative ways for you to borrow money. One such innovation is the reverse mortgage. Interest in reverse mortgages is rising with an aging population and low interest rates on savings accounts. As a result, we hear from our Inner Circle members periodically asking whether a reverse mortgage would be a good way to tap into the equity they have built up in their homes.

Reverse mortgages in Canada let homeowners who are 55 years of age or older borrow on their home equity—the minimum age was 60 until a year ago. (For married couples, both spouses must be above age 55). Typically, the loan-to-value ratio is up to 40%. But depending on their age and property, some borrowers may qualify for a loan of up to 55% of the value of their home. The loan and accumulated interest are repaid only after the house is sold or from the proceeds of the homeowner’s estate.

Reverse mortgages are best seen as loans of last resort

Continue Reading…