General

5 sensible steps to improve your 2018 game plan

“Your future depends on many things, but mostly on you.”
—Frank Tyger (1929–2011), cartoonist, columnist and humourist
Designing the investment plan for the long haul requires much serious thought. Unfortunately, investors shortchange themselves on two fronts. Firstly, they spend far too much time selecting investments. Secondly, and more important, they spend too little time researching and establishing their investment policies and strategies. The ones that the plans should put into effect to reach personal goals.

In my experience, few investors actually have a sensible game plan that is being followed. Too often, this results in a collection of “flavour of the day” investment selections. Designing the appropriate investment plan is essential, particularly the asset mix targets.

“Understanding the major investment risk factors brings perspective to the plan. The ability, willingness and need to take risks are your top three.”

Happily, this situation is easy to rectify. A new year is about to make its grand entrance. Let us take a breather to contemplate a few improvements.

Stewarding the finances is truly a long journey. If you were my client, I would start with this question, “What is important about investing to your family in 2018 and beyond?”

My observation is that many investors opt for preservation of capital. Others focus on portfolio growth. The rest concentrate on the retirement income stream. Lifestyle needs are also high on the pecking order.
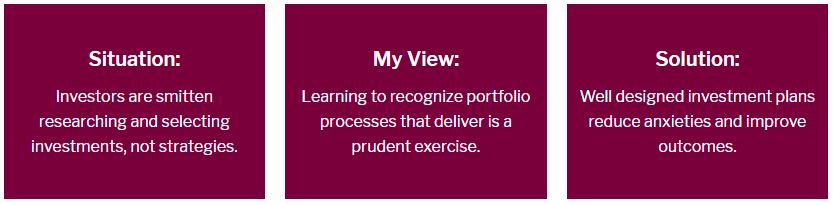
I touch on a handful of key steps in designing your game plan:

1.) Retirement prospects

Determine the family’s desired retirement income goal in today’s dollars. Calculate the size of portfolio to reach and sustain the goal. This provides portfolio direction and purpose. Estimate the personal rate of return required to achieve the retirement nest egg ballpark. Then treat that rate of return as the “investment benchmark” for the game plan.

Once the personal rate of return is identified, there is likely no need to incur higher investment risk than necessary. This is especially important to retired investors. Consider all the investment accounts owned as part of the big picture, not in isolation. Revisiting your “asset location” best practices helps fine tune the game plan.

2.) Investor profile

Analyze which type of investor profile suits and feels best. The most familiar ones are labeled as preservation, income, balanced, growth and aggressive. In my experience, investor profiles change infrequently.

The majority of investors are comfortable within 40% to 60% allocated to stocks and the remainder to cash and bond selections. For example, a balanced profile typically allocates about 50% to stocks, 40% to bonds and 10% to cash instruments.

3.) Asset mix 

Asset mix decisions have the greatest impact on portfolio outcomes than any other factor. Studies show that these decisions explain a substantial amount of variations in total portfolio returns. Continue Reading…
Advanced RRSP Strategies (Beyond the Basics)

RRSPs are a valuable tool for many taxpayers, which is why they are the backbone of many retirement plans. Getting the most out of your RRSP often involves thinking several years ahead, rather than just when the contribution deadline is looming.

Here are five RRSP strategies to get you thinking beyond the basics:

Claiming RRSP deductions

Most of us claim our RRSP deductions in the tax year we make the contribution, but you don’t have to. In fact, you can choose to deduct only a portion or none at all and carry it forward.

If you expect to move into a higher tax bracket next year from say, a big promotion, or the sale of rental property, you should still make your contribution to take advantage of tax-free compounding. But, it may be worth waiting to claim the deduction the next year (or later) when your marginal rate will be higher and you will get a substantially bigger tax refund.

Level out income

Continue Reading…

How to build a sound and profitable Retirement portfolio

By Patrick McKeough, TSINetwork.ca

Special to the Financial Independence Hub

To decide if an investment belongs in your portfolio for retirement, you need to take a close look at its attributes or features. But, just as important, you need a close look at how well the investment suits your needs. A superficial look can steer you in the wrong direction.

From time to time, for instance, investors say “Now that I’m retired, I can’t invest in stocks any more. I can’t risk a 30% to 40% drop in the value of my portfolio.” But these same investors may buy annuities without considering the fact that annuity rates are related to bond yields. Both are at historically low levels. A revival of inflation could do extraordinary damage to the purchasing power you get from the fixed returns on bonds or annuities.

Retirement planning and four key factors to consider when investing for retirement

Retirement planning is the process of setting retirement goals, estimating the income needed to meet those goals and assessing your potential sources of retirement income. These days, more investors suffer from what you might call “pre-retirement financial stress syndrome.” That’s the malady that strikes when it dawns on you that you don’t have enough money saved to be able to earn the retirement income stream you were banking on. The best way to overcome this is with sound investing.

Additionally, here are four key factors to consider for retirement saving:

  • How much you expect to save prior to retirement;
  • The return you expect on your savings;
  • How much of that return you’ll have left after taxes;
  • How much retirement income you’ll need once you’ve left the workforce.

Should you consider investment products in your portfolio for retirement?

The financial industry has created income-producing investment products to cater to investors who are wary of stock-market uncertainty. These products can provide steady income that’s higher than bond interest, or dividend yields from stocks. However, these products are almost always subject to hidden fees and risks that continually drain your capital, or leave it vulnerable to unexpected losses.

Successful investors understand that occasional market plunges are normal and unavoidable. A drop of 30% to 40% in stock prices is rare. But after the plunge ends, stocks bounce back and eventually recover. Meanwhile, if you follow our Successful Investor approach, you’ll still have dividend income. What’s more, you don’t need to (and probably won’t) sell at the low in prices.

You can maintain reserves for your cash flow needs by selling some stocks every year, during times of high and low prices.

Continue Reading…

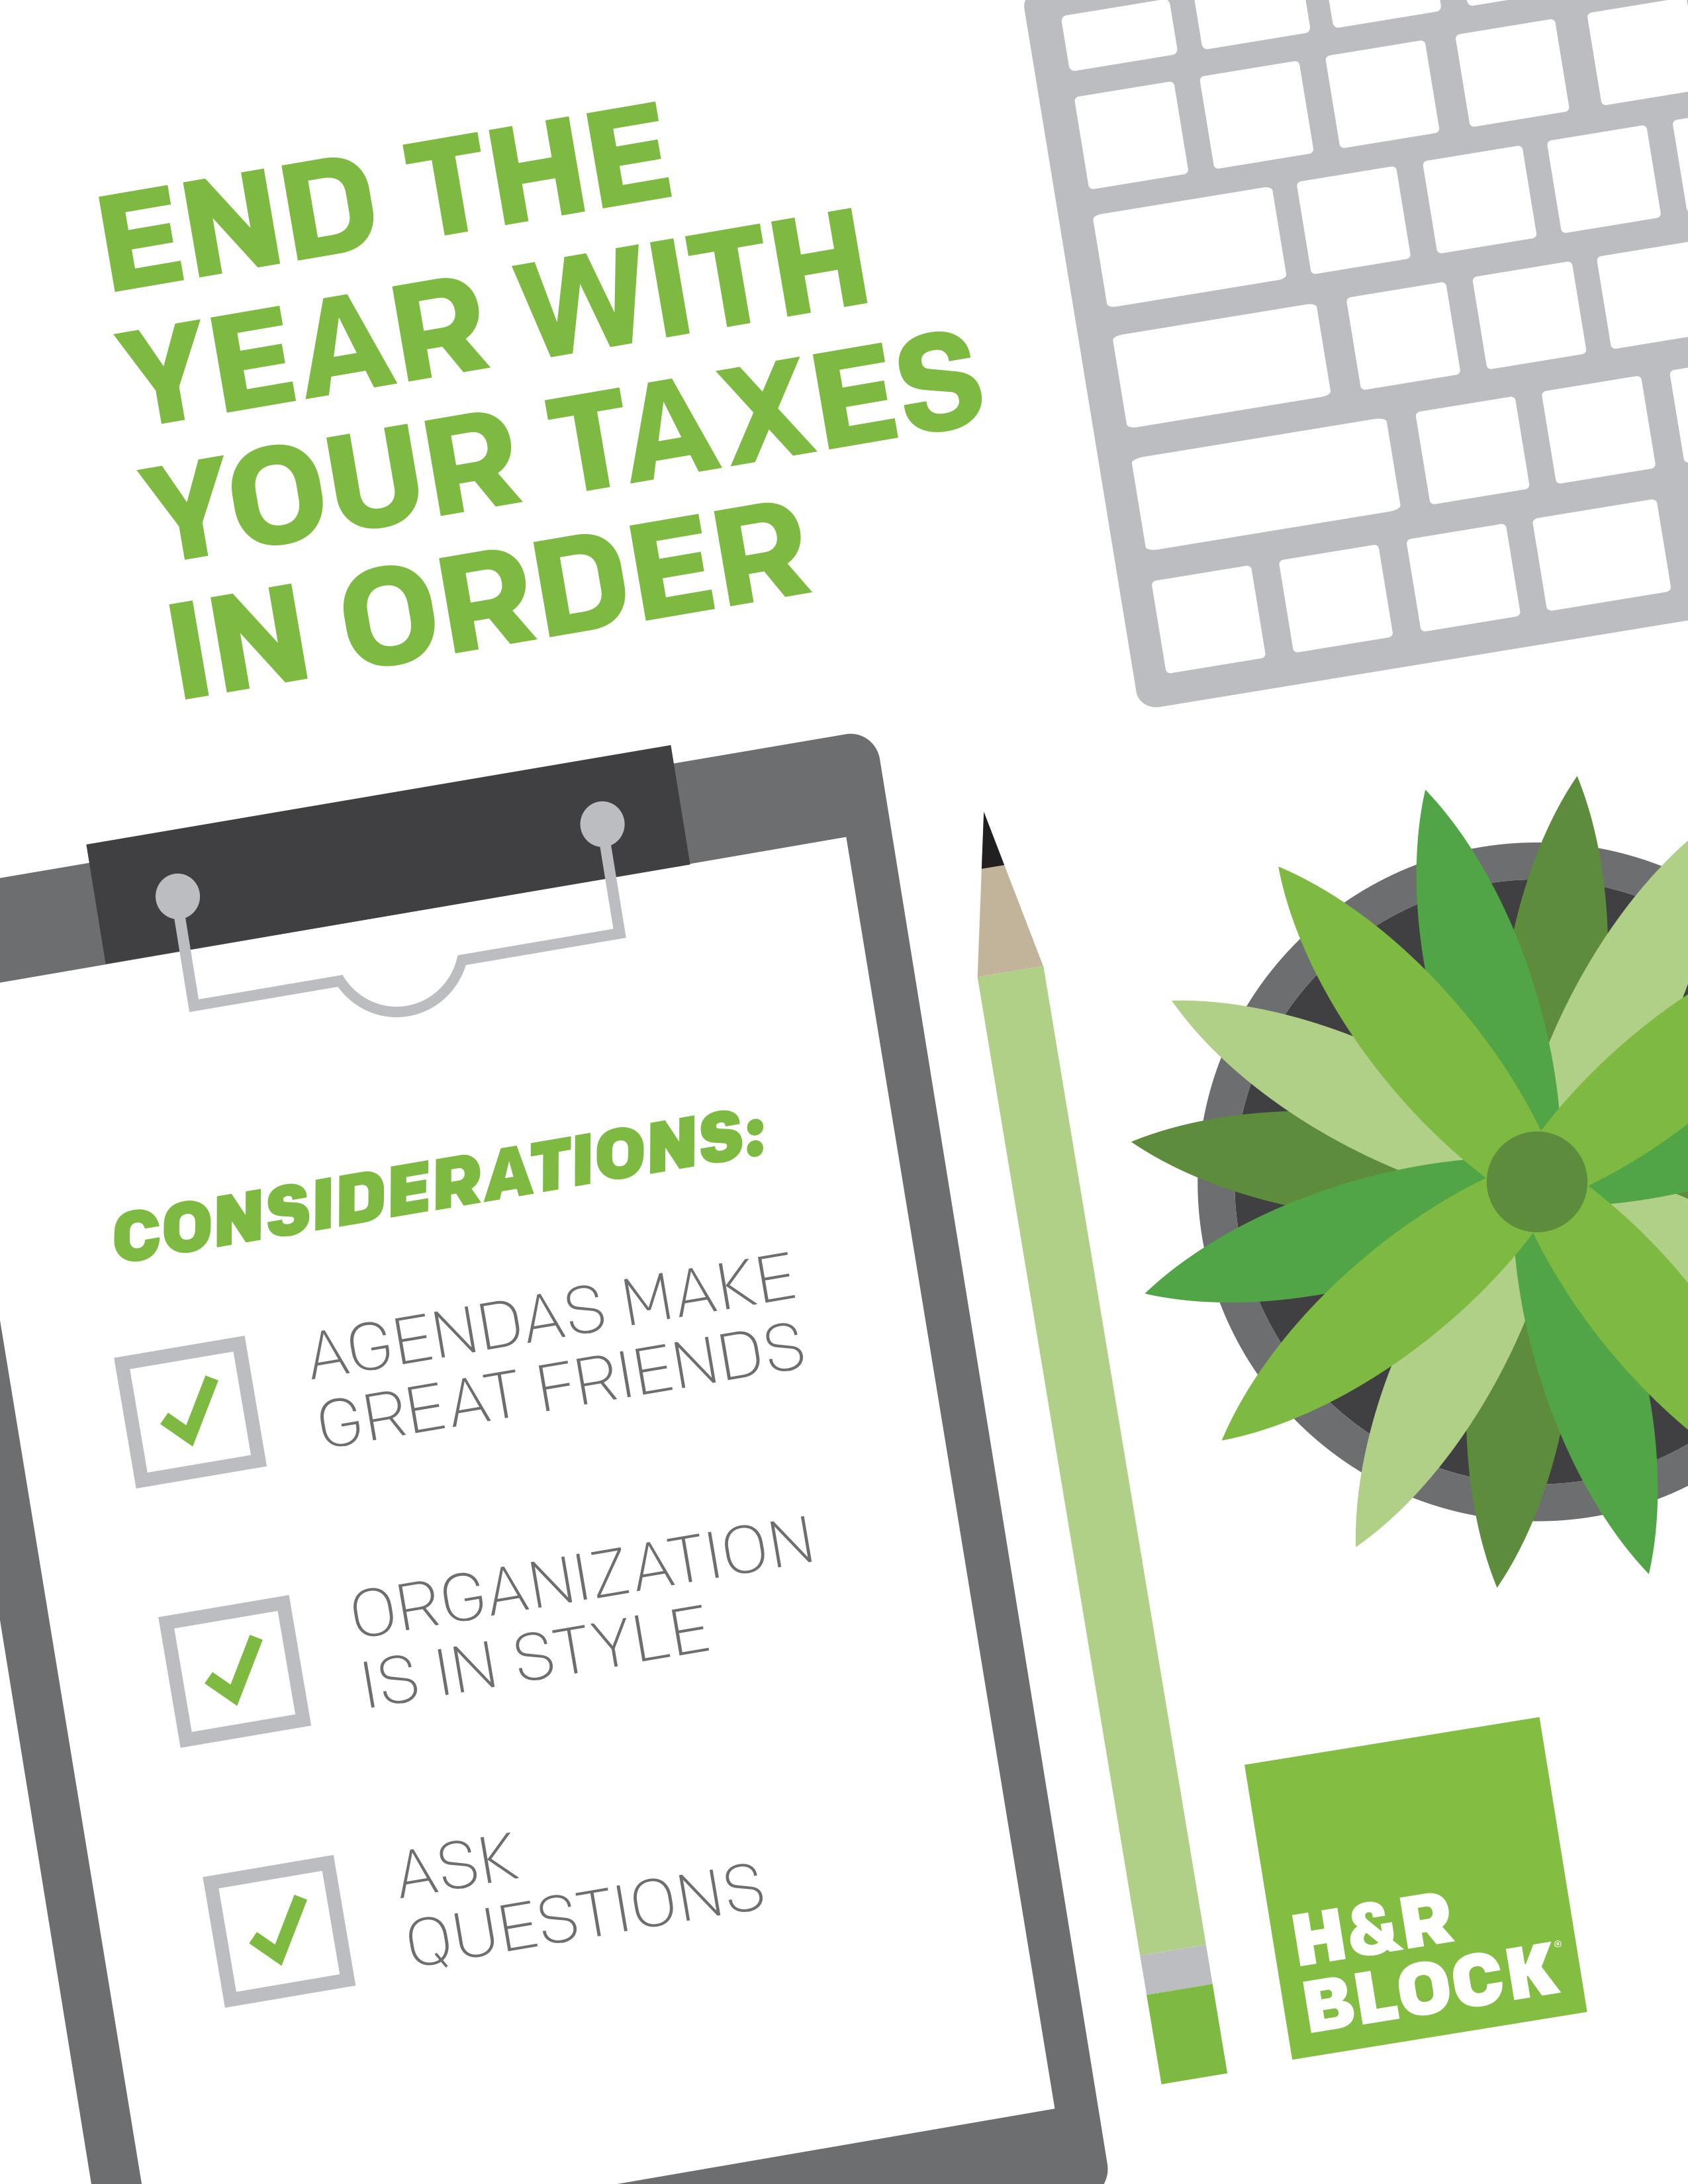
End the year with your taxes in order

By Lisa Gittens, H&R Block

Special to the Financial Independence Hub

At this time of year, you’re likely occupied with decorating for the holidays, cooking an abundance of food for family, and selecting gifts for your Secret Santa exchange. Amidst the placing of ornaments, stringing of lights and baking of cookies, taxes are probably the last thing on your mind: they’re something you’ll think about next year, when you’re reminded it’s officially tax season.

But, believe it or not, the end of a calendar year is the perfect time to review the current state of your filing and get your taxes in order before flipping the page to 2018. To help you do just that, H&R Block offers these tips:

Agendas make great friends

Treat yourself to the gift that keeps on giving: an agenda. With this new friend in tow, you can take advantage of sporadic free time and update it with all relevant tax-related dates so they don’t sneak up on you in 2018. Examples of entries you’d want to include are: February 26, 2018, which marks the day the Canadian Revenue Agency officially opens.

(As a side note, this is actually the latest opening in Canadian history and means Canadians will have a shorter window to file taxes.) April 30, 2018 is another date to keep in mind: it’s the deadline for filing 2017 personal tax returns. (If you’re self-employed, the deadline is June 15, 2018.)

Organization is in style

Hopefully you’ve been saving bills, tuition receipts, transit passes, charitable contribution receipts, health expenses, and other key tax documents this year. When it comes to your tax return, it literally pays (in the form of a tax return!) to retain and organize these documents. Like agendas, accordion-style folders with tabs to separate by category are great gifts to yourself. Just ensure you keep it in reach — and out of harm’s way — so you’ll be more motivated to use it throughout the year. Continue Reading…

What if I sold in May and went away?

At the end of April we wrote a piece looking at some new research on the calendar effect and popular heuristic known as Sell in May and go away.

While there is some evidence that this particular anomaly does exist and has persisted over certain periods of time, there is not really a good theoretical foundation for why it happens.  Mining historical data often yields patterns but assuming that those patterns will repeat can lead to unfortunate investor strategies and behaviours.

It’s in our nature to love short-cuts

Investors just love short-cuts. In fact not just investors love them but people in general always use heuristics to help increase the efficiency of their decision-making.  If you step outside, feel a sudden cool breeze and look up and see a dark cloud in the vicinity you respond fairly quickly and sensibly by seeking shelter or at least grabbing an umbrella as you head out the door.  This ability to create short-cuts makes our lives so much easier and sometimes even keeps us safe.   We recognize patterns that we’ve seen before, assume they’re going to happen again and act almost automatically in response: it simply makes decision-making faster and less difficult. No need to analyze things in detail, just act.

The challenge is that the same heuristics that make decision-making easier and faster or keep us safe in many aspects of our lives can also produce behavioural biases that don’t help us as investors.  We love things like the “January effect” or “Sell in May and go away” because they’re easy and have sometimes worked in the past.  But putting them into practice doesn’t always work out the way we might imagine.

But short-cuts don’t always work with investing

This year is a good case study.  What if we had sold in May and stayed out of the market through until now?  To cut to the chase, you wouldn’t be happy!  A Canadian investor would have missed out on the following returns from May 1 until now (all in Canadian dollar terms – return data from S&P Indices Canada and exchange rates from Bank of Canada as at December 7, 2017):

S&P/TSX Composite Total Return Index: +4.6%

S&P 500 Net Total Return Index (in CAD): +4.7%

S&P Global ex-US Broad Market Net Total Return Index (in CAD): +4.8%

Continue Reading…